






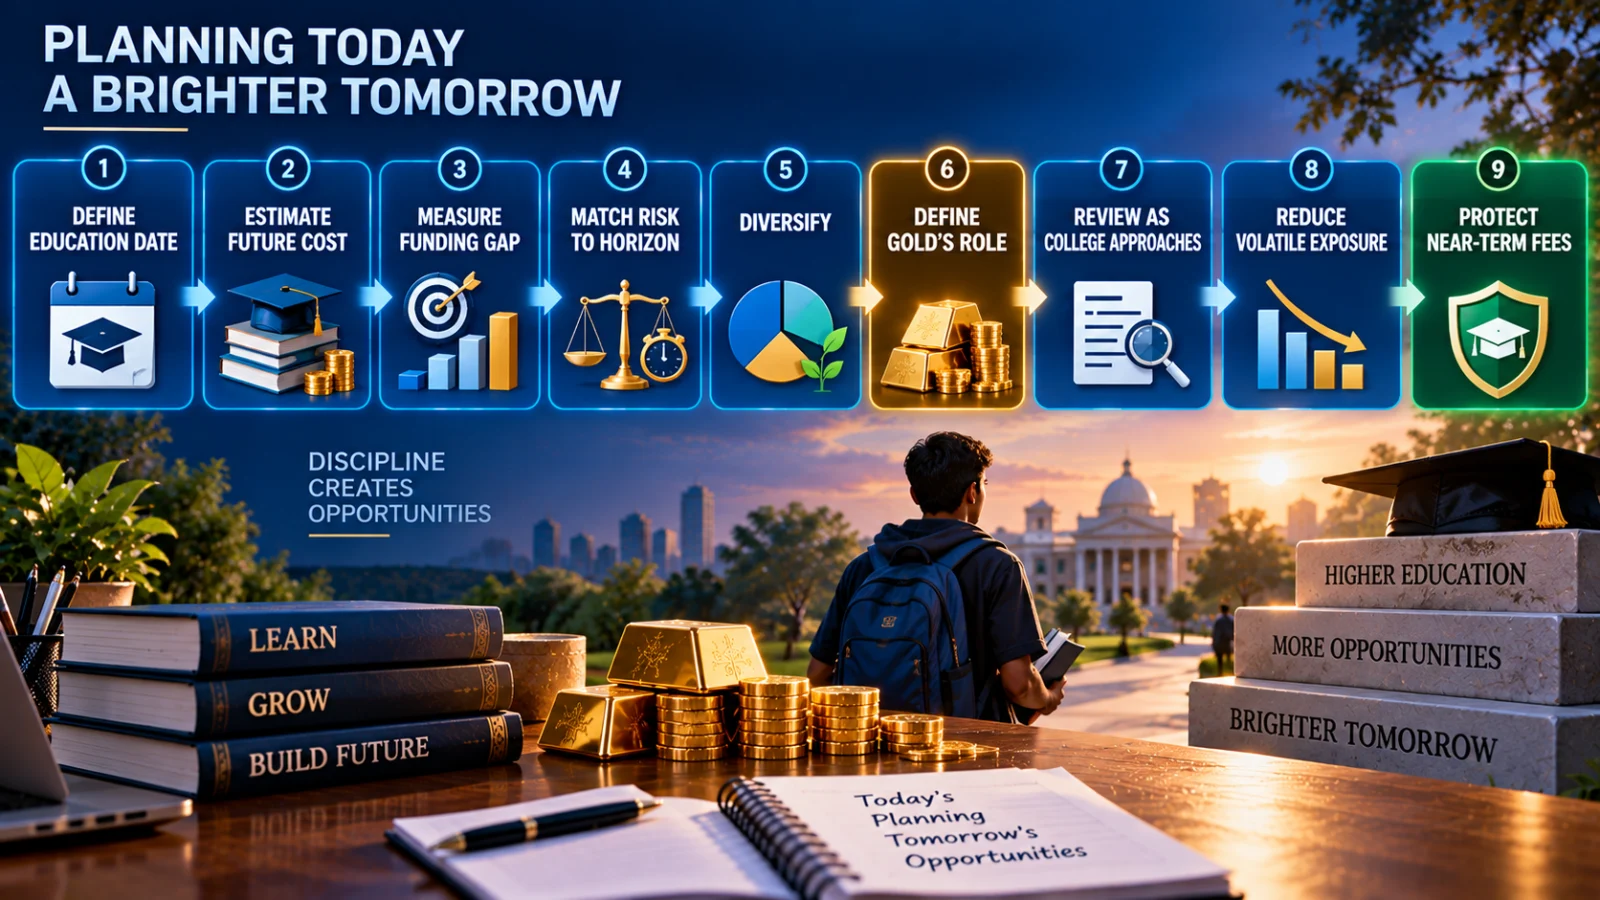
Gold for child education India planning should start with the education date, not with gold. A child’s college fee can become due on a fixed date, while gold has no guaranteed value or recovery date. Gold may have a supporting diversification role, but relying on it as the entire education fund can create a serious timing problem if prices are down when the money is needed.
The central question is therefore not simply whether gold is a good long-term asset. It is whether the education goal can tolerate gold being below a previous peak when the first large fee must be paid.
1. Define the education date
Estimate when the first major college or higher-education payment is likely to be needed. A goal with twelve years remaining can tolerate a different level of market uncertainty from money required next year.
2. Estimate the future liability
Start with today’s approximate education cost and recognise that the future amount may be higher because of inflation. Do not assume one universal education-inflation rate.
3. Measure the funding gap
Compare the future goal with money already earmarked for education and other assets that are genuinely available for the goal.
4. Match risk to the time remaining
The longer the remaining horizon, the more time a diversified portfolio may have to recover from market declines. As the payment date approaches, the ability to tolerate a large drawdown falls.
5. Diversify the accumulation portfolio
Do not make the education outcome depend on one asset class. Diversification cannot prevent losses, but it reduces dependence on one investment behaving favourably at the required moment.
6. Define gold’s role, if any
Gold may contribute diversification, but no reviewed evidence supports making it the universal or complete education portfolio.
7. Reassess as college gets closer
The goal remains the same while the remaining horizon becomes shorter. That change alone can justify reducing dependence on volatile assets.
8. Protect money needed soon
Near-term fees should not depend on gold or another volatile asset recovering at exactly the right time.
Why child education is different from general wealth building
A general wealth portfolio can sometimes wait through a market decline. An education liability is different. Admission and fee schedules can impose a practical payment date, and the family may not be able to postpone the course simply because an investment is temporarily below its previous value.
SEBI’s investor-education material treats a child’s higher studies as a financial goal and emphasises defining goals, investment horizon and risk tolerance before choosing investments. Its financial-goal tools also use years to goal, present cost and inflation as inputs. That sequence matters: the asset should serve the goal rather than the goal being forced to fit the asset.
What if gold is down when college fees are due?
This is the central risk. Gold is market-priced. It can rise substantially, but it can also experience large declines and extended periods below earlier peaks. Historical World Gold Council research documents negative calendar years close to 30% and multiple drawdowns greater than 20% since 1971. Those historical episodes do not predict the next decline, but they show why a future fee should not depend on gold always being near a record high.
If a family has concentrated most of the education corpus in gold and the price is depressed when the fee becomes due, the choices can become uncomfortable: sell at the prevailing price, find money elsewhere, borrow, reduce the planned education spend or delay a decision that may not be easy to delay.
The risk is therefore not only whether gold produces a positive long-term return. It is whether the asset’s value is adequate on the date the liability must be met.
Does that mean parents should avoid gold completely?
No. The evidence does not support a universal zero-gold rule either. Gold has historically provided diversification benefits in portfolios because it can behave differently from other assets. The useful distinction is between gold as one supporting asset and gold as the education plan itself.
SEBI’s investor guidance emphasises diversification rather than dependence on a single investment. For a child’s education, that principle is especially important because the goal has both a target amount and a target date.
Estimate the goal before choosing the asset
A parent cannot sensibly decide how much investment risk the education fund can tolerate without first understanding the liability. Begin with the approximate current cost of the course or education path being planned, then recognise that the future cost may differ materially.
SEBI’s financial-goal planner explicitly incorporates the present cost of the goal, years remaining and inflation. These are planning inputs, not promises. The future institution, course, country, accommodation requirement and fee structure may all change.
The correct output is therefore a planning range or working target that can be reviewed, not a falsely precise prediction of what college will cost many years from now.
Inflation matters, but do not invent one universal rate
Education costs can rise over time, so planning only for today’s fee can leave a future funding gap. But TPS cannot responsibly state that education inflation will always be a particular percentage.
The practical approach is to test the goal against reasonable scenarios and revisit the estimate periodically. If the expected course, institution or country changes, the target corpus may need to change as well.
Why diversification matters for a fixed-date goal
Diversification does not guarantee a profit and does not eliminate market risk. Its role is to avoid making the success of the education goal depend entirely on one asset.
If all of the corpus is in gold, the family is exposed to one market-price path. If all of it is in another volatile asset, the same concentration problem can exist in another form. A diversified structure can spread the sources of risk and return, subject to the parent’s horizon, risk capacity and available regulated products.
The remaining horizon should change the risk discussion
Time matters because a market decline is less disruptive when the payment date is distant than when the fee is due soon. SEBI’s risk-management guidance explicitly links investment type to horizon and cautions against depending on volatile or illiquid investments when money is needed in the near future.
This does not create one universal rule such as “sell gold five years before college.” The appropriate transition depends on the amount already accumulated, other investments, the size and timing of expected fees and the household’s overall financial position.
De-risking does not mean predicting the gold price
As the education date approaches, the objective changes gradually from accumulating wealth to protecting the amount that will soon be spent. That shift does not require a forecast that gold is about to fall.
It is a liability-matching decision. If the family knows that a substantial fee will be required soon, it becomes increasingly difficult to justify leaving that specific near-term amount dependent on a volatile market asset.
A sensible planning principle is therefore to reduce dependence on volatile assets as the spending date becomes near-term, while avoiding a rigid percentage schedule that pretends every household has the same circumstances.
Do not let recent gold performance redesign the goal
A strong recent gold rally can make it tempting to increase exposure simply because the asset has performed well. A decline can create the opposite temptation. Neither reaction changes the underlying education date.
The investment mix should remain anchored to the funding gap, remaining horizon, diversification, risk tolerance and the amount that must become dependable as the fee date approaches.
Should existing jewellery count toward the education fund?
Existing jewellery is still part of a household’s economic gold exposure and should not be ignored when assessing concentration. But it should not automatically be treated as fully available education capital.
Jewellery may include making charges, stones and resale friction, and some pieces may have cultural or emotional importance that makes the family unwilling to sell them. A realistic education plan should distinguish between gold the household owns and gold the household is genuinely prepared and able to convert into college funding.
There is no universal gold percentage for child education
No controlling evidence reviewed by TPS establishes that every Indian parent should put 5%, 10%, 15% or any other fixed percentage of a child’s education corpus in gold.
The appropriate role depends on the years remaining, required corpus, other assets, liquidity needs, household risk capacity and existing gold exposure. A percentage copied from somebody else’s portfolio can therefore create false precision.
What should be protected before the fee date?
The most important shift happens when a future goal becomes a near-term liability. Money that will soon be required for admission deposits, tuition or other unavoidable education costs should no longer depend heavily on a favourable gold price or another volatile market outcome.
This does not mean every education expense must be held in one particular product. It means the family should be able to pay the known near-term obligation without needing a market recovery first.
A practical way to review the plan
Review the education plan periodically and whenever something material changes: the child chooses a different course or country, the estimated cost rises, household income changes, a major new asset or liability appears, or the remaining horizon becomes much shorter.
The question at each review is simple: If the education payment were required at the end of the remaining horizon, how much of the goal still depends on markets behaving favourably?
That question is more useful than trying to predict whether gold will be higher or lower next year.
Bottom line
Gold can play a supporting role in a child’s education portfolio, but the education date should control the plan. The goal has a future liability that may not be flexible, while gold has no guaranteed price or recovery date. Start with the expected cost and horizon, account for inflation uncertainty, diversify rather than depend on one asset, and reduce reliance on volatile assets as the fee date approaches.
The purpose is not to eliminate every investment risk. It is to avoid reaching the college deadline with a corpus that can meet the goal only if gold happens to be trading at a favourable price.
Verification note
TPS reviewed SEBI investor-education material on financial goals, investment horizon, diversification, asset allocation, portfolio review and near-term risk, together with World Gold Council research on gold diversification, volatility and historical drawdowns. The evidence supports a goal-matching framework, not a universal gold allocation or future-return forecast.
Limitations and unresolved facts
Future gold returns, education inflation, course fees, tax rules and product rules are unknown. The appropriate asset mix and de-risking path depend on the household’s existing corpus, other goals, risk capacity, liquidity and the actual education timeline. Historical gold drawdowns do not predict when the next decline will occur, and industry research from the World Gold Council should not be treated as personalised investment advice.