
UPI payments up to ₹2,000 now have an explicit statutory no-charge protection under a September 14, 2026 Finance Ministry notification. The notification specifies UPI transactions up to ₹2,000 under Section 10A of the Payment and Settlement Systems Act and says no bank or system provider may impose a direct or indirect charge on a person making or receiving such a payment.
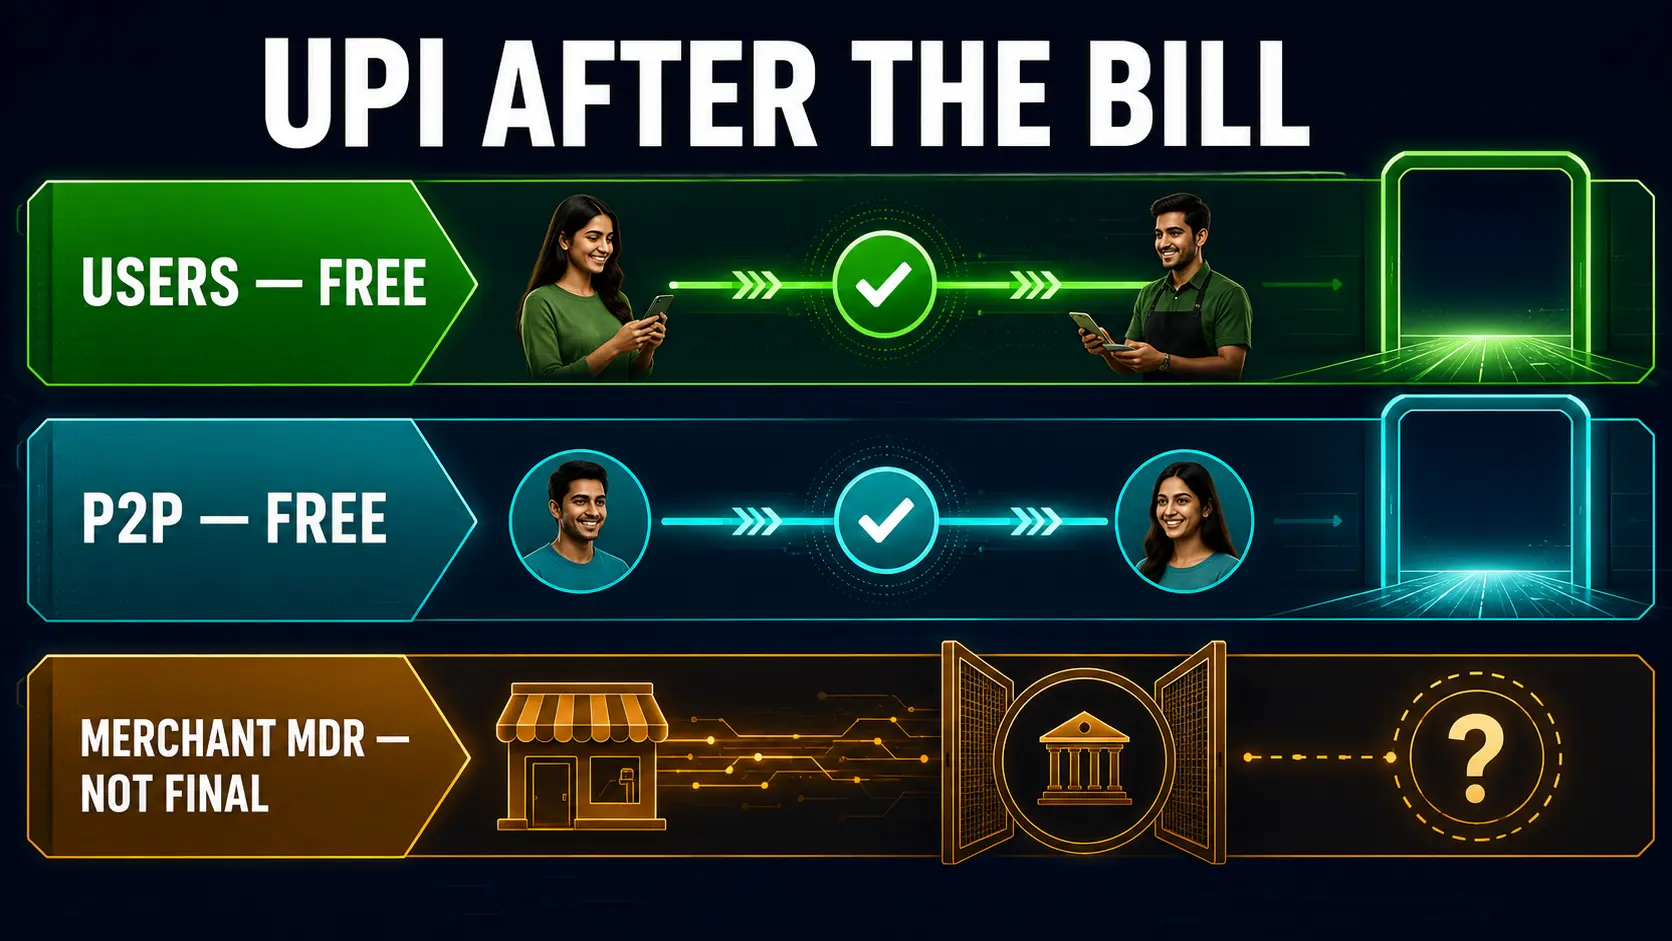
This does not mean every UPI payment above ₹2,000 is now chargeable. The notification defines the transactions protected by the Section 10A no-charge rule; it does not itself announce an MDR percentage, merchant category, charging mechanism or implementation rule for UPI payments above ₹2,000. The Government’s stated position also remains that consumers and person-to-person, or P2P, UPI payments will remain free.
Direct answer
Will ordinary UPI users have to pay?
No general consumer UPI transaction charge has been announced. The Government says consumers will not face UPI transaction charges and P2P payments will remain free.
What is now clear
What does the ₹2,000 rule mean?
UPI transactions up to ₹2,000 are expressly protected from direct or indirect charges by banks and system providers. The charging or MDR framework above ₹2,000 is still not specified by this notification.
₹2,000 is now an official legal boundary for the no-charge protection. It should no longer be described only as an older incentive threshold. But the notification does not say that transactions above ₹2,000 automatically attract a fee.
What changed on September 14, 2026?
The Ministry of Finance’s Department of Financial Services issued Notification S.O. 5067(E) under Section 10A of the Payment and Settlement Systems Act, 2007.
The notification specifies two electronic payment modes for the statutory no-charge protection:
- debit cards powered by RuPay; and
- UPI transactions up to ₹2,000.
It further states that no bank or system provider may impose, directly or indirectly, any charge on a person making or receiving a payment through those specified modes.
This is a material step beyond the earlier August clarification because the Government has now formally specified ₹2,000 in the Section 10A notification.
Seven facts about UPI charges after the 2026 Act
| Question | Current answer | What remains unresolved? |
|---|---|---|
| 1. Are ordinary UPI users being charged? | No general consumer UPI transaction charge has been announced. The Government says consumers will continue to use UPI without transaction charges. | The September notification does not create a general user fee above ₹2,000. |
| 2. Are P2P UPI transfers free? | Yes. The Government’s stated position is that all person-to-person UPI transactions will continue to be free. | No current official reversal of that position was identified. |
| 3. What is protected up to ₹2,000? | UPI transactions up to ₹2,000 are now expressly specified under Section 10A, and banks or system providers cannot impose direct or indirect charges on the payer or receiver. | The notification does not by itself describe every commercial arrangement outside this protected band. |
| 4. Does a UPI payment above ₹2,000 automatically attract MDR? | No. The notification removes the blanket statutory protection above the specified ₹2,000 band, but it does not itself impose an MDR or other fee on every higher-value payment. | A separate operative framework would still be needed to establish who is charged, at what rate and for which transactions. |
| 5. Has the merchant MDR rate been announced? | No final MDR percentage for higher-value ordinary UPI merchant transactions was identified in the September 14 notification. | The rate and detailed commercial framework remain unresolved. |
| 6. Is ₹2,000 now an official UPI charging threshold? | ₹2,000 is now the official upper boundary of the UPI transactions expressly protected from direct or indirect charges under this Section 10A notification. | It should not be described as proof that every transaction above ₹2,000 will be charged. |
| 7. Do PhonePe, Google Pay or other UPI apps now have to charge users above ₹2,000? | No such universal user charge follows from the notification. | Any future merchant-side or provider-side charging framework above the protected band needs its own controlling rules. |
What happened to the earlier promise that UPI would stay free?
The Ministry of Finance said on August 8 that consumers making UPI payments would not face transaction charges, all P2P transactions would remain free and any future MDR would apply only to a limited set of merchant transactions above a threshold at a nominal rate.
The September 14 notification now supplies an important legal detail that was missing from that statement: UPI transactions up to ₹2,000 are the transactions expressly specified for the Section 10A no-charge protection.
The two statements are not the same thing. One describes the Government’s broader policy position for consumers and P2P payments; the other defines the payment modes and transaction band protected by the statutory prohibition on charges.
Does the new rule mean UPI above ₹2,000 will cost money?
Not automatically. A transaction being outside the expressly protected ₹2,000 band is not the same as a fee having been imposed.
For a higher-value UPI payment to become chargeable under a specific framework, readers would still need a controlling rule or commercial decision explaining matters such as:
- whether MDR or another charge is actually introduced;
- which merchant transactions are covered;
- which merchants or merchant categories are affected;
- the MDR percentage or other rate;
- who bears the charge; and
- the effective date.
The September 14 notification does not provide those details.
What does MDR mean?
MDR, or Merchant Discount Rate, is a payment-processing charge associated with merchant transactions. It is different from a consumer being charged simply for sending a normal P2P UPI transfer.
The Government’s August position was that if MDR is introduced, it would apply only to a limited set of merchant transactions above a threshold, at a nominal rate substantially below typical debit- or credit-card MDR, while the vast majority of merchant UPI transactions would remain free.
Has the MDR rate above ₹2,000 been fixed?
No final MDR rate was identified in the September 14 Section 10A notification. The notification establishes the ₹2,000 no-charge protection boundary but does not state a merchant MDR percentage for transactions above it.
That distinction is important: the Government has now resolved the statutory protected band, but the operational charging rate and detailed merchant-side framework remain separate questions.
Do not read “free up to ₹2,000” as “charged above ₹2,000.” The first statement is now a notified legal protection. The second would require additional evidence showing an actual charge, rate and applicability rule.
What does this mean for a ₹2,500 UPI payment?
The September 14 notification does not allow a universal answer that a ₹2,500 UPI payment will incur a fee. It only establishes that the specific Section 10A prohibition on direct or indirect charges applies to UPI transactions up to ₹2,000.
For a payment above ₹2,000, the user should check the current Government, RBI, NPCI, bank or payment-provider rule that actually governs that transaction. A future MDR may also be merchant-side rather than a direct customer fee.
Can a merchant pass an MDR charge to the customer?
The current evidence does not establish a universal pass-through rule for a future higher-value UPI MDR framework. The September notification itself prohibits direct or indirect charges only within the specified protected modes and transaction band; it does not publish the complete merchant charging framework above ₹2,000.
Consumers should therefore avoid assuming either that a merchant can automatically surcharge every UPI payment above ₹2,000 or that no commercial rule can ever apply above that amount. The controlling future framework will matter.
What should UPI users check before believing a charge message?
- Check whether the payment is ₹2,000 or below. That UPI band now has an explicit no-charge protection under the September 14 notification.
- Check whether the claim concerns a consumer fee, a P2P transfer or a merchant MDR.
- For amounts above ₹2,000, look for the actual rate, merchant scope and effective date in a current controlling notification or official rule.
- Do not assume that being outside the protected band means a fee automatically applies.
- Do not confuse separate optional app services, credit products or card-on-UPI arrangements with ordinary bank-account UPI payments.
“UPI above ₹2,000 is now chargeable” is too broad. The Government has notified a protected no-charge band up to ₹2,000, but the notification does not itself impose a universal fee above that amount.
Official and current sources
- Gazette notification S.O. 5067(E), September 14, 2026 — reproduced Gazette text and official-source reference
- Ministry of Finance — No Charges for UPI Users, August 8, 2026
- Reuters — India bars bank charges on UPI payments up to ₹2,000, September 14, 2026
- NPCI — Unified Payments Interface
Verification
ThePulseSignal reviewed the September 14 Gazette notification text, current reporting on the notification and the Ministry of Finance’s August consumer/P2P clarification. The new notification expressly protects UPI transactions up to ₹2,000 from direct or indirect charges by banks and system providers. It does not itself establish an MDR percentage or universal charge for UPI transactions above ₹2,000.
Last verified: September 15, 2026.
Limitations
- The September 14 notification specifies the no-charge protected UPI band up to ₹2,000 but does not itself set a merchant MDR percentage above that amount.
- No universal rule charging every UPI transaction above ₹2,000 was identified.
- Detailed merchant categories, eligibility, charging mechanism and effective date for any future higher-value MDR framework remain unresolved.
- The Government’s broader position remains that consumers and P2P UPI transactions will stay free, but later controlling notifications should be checked if a specific higher-value transaction is said to attract a charge.
- RuPay credit-card-on-UPI and other separately priced payment products should not be treated as evidence of a universal charge on ordinary bank-account UPI.
Bottom line
UPI transactions up to ₹2,000 now have an explicit legal no-charge protection. Banks and system providers cannot impose direct or indirect charges on the payer or receiver for those transactions. That is a real change from the earlier state in which the threshold had not yet been formally specified. But it is equally important not to overread the notification: it does not say every UPI payment above ₹2,000 will be charged, and it does not set the final MDR rate or detailed merchant framework for higher-value transactions.