
FCNR(B) and NRE deposits continue to be available after the RBI’s temporary 2026 rate relaxation ended. What changed is the regulatory boundary within which banks price qualifying new and renewed deposits.
For an NRI deciding whether to open or renew a deposit, the useful question is no longer simply what happened on August 31. It is which RBI rule applies to the deposit now, and what rate is the bank actually offering within that framework?
Direct answer: NRE deposits and FCNR(B) deposits remain available. NRE rates are governed by the applicable RBI restriction relative to comparable domestic rupee term deposits, while FCNR(B) ceilings depend on the deposit tenor and the relevant currency benchmark. Always use the bank’s current rate card for the actual customer rate.
What happened to the temporary RBI relaxation?
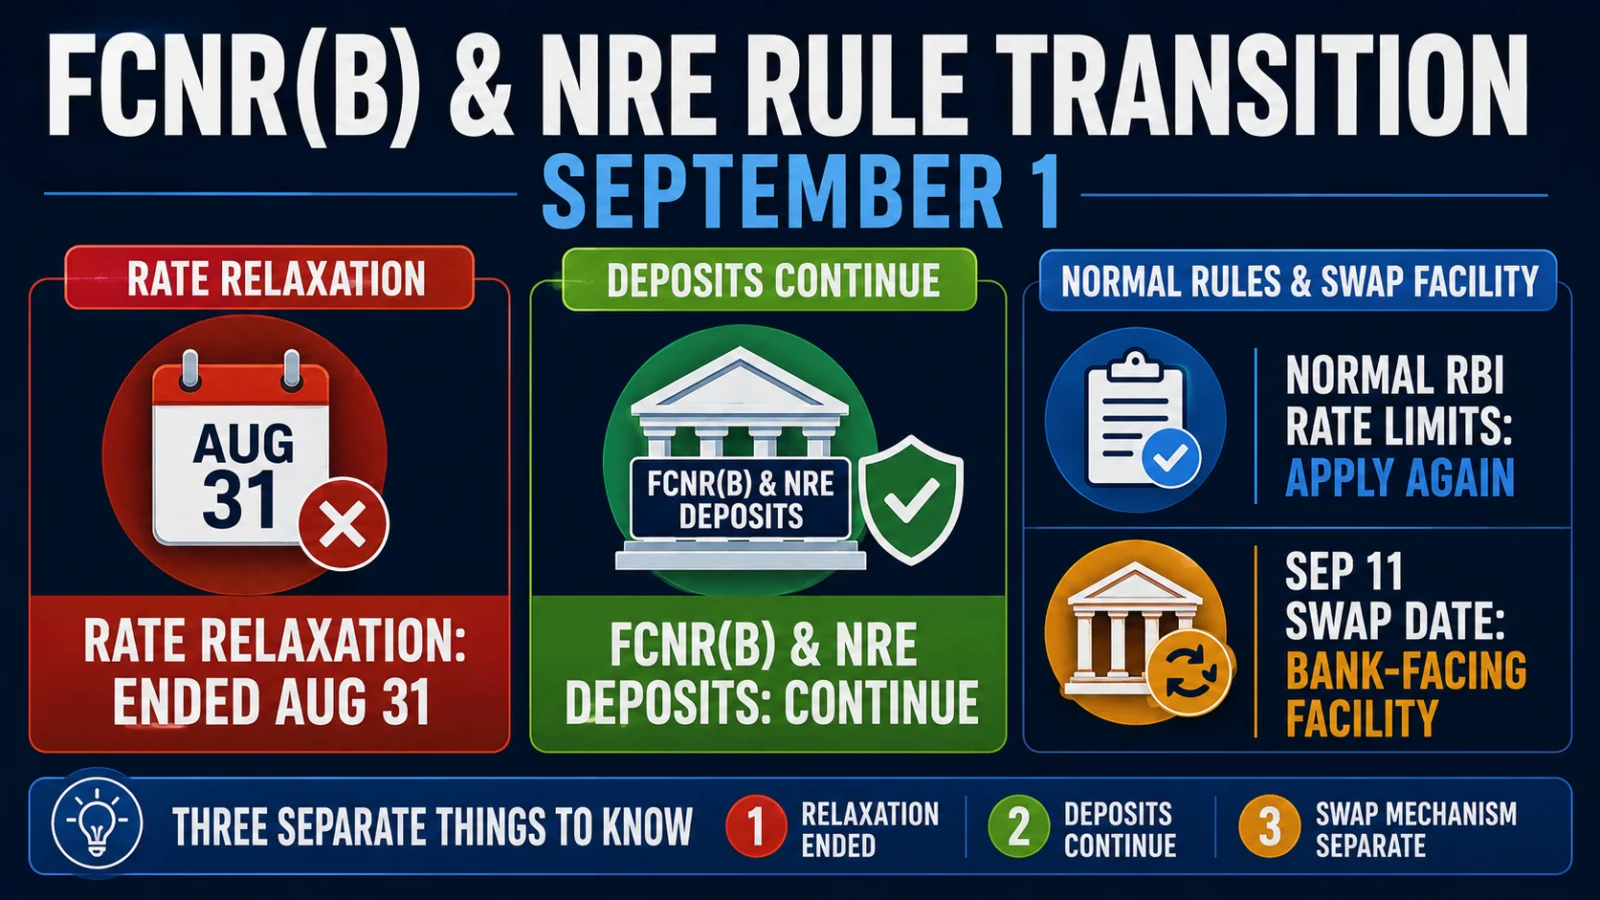
RBI temporarily relaxed the normal interest-rate restrictions in June 2026 for specified longer-tenor FCNR(B) and NRE deposits.
The relaxation covered qualifying fresh deposits and deposits renewed on maturity. RBI later amended the end date so that the temporary treatment expired on August 31, 2026.
That expiry is now historical context. It does not mean the deposit products ended.
Are FCNR(B) deposits still available?
Yes. Banks continue to publish FCNR(B) deposit rates after September 1.
For example, current bank rate cards reviewed by TPS show FCNR(B) pricing effective September 1 and September 7, confirming that FCNR(B) remains an active deposit product after the temporary relaxation expired.
Are NRE deposits still available?
Yes. NRE savings and term-deposit products also continue.
The August 31 change concerned a temporary interest-rate exemption for specified longer-tenor deposits. It did not close NRE accounts or prohibit banks from accepting new NRE term deposits.
What is the normal RBI rule for NRE term-deposit rates?
Under the RBI deposit framework applicable to commercial banks, interest rates on NRE and NRO term deposits are subject to the applicable restriction relative to rates offered on comparable domestic rupee term deposits.
The temporary 2026 relaxation removed that restriction for qualifying fresh or renewed NRE deposits of three years and above during the special window. With that temporary treatment over, the ordinary restriction again controls qualifying deposits.
This does not create one RBI-set NRE rate. Banks still set their own customer rates, but those rates must remain within the applicable regulatory boundary.
How are FCNR(B) rate ceilings different?
FCNR(B) deposits are denominated in permitted foreign currencies, so their regulatory ceilings are linked to currency-specific benchmarks rather than to domestic rupee deposit rates.
Under the ordinary framework reviewed for this article:
- FCNR(B) deposits from one year to less than three years use the applicable Overnight Alternative Reference Rate or swap benchmark plus the permitted RBI spread for that maturity band.
- FCNR(B) deposits from three years to five years are subject to the relevant Overnight Alternative Reference Rate or swap benchmark plus 350 basis points under the ordinary framework.
Because the reference rate differs by currency, there is no single universal maximum FCNR(B) percentage that applies across USD, GBP, EUR, CAD, AUD and other permitted currencies.
Does RBI decide the exact FCNR(B) rate my bank must pay?
No. RBI defines the regulatory ceiling. The bank determines the actual offered rate within that ceiling.
This is why two banks can publish different FCNR(B) rates for the same currency and tenor without either rate necessarily violating RBI rules.
Why can bank FCNR(B) rates change during the same month?
Banks can revise their published rate cards subject to the applicable RBI framework and their own approved deposit-pricing policies.
Current September evidence illustrates this. Central Bank of India publishes FCNR(B) rates effective September 1, while Tamilnad Mercantile Bank publishes another rate schedule effective September 7.
The applicable customer rate therefore needs to be checked for the actual booking or renewal date.
What should you check before opening an FCNR(B) deposit?
- Currency: identify whether the deposit is in USD, GBP, EUR, CAD, AUD or another permitted currency offered by the bank.
- Tenor: confirm the exact maturity band because the RBI ceiling structure differs by tenor.
- Rate-card effective date: use the bank’s latest published rate rather than an older promotional screenshot.
- Deposit amount: some banks publish different pricing or product conditions by deposit size.
- Premature withdrawal: check whether a penalty applies and how interest is recalculated if the deposit is closed early.
- Renewal instruction: verify the rate that will apply when a maturing deposit is renewed.
What should you check before opening or renewing an NRE deposit?
- Check the bank’s current NRE term-deposit rate card.
- Confirm the exact tenor and deposit amount.
- Check whether the quoted rate is effective on the date of booking or renewal.
- Review premature-withdrawal conditions.
- Do not assume a rate advertised during the temporary relaxation is still available.
- Use the bank’s current deposit advice or confirmation as the customer-specific record.
What happens to a deposit that was already booked?
The end of the temporary relaxation does not by itself establish that an already contracted deposit must be repriced before maturity.
The customer’s existing rate and premature-withdrawal treatment depend on the deposit contract and applicable bank terms.
For a renewal, however, the bank’s rate and regulatory framework applicable on the renewal date become important.
Does every bank have to cut its rate after a regulatory ceiling returns?
No automatic universal cut can be inferred.
If a bank’s existing customer rate already falls within the applicable normal RBI limit, restoration of the ceiling does not by itself prove that the bank must reduce that rate.
The correct comparison is between the bank’s actual rate and the applicable regulatory boundary for that product, currency and tenor.
What was the separate FCNR(B) swap facility?
RBI also introduced a separate USD-INR swap facility linked to eligible FCNR(B) deposits mobilised by banks.
That mechanism is primarily bank-facing and should not be confused with the ordinary retail question of whether an NRI can continue to hold, open or renew an FCNR(B) deposit.
The temporary mobilisation and swap timelines were part of the 2026 policy response. They do not replace the ordinary FCNR(B) deposit framework for future customer decisions.
Do not confuse three different things: the temporary rate relaxation, the bank-facing RBI swap facility and the continuing FCNR(B)/NRE deposit products are separate regulatory and banking states.
Can an old promotional FCNR(B) rate still be trusted?
Only if the bank confirms that the rate is still effective for the deposit date, tenor, currency and amount involved.
Rate pages can change after RBI policy windows close or when market benchmarks move. A screenshot or article quoting an older rate should therefore not replace the bank’s current rate card.
Examples of current post-expiry bank pricing
TPS reviewed current bank pages after the August 31 expiry to verify that the market had moved into ongoing post-relaxation pricing rather than discontinuing FCNR(B) deposits.
- Central Bank of India publishes FCNR(B) rates effective September 1, 2026.
- Cosmos Bank publishes FCNR(B) rates applicable during September 2026.
- Tamilnad Mercantile Bank publishes revised FCNR(B) rates effective September 7, 2026.
These are implementation examples, not a recommendation to use any particular bank and not proof that one bank offers the best rate.
Does the highest advertised rate automatically mean the best deposit?
No. Rate is only one part of a deposit decision.
An NRI may also need to consider currency exposure, tenor, premature-withdrawal conditions, remittance needs, renewal settings, account servicing and the tax treatment applicable to the individual.
What could change this answer later?
- RBI could amend the ordinary FCNR(B) ceiling or NRE rate restriction.
- RBI could announce another temporary relaxation.
- Currency benchmark rates used for FCNR(B) ceilings can change.
- Banks can revise their offered rates within the regulatory framework.
- Deposit-product terms can change independently of the RBI ceiling.
Verification method
ThePulseSignal checked RBI’s August 25 amendment that ended the temporary FCNR(B) and NRE rate relaxation on August 31 and reviewed the ordinary RBI deposit-rate framework that remains relevant after the expiry. TPS also checked current September bank rate cards from Central Bank of India, Cosmos Bank and Tamilnad Mercantile Bank to verify that FCNR(B) products continue under post-expiry pricing. No later RBI direction restoring the expired relaxation was identified in the current review.
Limitations and unresolved facts
- Bank-specific rates can change after this review.
- TPS does not determine the applicable FCNR(B) benchmark for an individual deposit at a future booking date.
- Customer-specific treatment depends on the bank’s current rate card and deposit contract.
- The post-expiry bank examples are implementation evidence, not a comprehensive comparison of all banks.
- This article does not provide personalised investment or tax advice.
- A later RBI amendment can supersede the current regulatory framework.
Frequently asked questions
Are FCNR(B) deposits still available after August 31, 2026?
Yes. Banks continue to publish FCNR(B) rates after the temporary relaxation ended.
Are NRE deposits still available?
Yes. The expiry affected a temporary interest-rate relaxation, not the existence of NRE deposits.
What is the normal FCNR(B) ceiling for three-to-five-year deposits?
Under the ordinary framework reviewed for this article, the ceiling is linked to the relevant currency’s Overnight Alternative Reference Rate or swap rate plus 350 basis points.
Does RBI set one FCNR(B) rate for every bank?
No. RBI sets the regulatory framework and ceiling; banks set customer rates within that framework.
Can two banks offer different FCNR(B) rates?
Yes. Different bank rates can coexist as long as each complies with the applicable RBI framework.
Does an existing FCNR(B) or NRE deposit get repriced automatically?
The expiry does not by itself establish automatic repricing of an already contracted deposit. Check the deposit’s terms and the servicing bank’s instructions.
What should I check before renewing?
Check the latest bank rate card, effective date, tenor, currency where applicable, deposit amount and premature-withdrawal terms.
Bottom line: the temporary 2026 RBI relaxation has ended, but FCNR(B) and NRE deposits continue. The durable rule is to identify the applicable RBI rate framework and then check the bank’s current customer rate for the exact currency, tenor and booking or renewal date.
Last verified: September 8, 2026.