
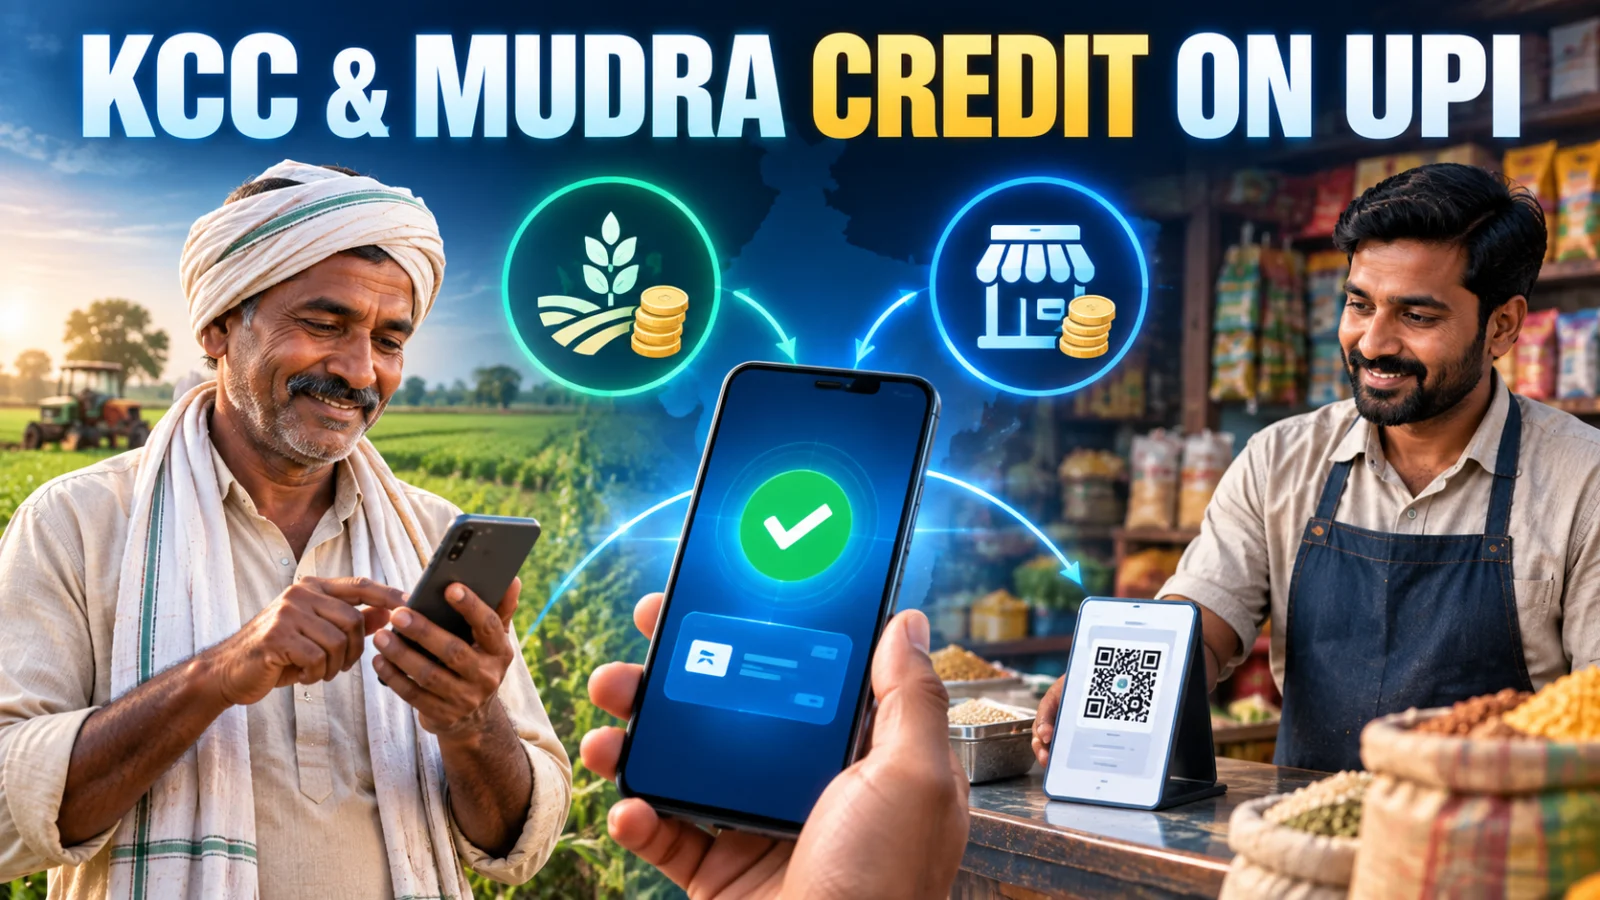
KCC and MUDRA credit on UPI allows eligible borrowers to link an already-sanctioned Kisan Credit Card or PM MUDRA credit facility to UPI where their bank and account are supported. Current Global Fintech Fest 2026 reporting shows that the facility is already live through multiple banks, while additional participating banks were still moving into live availability.
The key distinction is that this is not a new KCC loan, a new MUDRA loan or a universal instant-credit entitlement. The borrower must already have an eligible sanctioned credit facility. Whether it appears in a UPI app still depends on the lender, account, implementation state and supported UPI route.
What changed for KCC and MUDRA borrowers
RBI introduced the broader Credit Line on UPI framework in September 2023, allowing pre-sanctioned bank credit lines to be used as UPI funding accounts. The September 2026 development extends that payment infrastructure to eligible KCC and PM MUDRA credit facilities.
KCC-on-UPI was not completely new in September 2026: SBI had previously disclosed Credit Line on UPI enablement for KCC. The current development is therefore better understood as a broader KCC and PM MUDRA rollout rather than the invention of credit-on-UPI itself.
How to check whether your KCC or MUDRA credit can be used on UPI
The facility uses existing sanctioned credit. It should not be interpreted as an automatic new loan available merely because a person uses UPI.
Current GFF reporting describes multiple banks as live or moving live, but the published implementation details are not sufficient to assume that every KCC and PM MUDRA product at every participating bank has identical availability.
Bank participation does not prove that every KCC or MUDRA account is already enabled. Borrowers should check the current lender and supported UPI-app instructions for their account.
Current GFF reporting confirms UPI payment use and includes a PM MUDRA demonstration in which a Bank of Baroda account was linked to a UPI app. Do not assume that every transaction type demonstrated or reported is enabled identically for every bank, account or credit product.
Which banks support KCC and MUDRA credit on UPI?
September 2026 reporting from Global Fintech Fest shows a rollout across a group of participating banks, but the evidence needs to be read carefully because different reports describe the implementation from different angles.
Economic Times reporting listed ten banks for Kisan Credit Card credit-line use through UPI: State Bank of India, Bank of Baroda, Punjab National Bank, Union Bank of India, Indian Bank, Canara Bank, Indian Overseas Bank, IDBI Bank, Bank of Maharashtra and UCO Bank. The same report listed eight banks for PM MUDRA: State Bank of India, Punjab National Bank, Bank of Baroda, Union Bank of India, Canara Bank, Indian Overseas Bank, IDBI Bank and UCO Bank.
Separate ETBFSI coverage from the GFF demonstration reported that seven banks were already live on the Credit Line on UPI facility and that Union Bank of India, IDBI Bank and UCO Bank were going live. These descriptions should not be treated as proof that every listed bank had identical live status for both KCC and PM MUDRA at the same moment.
For that reason, the safest borrower-level test remains the actual account state: check whether your bank supports your specific KCC or PM MUDRA facility and whether that sanctioned account appears as an eligible credit funding source through a supported UPI route.
What can the linked credit line be used for?
Merchant and business-payment use is clearly supported by current reporting. Eligible borrowers can use sanctioned credit through UPI instead of relying only on money held in a deposit account when making supported transactions.
Current GFF coverage also provides more implementation detail than the launch summary alone. ETBFSI reported a demonstration in which a small shopkeeper with a Bank of Baroda MUDRA account linked the account to a UPI app by scanning a QR code; once linked, the credit line could be used for payments to vendors and suppliers, and the demonstration was described as supporting sending and receiving funds.
That demonstration should not be generalized into a promise that unrestricted person-to-person transfers or every ordinary UPI function is available against every KCC or PM MUDRA credit line. Transaction permissions can depend on the product, lender, account, app and implementation rules. Verify the functions actually offered for your linked credit account before relying on them.
Does every KCC or MUDRA borrower get this automatically?
No. The rollout applies to eligible borrowers with existing sanctioned credit at supported institutions. Having a KCC or PM MUDRA facility does not by itself prove that the account is already enabled as a UPI credit funding source.
The practical verification should happen at the account level: confirm that the sanctioned facility remains active, check that the bank supports the relevant credit product, and follow the lender or supported UPI-app linking process.
What about interest, fees, repayment and transaction limits?
The credit being used remains a bank-sanctioned borrowing facility. Applicable interest, repayment terms, available credit and account conditions therefore depend on the underlying KCC or PM MUDRA arrangement and the lender’s implementation.
The current evidence does not establish one universal September 2026 interest rate, transaction cap, daily limit, fee structure or repayment process covering every participating bank. Borrowers should verify those terms with their lender before using the linked credit facility.
What has not changed
The rollout does not replace normal KCC or PM MUDRA eligibility and sanction processes. It does not mean that scanning a UPI QR code automatically creates a new loan. It also does not establish that every UPI application, bank or eligible account has been enabled simultaneously.
The underlying RBI Credit Line on UPI framework predates the September 2026 rollout. The important current change is the extension and broader implementation of that framework for KCC and PM MUDRA sanctioned credit.
What borrowers should verify before using it
Check the exact sanctioned account, your bank’s current live status for the relevant product, available credit, supported UPI linking route and transaction scope. If the credit facility is not visible in a UPI app, do not assume that the sanctioned loan has disappeared or that you are necessarily ineligible; implementation may still be bank-, account-, product- or app-specific.
What remains unresolved
A direct September 2026 DFS or NPCI implementation document providing a complete bank-by-bank, product-by-product and app-by-app matrix was not recovered in the current evidence. The reviewed GFF reports also use different descriptions of participating-bank and live-rollout status.
Exact account enablement, app support, bank-specific transaction limits, interest or fee treatment, repayment handling, merchant restrictions, person-to-person functionality and KCC end-use controls therefore should not be assumed to be universal.
Verification note: ThePulseSignal reviewed the RBI’s original Credit Line on UPI framework, NPCI’s framework-launch material, SBI evidence showing earlier KCC enablement and current Global Fintech Fest 2026 reporting describing the KCC and PM MUDRA rollout. Current GFF coverage adds implementation evidence, including live-bank status and a PM MUDRA account-linking demonstration, while account-specific availability still requires lender or UPI-app verification.