






If you are asking how much gold in portfolio exposure is enough, the evidence does not support one percentage for everyone. Figures such as 5%, 10% or 15% can be useful reference points in research or rules of thumb, but they are not automatically the right answer for an individual investor. The more defensible approach is to decide what job gold should perform, examine the assets already around it and then choose a target that fits the portfolio rather than copying a number.
1. Define gold’s job
Decide whether gold is being added mainly for diversification, stress resilience, currency exposure, long-term wealth preservation or another clearly defined portfolio purpose.
2. Measure the portfolio around it
Look at the existing equity, debt, cash and other assets because the same gold percentage can behave differently inside different portfolio mixes.
3. Count existing gold exposure
Inventory financial gold, bars, coins and relevant physical or jewellery holdings before assuming the portfolio starts from zero gold.
4. Check constraints
Consider goal horizon, liquidity needs, tolerance for drawdowns and whether the investor can maintain the target through market cycles.
5. Choose a defensible target or range
Use research as evidence, not as a universal prescription. Avoid false precision when the evidence does not identify one unique optimum.
6. Set the maintenance rule separately
Once the target is chosen, define how portfolio drift will be monitored and rebalanced rather than repeatedly changing the target because gold prices moved.
There is no evidence-backed universal gold percentage
The strongest answer is not “10%” or “15%.” Portfolio research can test how particular gold allocations behaved inside a particular model, but that does not turn the tested range into a personal recommendation.
World Gold Council research published in March 2026 examined a hypothetical Indian portfolio over December 2006 to December 2025. Its starting portfolio was 70% equities and 30% fixed income. The study then replaced equity and fixed-income exposure proportionately with gold and reported improved historical risk-adjusted outcomes and lower drawdowns across the gold allocations it tested, including allocations between 7.5% and 15%.
That result is useful evidence that gold can alter portfolio behaviour. It is not evidence that every Indian investor should hold between 7.5% and 15% gold. The outcome depends on the starting portfolio, the historical period, the assets used, the methodology and assumptions. Future returns and correlations can differ.
What the 7.5%–15% research range actually tells you
The most important lesson from the study is not the percentage itself. It is that the effect of gold was measured inside a specific portfolio.
A 10% gold allocation inside an equity-heavy portfolio is not economically identical to 10% gold inside a portfolio already dominated by fixed income or cash. Gold’s value as a diversifier depends partly on what it is diversifying.
This is why a historical model should be used as evidence about portfolio interaction rather than copied as an allocation instruction.
Start by defining what job gold is supposed to do
Before choosing a target, the investor should be able to explain why gold is being included at all.
If the answer is simply “because gold recently went up,” the target is being driven by performance chasing rather than portfolio design. A stronger reason would be that gold is expected to provide a return pattern that differs from equity and debt, potentially helping diversification or drawdown resilience over some market environments.
SEBI’s investor guidance treats asset allocation as a broader decision shaped by financial goals, investment horizon, risk tolerance and diversification. Those factors should come before a gold percentage, not after it.
Your equity-debt mix changes the gold decision
The amount of portfolio risk already coming from other assets matters.
An investor with a high equity concentration is exposed heavily to equity-market drawdowns. An investor with a much larger debt or cash allocation has a different risk structure. Adding the same percentage of gold to both portfolios does not necessarily produce the same diversification benefit or trade-off.
The useful question is therefore not only “How much gold?” but also “What is gold being added to?”
Count the gold you already own before adding more
Indian households can already have meaningful exposure through jewellery, coins, bars, inherited gold or financial gold products.
That existing exposure should at least be inventoried before setting a new investment target. Otherwise, an investor can think the portfolio has 5% gold while the household’s broader economic exposure is materially higher.
However, jewellery should not automatically be treated as identical to liquid investment gold. Jewellery can include making charges, stones, design value and emotional or cultural use, and the household may have no intention of selling it. The appropriate treatment therefore depends on what the exposure represents and how realistically it could serve the portfolio purpose.
Goal horizon and liquidity come before optimisation
A mathematically attractive allocation is not useful if it conflicts with when the money is needed.
Money required for a near-term goal has a different liquidity and volatility requirement from capital intended for a long investment horizon. Gold can fluctuate materially, so a reader should not choose an exposure level without considering whether the portfolio can tolerate those movements before the relevant goal date.
This is one reason a portfolio target cannot be derived from age or a single risk label alone.
Drawdown tolerance matters — but more gold is not automatically safer
Historical research has shown that adding gold to some diversified portfolios can reduce drawdowns and improve risk-adjusted outcomes. That does not imply that every additional percentage point of gold always reduces risk.
Too much concentration in any one asset can create a different type of portfolio risk. The allocation decision should therefore ask whether the proposed gold exposure improves the portfolio’s overall behaviour rather than assuming that a larger gold allocation is automatically more defensive.
Why age-based formulas are too simple
Rules such as “divide your age by two” can be easy to remember, but the reviewed evidence does not establish them as universal gold-allocation rules.
Two investors of the same age can have completely different goals, income stability, liabilities, existing assets, liquidity needs, pension coverage and tolerance for market losses. Age can be one relevant circumstance, but it cannot replace the broader allocation decision.
A target range can be more honest than a magic number
Portfolio decisions often look precise only because a percentage has been written to one decimal place. The underlying evidence may not justify that level of certainty.
When multiple allocations have historically produced acceptable portfolio outcomes, a target range can reflect uncertainty more honestly than claiming that one exact number is optimal.
The purpose of the range is not to make the decision vague. It is to establish a disciplined boundary that reflects the portfolio’s goals and constraints without pretending the future is known.
| Question | Why it matters before choosing gold exposure |
|---|---|
| What job should gold perform? | Determines whether the allocation is meant for diversification, resilience, currency exposure or another portfolio function. |
| How much equity and debt already exists? | Gold’s diversification effect depends on the risk structure around it. |
| How much gold is already owned? | Physical, jewellery and financial holdings can make actual exposure higher than the investment account suggests. |
| When will the money be needed? | Shorter horizons reduce the ability to tolerate market-price swings. |
| How much drawdown can the investor tolerate? | The target should fit overall portfolio risk rather than use gold as a generic safety label. |
| Can the target be maintained? | A target that is repeatedly changed after price moves becomes performance chasing rather than disciplined allocation. |
Do not raise the target just because gold recently performed well
Recent returns are historical outcomes, not evidence that the same return pattern will continue. Increasing a strategic allocation only after an asset has rallied can turn portfolio construction into return chasing.
A better test is whether the original portfolio purpose or constraints changed. If the goal, horizon, surrounding assets and risk capacity are unchanged, a price rally alone does not prove that the strategic target should be increased.
Choosing the target comes before rebalancing
Allocation and rebalancing are related but different jobs.
This article answers the upstream question: what gold exposure should the portfolio aim for? Rebalancing begins after that decision, when market movements push the actual portfolio away from the chosen target.
TPS separately explains how gold portfolio allocation and rebalancing work in India, including how portfolio drift can be corrected after a target already exists.
A practical framework without a universal recommendation
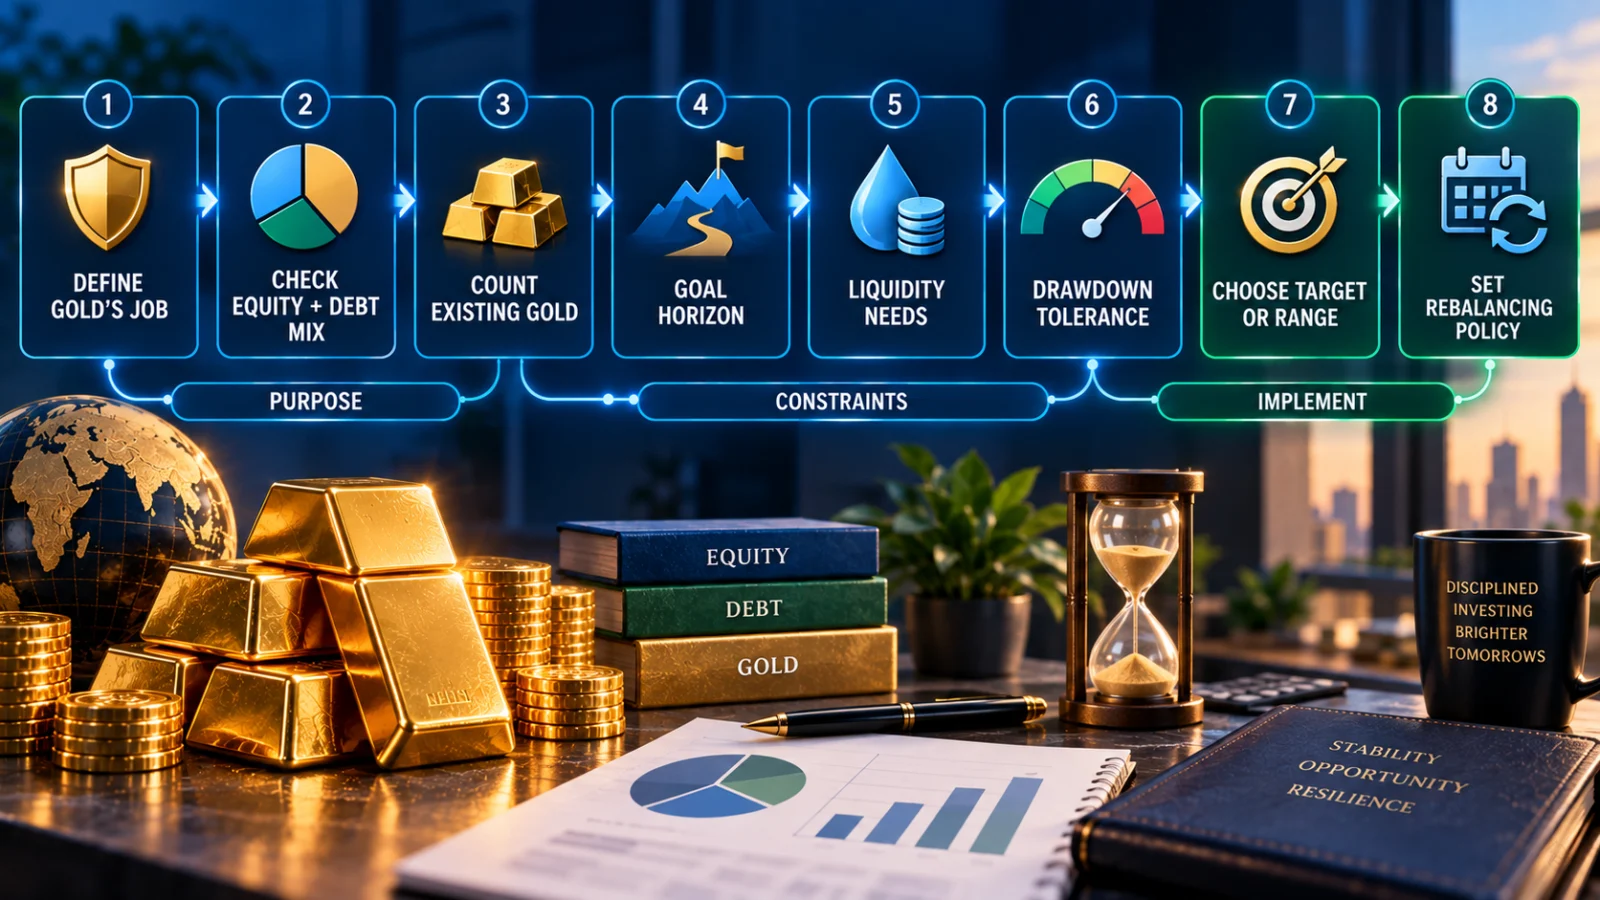
A reader can work through the allocation decision in this order:
- Define the financial role expected from gold.
- Measure the current equity, debt, cash and other asset mix.
- Inventory existing financial and physical gold exposure.
- Check goal horizon and near-term liquidity requirements.
- Assess how much portfolio drawdown can realistically be tolerated.
- Use historical portfolio studies to understand trade-offs rather than copy their tested percentages.
- Select a target or range that fits the portfolio’s purpose and constraints.
- Set a separate rebalancing rule to maintain that target over time.
This process does not produce one universal percentage because the evidence does not support one. It produces a better-defined decision.
Bottom line
How much gold should be in a portfolio cannot be answered responsibly with one percentage for everyone. The WGC India study provides useful evidence about how certain gold allocations behaved in one historical model, but its tested range is not a personal prescription.
The stronger approach is to decide what gold is meant to do, understand the surrounding equity and debt mix, count existing gold exposure, consider horizon and liquidity, assess drawdown tolerance and then choose a target or range that can be maintained consistently.
Verification note
TPS reviewed World Gold Council India portfolio research and SEBI investor guidance on asset allocation, risk, diversification and investment horizon. Current allocation articles were used during R&D to identify recurring percentage rules and reader confusion, not as controlling evidence for a universal allocation.
Limitations and unresolved facts
Future gold returns and correlations are unknown. Historical portfolio optimisation is period- and model-dependent. Individual goals, liabilities, liquidity needs, taxes, existing gold holdings and risk capacity differ, so TPS cannot establish a universally correct or personalised gold percentage. Jewellery and inherited gold can represent economic exposure but may not be equivalent to liquid investment gold.