






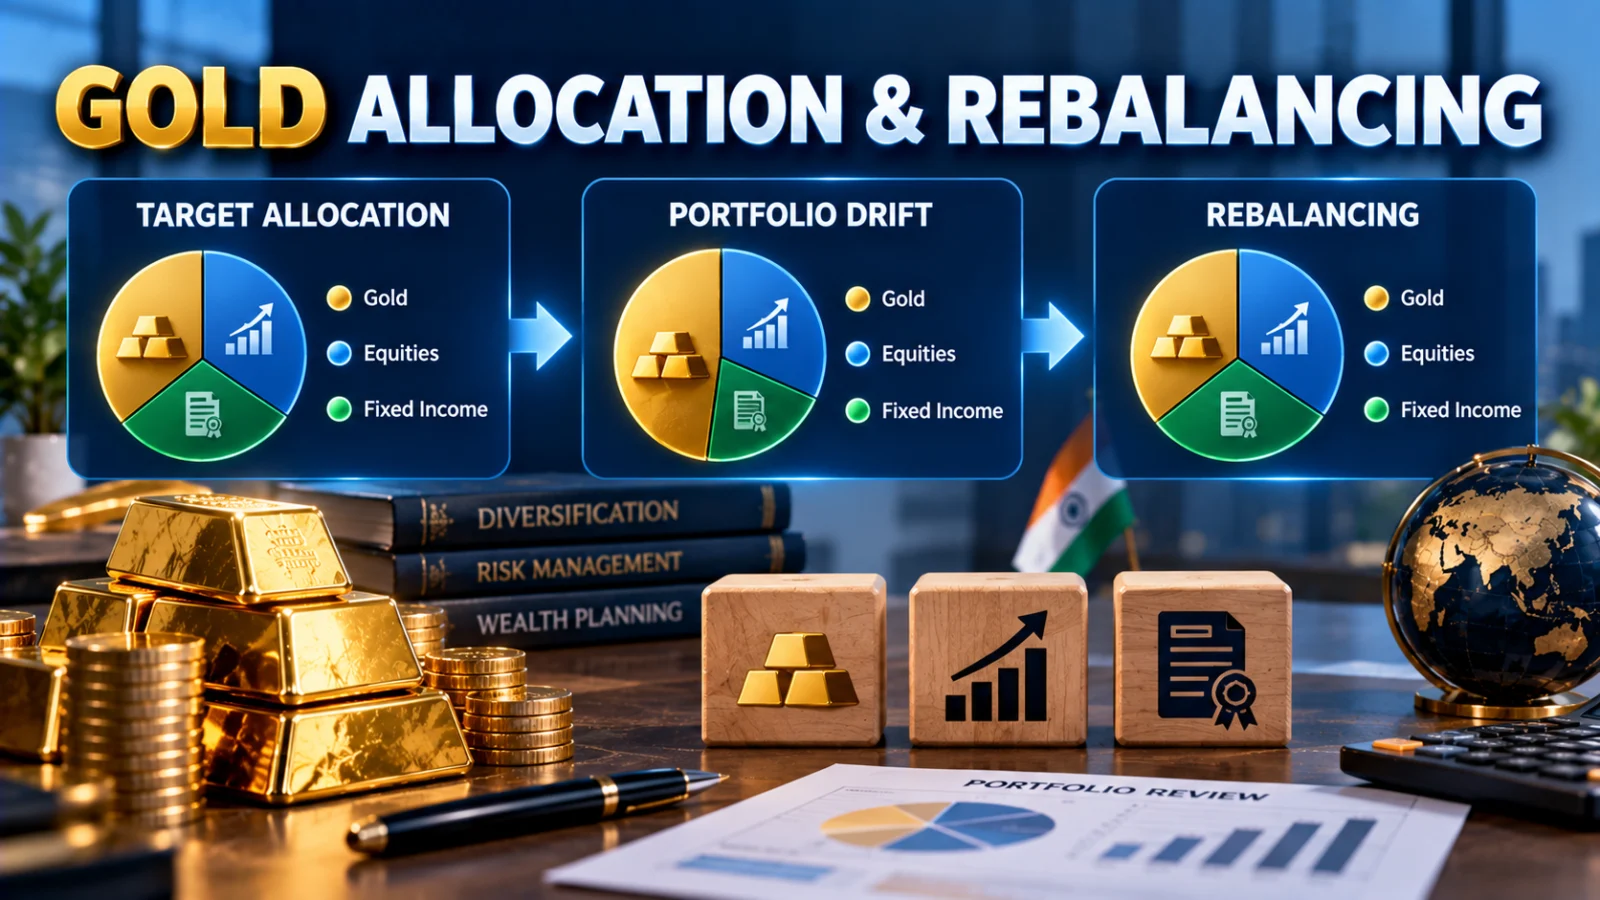
Gold portfolio allocation rebalancing India is best understood as a discipline for maintaining a chosen portfolio mix, not as a method for predicting the next gold rally. The investor starts with a target allocation, allows market prices to move, measures how far the portfolio has drifted, and then restores the intended mix when a review rule says action is needed.
That distinction matters because a gold rally can make an investor feel that the winning asset should be left alone or bought more aggressively. Rebalancing can produce the opposite action: if gold has risen enough to become overweight relative to the investor’s chosen target, the method may call for trimming gold or directing new money toward underweight assets. If gold becomes underweight, the same discipline can work in the other direction.
The method therefore reduces dependence on repeatedly forecasting what gold will do next. It does not remove risk, guarantee better returns or establish one correct gold percentage for every investor.
What does gold allocation actually mean?
A gold allocation is the percentage of an investable portfolio assigned to gold as one asset class. If an investor has a diversified portfolio containing equities, fixed income and gold, the allocation describes how much of the total portfolio value is represented by gold at a particular point in time.
The key word is target. A strategic allocation is not simply the amount of gold the investor happens to own today. It is a portfolio weight chosen as part of a broader risk and diversification plan.
What did the World Gold Council’s India study actually test?
The World Gold Council’s 2026 India analysis tested a hypothetical portfolio in Indian rupees using historical data from December 2006 through December 2025.
The baseline portfolio was 70% equities and 30% fixed income. The equity component used 60% BSE SENSEX TRI and 10% MSCI World Net TRI. The fixed-income allocation was divided among Indian government bonds, corporate bonds and short-duration Indian Treasuries.
Gold was then introduced by reducing the equity and fixed-income allocations at equal weight. WGC compared portfolios containing gold allocations of 7.5%, 10%, 12.5% and 15% with the no-gold baseline.
Across that specific historical simulation, the gold-containing portfolios showed improved risk-adjusted returns and lower drawdowns. That is useful evidence about how gold behaved inside the tested portfolio. It is not evidence that every Indian investor should hold between 7.5% and 15% gold.
Why the 7.5%–15% range is not a recommendation
The study range came from one historical portfolio construction, one set of asset indices and one sample period. Change the starting portfolio, time period, investor objectives, cash-flow needs, costs or future asset correlations and the result can change.
This is also consistent with earlier World Gold Council India research, which used different assumptions and historical periods and produced different portfolio-allocation findings. That is exactly why TPS treats these numbers as historical evidence rather than as a universal allocation rule.
1. Set the target
The investor defines how gold fits within the broader portfolio. The target should come from the investor’s own risk, goals, liquidity needs and overall asset mix, not from copying a historical study percentage.
2. Let markets move
Gold, equities and bonds will not earn identical returns. Their changing market values cause the portfolio weights to drift even when the investor makes no trades.
3. Measure the drift
At a review point, compare the current gold percentage with the chosen target instead of asking only whether gold has recently risen or fallen.
4. Restore the intended mix
An overweight asset can be reduced, an underweight asset can be increased, or new contributions can sometimes be directed toward underweight assets so the portfolio moves back toward its target.
5. Repeat under the same discipline
The method remains focused on portfolio weights rather than repeatedly changing the plan because of headlines, recent returns or predictions about the next gold move.
What is portfolio drift?
Portfolio drift happens when assets perform differently. Suppose an investor starts with a chosen gold target and gold subsequently rises much faster than the rest of the portfolio. Gold’s percentage of the total portfolio can become larger even though the investor has not purchased another gram or fund unit.
For illustration, imagine a ₹10 lakh portfolio with ₹1 lakh in gold. Gold begins at 10% of the portfolio. If gold rises sharply while the other assets move much less, the gold holding can become more than 10% of the new portfolio value. The investor now has a different risk mix from the one originally selected.
The important question is therefore not simply, “Did gold go up?” It is, “How far has the portfolio moved away from its intended allocation?”
Why rebalancing can mean trimming gold after a rally
If a target exists and a rally pushes gold materially above it, restoring the target can require reducing the overweight position. That may mean selling part of the gold exposure, or it may mean directing new contributions toward other assets until the imbalance narrows.
This is not automatically a forecast that gold is about to fall. The action follows the portfolio rule: gold has become a larger share of the investor’s risk than the plan intended.
That distinction helps explain why rebalancing can feel uncomfortable. It sometimes asks the investor to reduce the recent winner rather than chase it.
Why rebalancing can also mean adding gold after underperformance
The same logic works in reverse. If gold falls or other assets rise faster and gold becomes materially underweight, restoring the target can require adding gold exposure.
Again, that does not mean the investor has correctly predicted an imminent rally. The action is based on the target allocation rather than a near-term price forecast.
Does rebalancing always require selling?
No. An investor who is still adding money to the portfolio may be able to direct new contributions toward underweight assets instead of immediately selling an overweight holding.
For example, if gold has become overweight, new money can sometimes be directed toward equities or fixed income. If gold is underweight, new contributions can sometimes be directed toward gold. Whether this is sufficient depends on the size of the drift and the investor’s cash flows.
How often should gold be rebalanced?
There is no single universal frequency established by the WGC 2026 study for every investor. Rebalancing frameworks can be calendar-based, threshold-based or combine both ideas.
A calendar approach checks the portfolio at defined intervals. A threshold approach acts when an asset moves far enough away from its target. The appropriate rule depends on the portfolio, costs, taxes, liquidity and how much drift the investor is prepared to tolerate.
TPS therefore does not present “rebalance every year” or any other interval as a universal evidence-backed rule.
Why rebalancing reduces dependence on market timing
Market timing asks a different question: “What will gold do next?” Rebalancing asks, “Has my portfolio moved too far away from the allocation I chose?”
The second question can be answered from current portfolio weights without predicting the next market move. An investor may still make a poor allocation choice or experience losses, but the decision process is more rule-based and less dependent on reacting to fear, excitement or recent performance.
Does rebalancing guarantee better returns?
No. Historical portfolio simulations show what would have happened under specific assumptions and market conditions. They cannot guarantee future asset returns, future correlations or future drawdowns.
Rebalancing can also cause an investor to reduce an asset that continues rising or add to an asset that continues falling. Its purpose is to maintain the chosen portfolio risk structure, not to maximize every short-term return.
What can change the real-world result?
Historical portfolio studies are cleaner than real implementation. Actual investors can face taxes, transaction charges, bid-ask spreads, product expenses, liquidity differences and cash-flow constraints.
The investment vehicle also matters. Rebalancing a liquid exchange-traded product can be operationally different from dealing with physical gold. This page does not attempt to choose the gold vehicle for the reader; that is a separate investment-product decision.
Should jewellery be counted as portfolio gold?
There is no universal answer established by the evidence reviewed for this article. Jewellery can combine financial, consumption, cultural and sentimental value, and it may carry making charges or resale frictions that differ from investment products.
A reader should therefore not automatically treat every household gold item as interchangeable with a liquid strategic investment allocation without deciding what that holding actually represents in the household’s financial plan.
What the method actually proves — and what it does not
| What the evidence supports | What it does not establish |
|---|---|
| Gold improved risk-adjusted outcomes in WGC’s specific historical Indian portfolio simulation. | That every investor should use the same gold allocation. |
| Different asset returns cause portfolio weights to drift. | That an overweight asset is about to fall. |
| Rebalancing can restore a chosen portfolio mix. | That rebalancing guarantees higher returns. |
| A rule-based allocation process can reduce dependence on short-term forecasts. | That future gold, equity or bond behaviour will match the past. |
A simple way to think about the method
The method can be summarized as:
Choose a target → let markets move → measure drift → rebalance toward the target → repeat.
The discipline is valuable precisely because it does not require a new gold-price prediction every time the market moves. But the target itself still has to be appropriate for the investor, and the real-world cost of implementing the rule still matters.
Verification note
TPS reviewed the World Gold Council’s 2026 India portfolio analysis and its stated historical period, asset mix and tested gold allocations. TPS also reviewed current Indian portfolio-rebalancing material to verify how allocation drift and rebalancing are described in practical investor contexts. Historical study results were kept separate from personalised investment recommendations.
Limitations and unresolved facts
The WGC findings are historical and depend on its specified hypothetical portfolio, indices and Dec 2006–Dec 2025 sample. TPS has not established one correct gold percentage, one correct review frequency or one tax-efficient rebalancing route for every investor. Future asset returns and correlations can differ, and implementation costs, taxes, product structure, liquidity, personal goals and risk tolerance can materially change the outcome.