






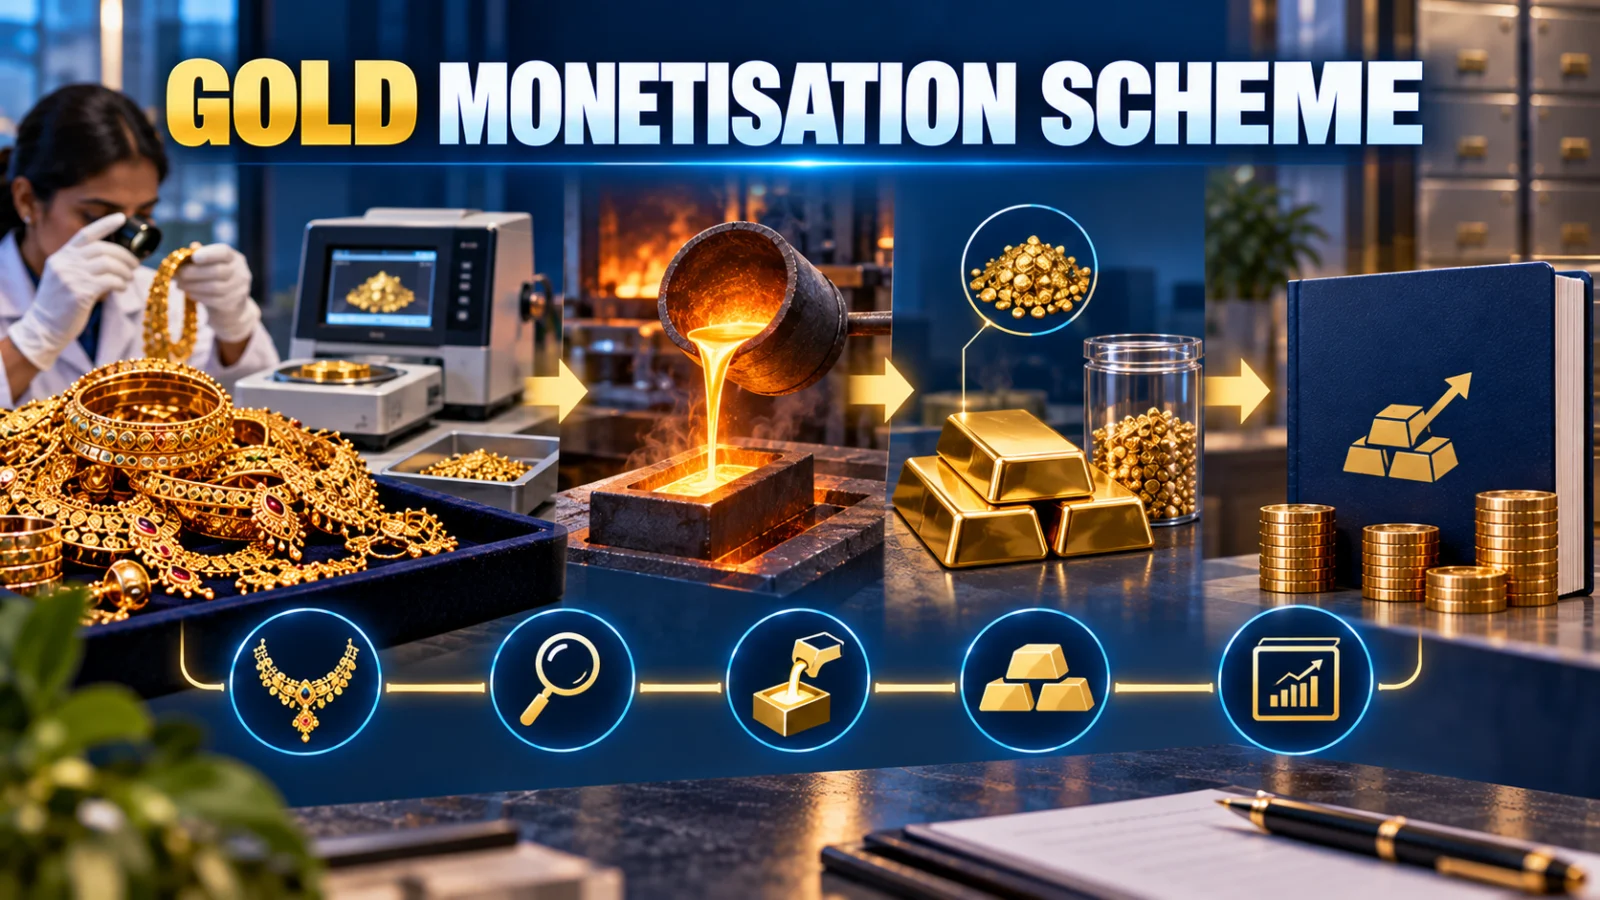
The Gold Monetisation Scheme still provides a possible way to earn interest on eligible idle physical gold in India, but the scheme is not the same as it was before March 2025. New Medium and Long Term Government Deposits stopped accepting fresh mobilisation and renewals from March 26, 2025. The surviving route for a new depositor is a Short Term Bank Deposit, or STBD, where a designated bank chooses to offer it.
The practical point many readers miss is even more important: this is not a scheme where your necklace sits untouched in a bank while earning interest. If you proceed beyond preliminary purity testing and consent to fire assay, the jewellery can be melted. The resulting deposit is recorded as an equivalent quantity of standard gold in grams rather than as custody of the original ornament.
What changed after March 2025?
Short Term Bank Deposit: may still be offered by designated banks for a 1–3 year period, subject to the bank’s own current terms.
Medium Term Government Deposit: no new mobilisation or renewal from March 26, 2025.
Long Term Government Deposit: no new mobilisation or renewal from March 26, 2025.
Existing older MLTGD deposits: they were not cancelled and continue under their applicable existing terms until redemption.
Can you still earn interest on idle gold?
Yes, potentially. A designated bank can still offer an STBD under the Gold Monetisation Scheme. The important word is can: RBI does not require every designated bank to operate the product continuously.
The bank determines the STBD interest rate, lock-in conditions and payment periodicity under the scheme framework. That means there is no single current national STBD interest rate that applies to every bank.
SBI, for example, currently states that it accepts deposits under STBD and publishes separate rates across its 1-to-3-year tenure bands. Those figures are SBI-specific and can change; they should not be treated as universal GMS rates.
What gold can be deposited?
The RBI framework permits eligible raw gold including jewellery, bars and coins, subject to scheme rules. Stones and other non-gold material are excluded when the actual gold quantity is determined.
The current minimum deposit under the scheme is 10 grams of eligible raw gold. There is no scheme-level maximum quantity specified in the same way as the minimum, although banks and operating centres can have practical procedures and documentation requirements.
What actually happens to jewellery under GMS?
This is the most important part of the decision.
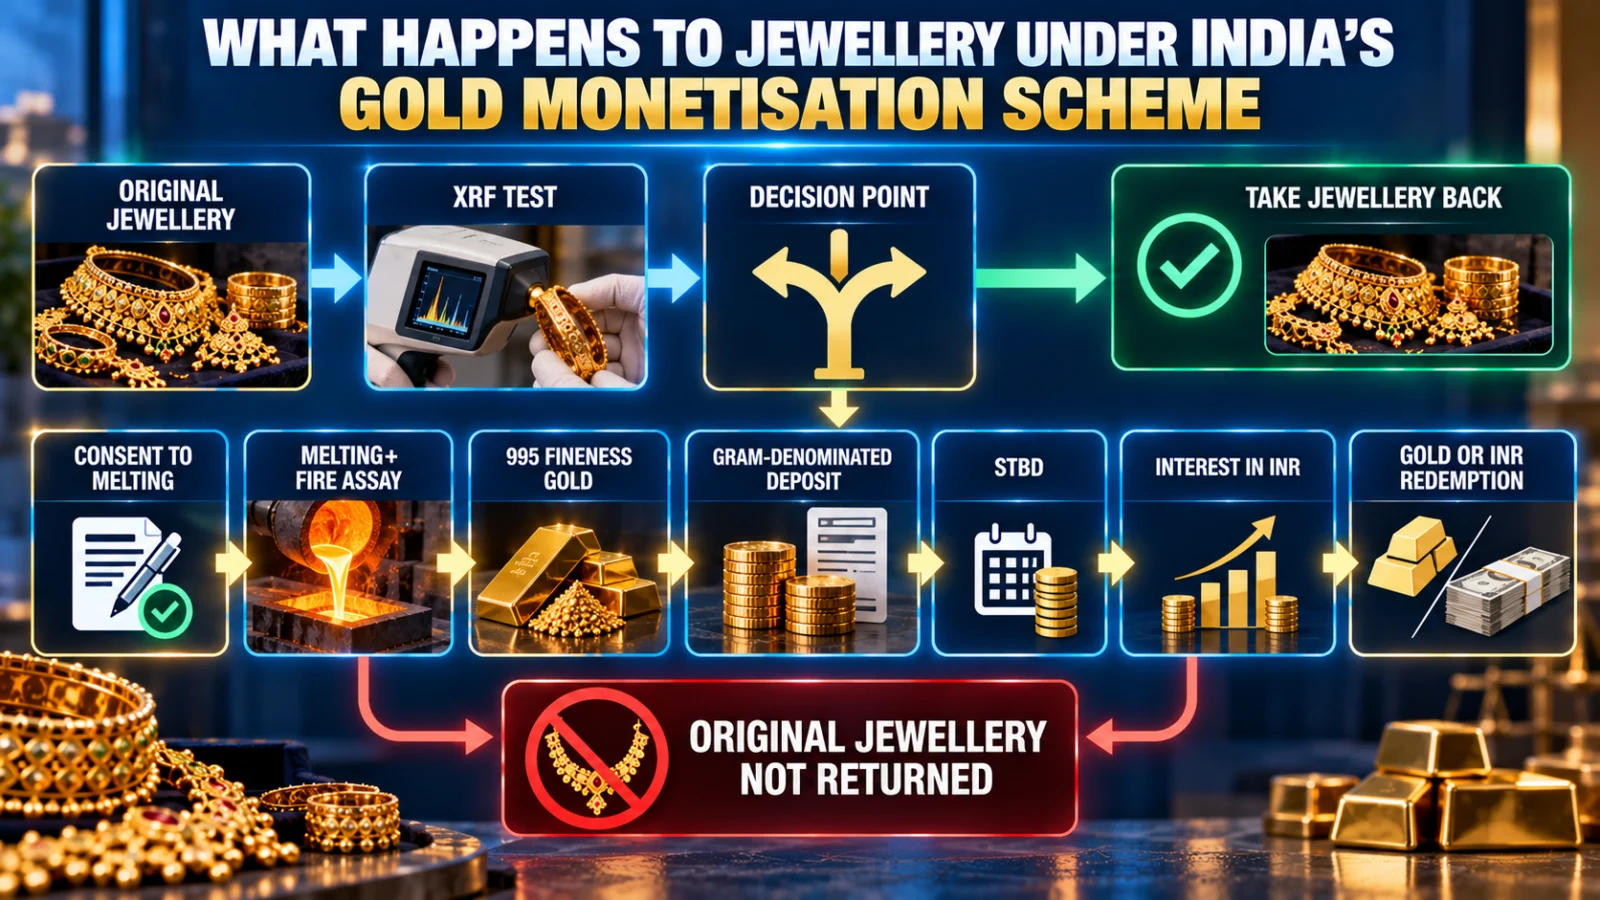
The process begins with weighing and preliminary purity testing, commonly including XRF testing at an authorised Collection and Purity Testing Centre or other permitted facility.
At this preliminary stage, the customer can still decide not to continue and take the original jewellery back.
If the customer accepts the preliminary result and gives consent for fire assay, the jewellery is cleaned and melted. A sample is then tested to establish the final purity.
Once melting has occurred, the original physical form of the jewellery is gone. If the customer disagrees with the final assay and decides not to proceed, RBI’s process provides for return of the gold only in its post-melted form rather than reconstruction of the original ornament.
| Stage | What the customer still owns | Can the original jewellery still be taken back? |
|---|---|---|
| Before testing | Original jewellery | Yes |
| After preliminary XRF testing | Original jewellery | Yes, before consent to melting |
| After consent to melting and fire assay | Melted gold / standardised gold quantity | No, not in the original ornament form |
| After deposit creation | Gold-denominated bank deposit | No original ornament remains in custody |
What does the bank actually credit?
The deposit is not recorded as “one necklace” or “two bangles.” The final purity and quantity are converted into an equivalent amount of standard gold, expressed in grams of 995 fineness.
This means the deposit principal is gold-denominated. The account represents a standard quantity of gold, not the continued ownership of a specific piece of jewellery in its original form.
This distinction also explains why GMS should not be confused with a bank locker. A locker is a custody arrangement in which the physical item remains your item. GMS is a monetisation mechanism in which the physical gold is standardised for deposit.
Is the interest paid in gold?
No. Under the current STBD framework, interest is denominated and paid in Indian rupees.
The principal remains denominated in gold, while the interest calculation follows the participating bank’s applicable STBD terms.
This is why saying “gold itself earns interest” can be misleading. The physical metal has no native yield. The interest exists because the gold has been placed inside a bank deposit structure.
TPS explains that broader distinction separately in Can Gold Generate Monthly Income?. This page focuses specifically on how the Gold Monetisation Scheme creates that interest-bearing wrapper.
What interest rate can you get?
There is no single universal STBD rate under the current GMS structure.
RBI allows designated banks to determine their own STBD rates and related terms. SBI currently publishes the following annual rates on its scheme page:
- 1 year: 0.50%
- Above 1 year up to 2 years: 0.55%
- Above 2 years up to 3 years: 0.60%
Those rates are an example of one bank’s current offering, not a national GMS rate. Another participating bank can offer different terms or choose not to operate STBD at all.
When does interest start?
The exact operational timing should be checked with the bank handling the deposit.
SBI currently states that interest begins from the date the gold is converted into tradable refined bars or 30 days after receipt of the gold, whichever occurs earlier. That is useful current implementation evidence, but it should not be presented as a universal timing rule for every participating bank without checking that bank’s current terms.
Can you get the same jewellery back at maturity?
No. Once the original ornament has been melted and converted into the standardised gold deposit, the scheme does not preserve the necklace, bangle or coin as the identical physical object originally tendered.
At maturity, the principal may be redeemable according to the applicable scheme and bank terms in gold or the rupee equivalent. If gold redemption is chosen, it refers to standard gold under the scheme—not reconstruction of the original jewellery.
This makes sentimental, antique and design value important before the deposit is created. A family heirloom can contain value that is not captured by its metal weight alone.
What happens to existing medium- and long-term GMS deposits?
The March 2025 change did not cancel existing MTGD or LTGD deposits.
Deposits already made before the discontinuation continue under their applicable existing terms until redemption. The change affects new mobilisation and renewal under those components from March 26, 2025 onward.
A reader holding an older government deposit should therefore not assume that the account disappeared merely because new deposits stopped.
Is GMS the same as a bank locker with interest?
No.
A bank locker is designed for physical custody. The jewellery remains identifiable as the same physical object unless something outside normal custody occurs.
GMS is designed to monetise gold. Once the depositor proceeds through the melting and assay stage, the important asset becomes the measured standard-gold quantity credited to the deposit.
That difference is central to deciding whether the scheme makes sense for a particular item.
Who should think carefully before depositing jewellery?
A depositor should be especially cautious if the item’s value depends heavily on anything beyond raw gold content.
That can include:
- heirloom or family significance;
- antique or collectible value;
- craftsmanship or design value;
- stones or non-gold components;
- emotional importance;
- a desire to receive the identical jewellery back later.
The scheme can monetise the gold content, but it is not designed to preserve these non-metal characteristics.
Bank availability
Confirm that the bank is currently accepting new STBD deposits rather than relying on an old GMS page.
Current interest rate
Check the bank’s current rate for the exact STBD tenure you are considering.
Testing location
Confirm the authorised branch, CPTC or other approved collection route and the expected processing steps.
Melting consent
Understand that you can walk away before consenting to fire assay, but the original ornament form is lost after melting.
Deposit quantity
Verify the final 995-fineness equivalent grams credited after assay.
Redemption terms
Check the bank’s lock-in, premature-redemption conditions and whether your chosen maturity redemption is in gold or INR.
Bottom line
Yes, idle physical gold can still potentially earn interest under the Gold Monetisation Scheme, but the surviving new-deposit route is STBD and availability depends on the bank.
The more important decision is what happens to the gold itself. Jewellery deposited under GMS is not simply kept intact in a vault. Once the customer consents to melting and fire assay, the original ornament is transformed into a standardised gold quantity and the deposit is recorded in grams of 995-fineness gold.
Before comparing interest rates, decide whether you are genuinely willing to give up the original physical form of the jewellery. Then verify the participating bank’s current STBD availability, rate, tenure, testing process and redemption rules.