






A gold SIP can be useful for a salaried person who wants to invest a fixed amount in gold at regular intervals without trying to predict one perfect entry price. But the word SIP describes the investing method, not a guarantee of better returns — and not every product marketed as a “gold SIP” has the same regulatory structure.
The simplest answer is: monthly investing can improve discipline and spread your purchases across different gold prices, but it does not guarantee a profit, remove gold-price risk or automatically beat a lump-sum investment.
There is a second question that matters just as much: what product are you actually buying each month? A recurring investment through a SEBI-regulated mutual-fund or Gold ETF-related route is not the same thing as a platform selling recurring purchases of digital gold.
If your problem is inconsistent investing or anxiety about choosing one entry price, periodic investing can create discipline and spread purchases over time.
Check whether you are buying units of a SEBI-regulated mutual-fund or Gold ETF-related product, exchange-traded gold exposure, or a separately marketed digital-gold product.
Compare the scheme’s expenses, trading or demat costs where relevant, liquidity and how units are bought and redeemed.
SIP changes the timing of purchases. It does not make gold prices predictable and does not guarantee a positive return.
What does a Gold SIP actually mean?
SIP stands for Systematic Investment Plan. In a mutual-fund context, it means investing a predetermined amount at regular intervals rather than investing the entire amount at once.
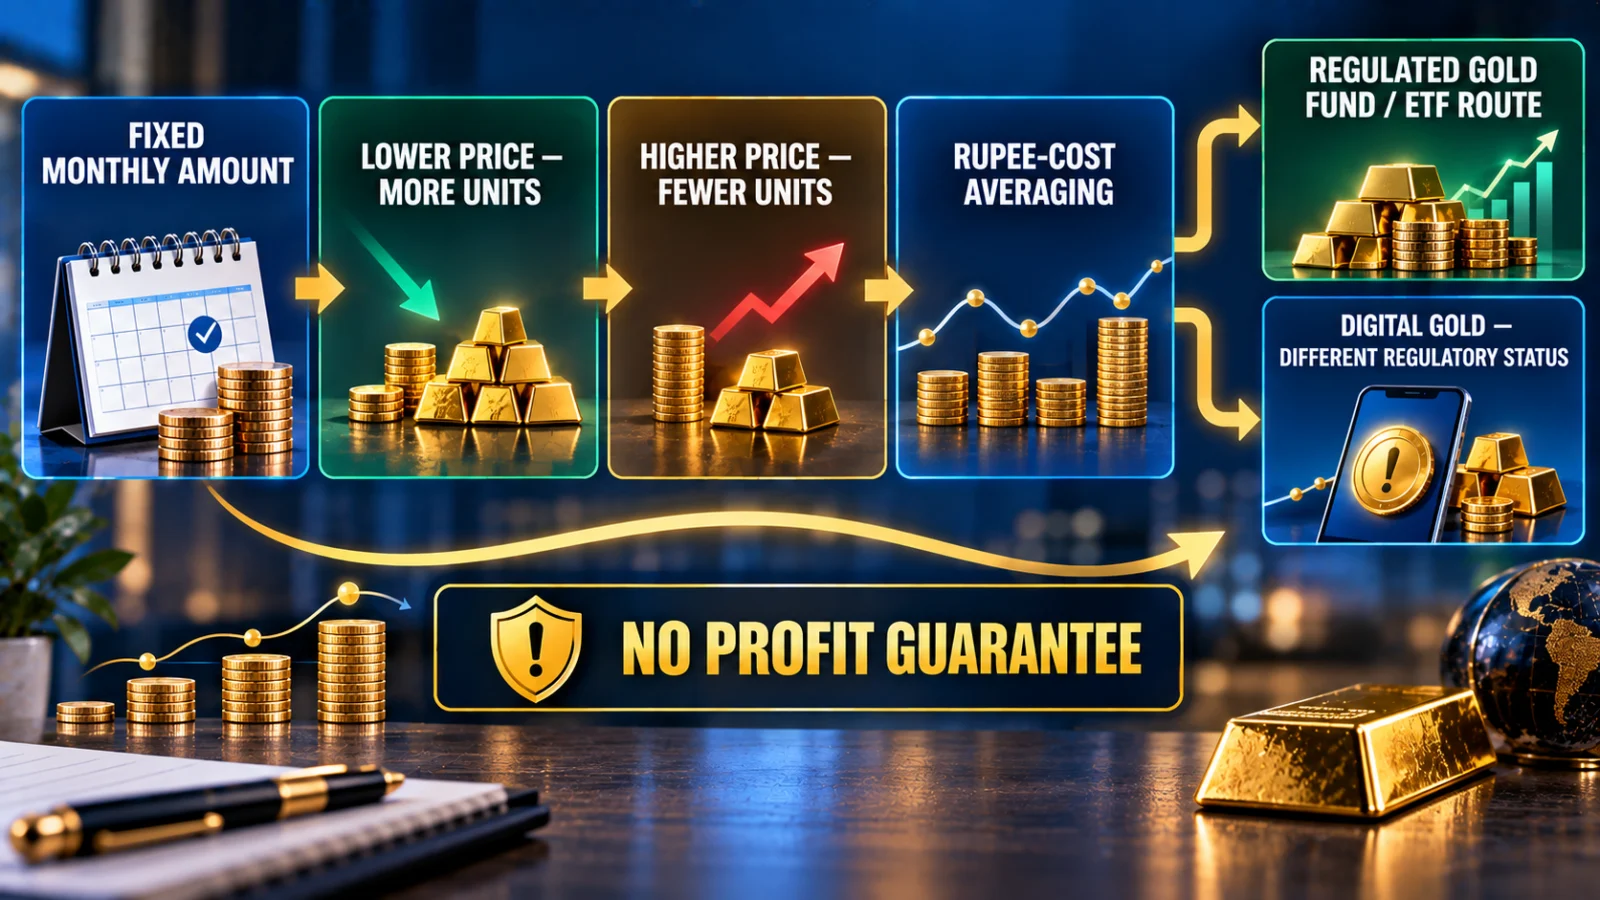
SEBI’s investor-education material explains the rupee-cost-averaging mechanism: when the unit price is lower, the fixed investment amount buys more units; when the unit price is higher, it buys fewer units. Over multiple purchase dates, the investor is therefore not dependent on one single market entry price.
For a salaried investor, the practical attraction is straightforward. Income normally arrives monthly, so a fixed recurring investment can align investing with cash flow and reduce the temptation to keep postponing the decision while waiting for the “right” gold price.
Does monthly investing in gold actually work?
It can work for the specific jobs that SIP is designed to solve: discipline, regular investing and reduced dependence on selecting one entry point.
That is different from saying that SIP guarantees a superior investment result.
If gold falls after several monthly purchases, the investment can still lose value. If gold rises sharply soon after a lump-sum investor buys, that lump-sum investor may outperform someone who is still spreading purchases over future months. The reverse can happen when a large lump sum is invested immediately before a price decline.
Therefore, the honest conclusion is not “SIP always wins.” It is: SIP changes the path by which you build the position.
How rupee-cost averaging works
Imagine that you invest the same amount every month. You do not need to forecast the exact gold price in advance.
- When the unit price is lower, the same rupee amount purchases more units.
- When the unit price is higher, the same rupee amount purchases fewer units.
- Across many purchases, your acquisition cost reflects several different market levels instead of one date.
This is the core rupee-cost-averaging effect described in SEBI investor education.
It should not be confused with a loss-prevention mechanism. Averaging purchase prices cannot stop the market value of the accumulated units from falling.
Does Gold SIP guarantee profit?
No. SEBI’s SIP calculator itself warns that its calculations are illustrations and do not represent actual returns. Market returns are not fixed and cannot be predicted.
The same principle applies when the underlying asset is gold. A regular contribution schedule cannot transform a market-linked investment into a guaranteed-return product.
A reader should therefore treat projected SIP calculators as illustrations of possible compounding or contribution patterns, not promises of what the investment will become.
Is Gold SIP always better than lump sum?
No universal rule says SIP will always outperform lump sum. The result depends on the sequence of gold prices after the investment begins.
| Situation | What periodic investing changes | What it does not guarantee |
|---|---|---|
| You have monthly salary cash flow | Lets you invest gradually as money becomes available | A higher return than investing earlier |
| You worry about buying at one high price | Spreads purchases across multiple prices | Protection from a prolonged gold-price decline |
| You already have a large investible amount | Can intentionally phase entry over time | That phasing will beat an immediate lump sum |
| You struggle to invest consistently | Automation can improve discipline | That gold itself is suitable for your financial goal |
The bigger question: what are you buying through the SIP?
This is where the phrase “Gold SIP” can become misleading. SIP is a payment and investment schedule. It does not identify the regulatory or ownership structure of the underlying gold product.
SEBI has specifically distinguished SEBI-regulated gold products from digital-gold products offered by online platforms.
Route 1: Gold ETF
A Gold Exchange Traded Fund is a SEBI-regulated mutual-fund product whose underlying exposure is gold or permitted gold-related instruments. ETF units trade on a stock exchange.
SEBI’s investor material explains that ETFs trade like shares on an exchange, while AMFI describes Gold ETFs as schemes with gold as the underlying asset. Because ETF units are exchange traded, investors should also consider brokerage, demat-related costs where applicable, liquidity and the possibility that traded prices can differ from NAV.
A person who buys Gold ETF units periodically is following a systematic buying strategy, even though the operational process is not necessarily the same as registering a conventional mutual-fund SIP mandate.
Route 2: Gold Fund of Fund or Gold ETF Fund of Fund
A Gold Fund of Fund is a mutual-fund scheme that invests in an underlying Gold ETF rather than requiring the investor to buy the ETF units directly on the exchange.
Scheme documents available through AMFI show that Gold ETF Fund of Fund products can offer a Systematic Investment Plan route for small and regular investments. A demat account is generally not mandatory for conventional mutual-fund units outside ETFs, although scheme-specific operating rules should always be checked.
The trade-off is that a Fund of Fund can have its own expenses in addition to the expenses embedded in the underlying fund. AMFI’s investor material notes that FoFs involve two levels of expenses, subject to regulatory limits.
Route 3: Recurring digital gold purchases
This requires a separate regulatory warning.
In November 2025, SEBI cautioned the public about online platforms offering “Digital Gold/E-Gold” products. SEBI said these products are different from SEBI-regulated gold products because they are neither notified as securities nor regulated as commodity derivatives under SEBI’s framework.
SEBI also said such products may expose investors to counterparty and operational risks and that securities-market investor-protection mechanisms are not available for these digital-gold investments.
Therefore, a platform’s use of the words “Gold SIP”, “daily gold SIP” or “monthly digital gold” should not be read as proof that the product is a SEBI-regulated mutual-fund SIP.
Gold ETF or Gold Fund of Fund: which route suits monthly investing better?
The answer depends on how you want to invest.
| Factor | Direct Gold ETF | Gold ETF Fund of Fund |
|---|---|---|
| How you transact | Units trade on a stock exchange | Units are bought or redeemed through the mutual-fund route |
| Demat/trading setup | Exchange-traded ETF units are held in demat form | Demat is generally optional for non-ETF mutual-fund units, subject to scheme rules |
| Regular investing | You can build exposure through periodic purchases | Gold FoF schemes can provide a conventional SIP facility |
| Costs to inspect | Expense ratio plus relevant brokerage/demat costs | FoF expenses plus underlying-fund expenses within regulatory limits |
| Pricing | Exchange-traded market price can differ from NAV | Transactions follow the mutual-fund NAV framework |
This comparison is about operating structure, not a recommendation that one route is universally superior.
What monthly investing does not solve
A Gold SIP does not answer every investment question. Before starting one, separate the following issues:
- Asset suitability: SIP does not tell you whether gold is appropriate for your goal or portfolio.
- Allocation: investing monthly does not determine how much of your savings should be in gold.
- Price risk: gold can fall after you invest.
- Product risk: different gold products have different regulatory, liquidity, cost and counterparty structures.
- Return uncertainty: neither SIP nor gold guarantees a particular return.
- Costs: recurring small transactions can still involve scheme expenses, brokerage or other route-specific costs.
When can a Gold SIP make practical sense for a salaried person?
Periodic gold investing can be a practical structure when all of the following are true:
A monthly schedule matches the way salary income becomes available.
Automation reduces the need to make a fresh timing decision every month.
You are not treating rupee-cost averaging as a guarantee against loss.
You know whether you are using a regulated mutual-fund/ETF structure or a different digital-gold arrangement.
When should you not start merely because it is called a SIP?
Do not use the word SIP as a substitute for product due diligence.
A recurring debit can make almost any purchase feel systematic. What matters is what happens after the money is debited: what asset or unit you receive, who regulates the product, how it is valued, how you exit, what expenses apply and what protections are available.
This is especially important for digital gold because SEBI has explicitly said those products operate outside its securities-market regulatory framework.
A practical Gold SIP checklist
Before setting up a monthly gold investment, answer these questions:
- What exact product will my money buy?
- Is it a SEBI-regulated mutual-fund or exchange-traded gold product?
- If it is marketed as digital gold, what regulatory framework and investor protections actually apply?
- Does the route require a demat or trading account?
- What scheme expenses, brokerage, demat or other charges may apply?
- How easily can I stop the recurring investment or redeem/sell the units?
- Am I choosing SIP for discipline and cash-flow matching rather than because I believe it guarantees better returns?
- Does gold itself fit the purpose for which I am saving?
So, does Gold SIP work?
Yes — if “work” means helping you invest a fixed amount regularly, reducing dependence on one entry price and creating disciplined exposure to gold.
No — if “work” means guaranteeing profit, eliminating price risk or always beating a lump-sum investment.
For an Indian salaried investor, the most important decision is therefore not simply SIP versus lump sum. It is a two-part decision: do you want to spread purchases over time, and which underlying gold product are you comfortable owning?
SEBI-regulated Gold ETFs and mutual-fund Gold ETF Fund of Fund routes operate inside the securities-market framework. Digital gold products marketed by online platforms are a separate category, and SEBI has cautioned that they sit outside its securities-market regulatory framework.
Verification note
TPS reviewed SEBI investor-education material on SIP and rupee-cost averaging, SEBI’s SIP calculator disclaimer, SEBI guidance on ETFs, SEBI’s November 2025 digital-gold caution, and AMFI material describing Gold ETFs and Gold ETF Fund of Fund structures. The evidence supports periodic investing as a discipline and averaging mechanism, not as a guaranteed-return strategy or a universal winner over lump sum.