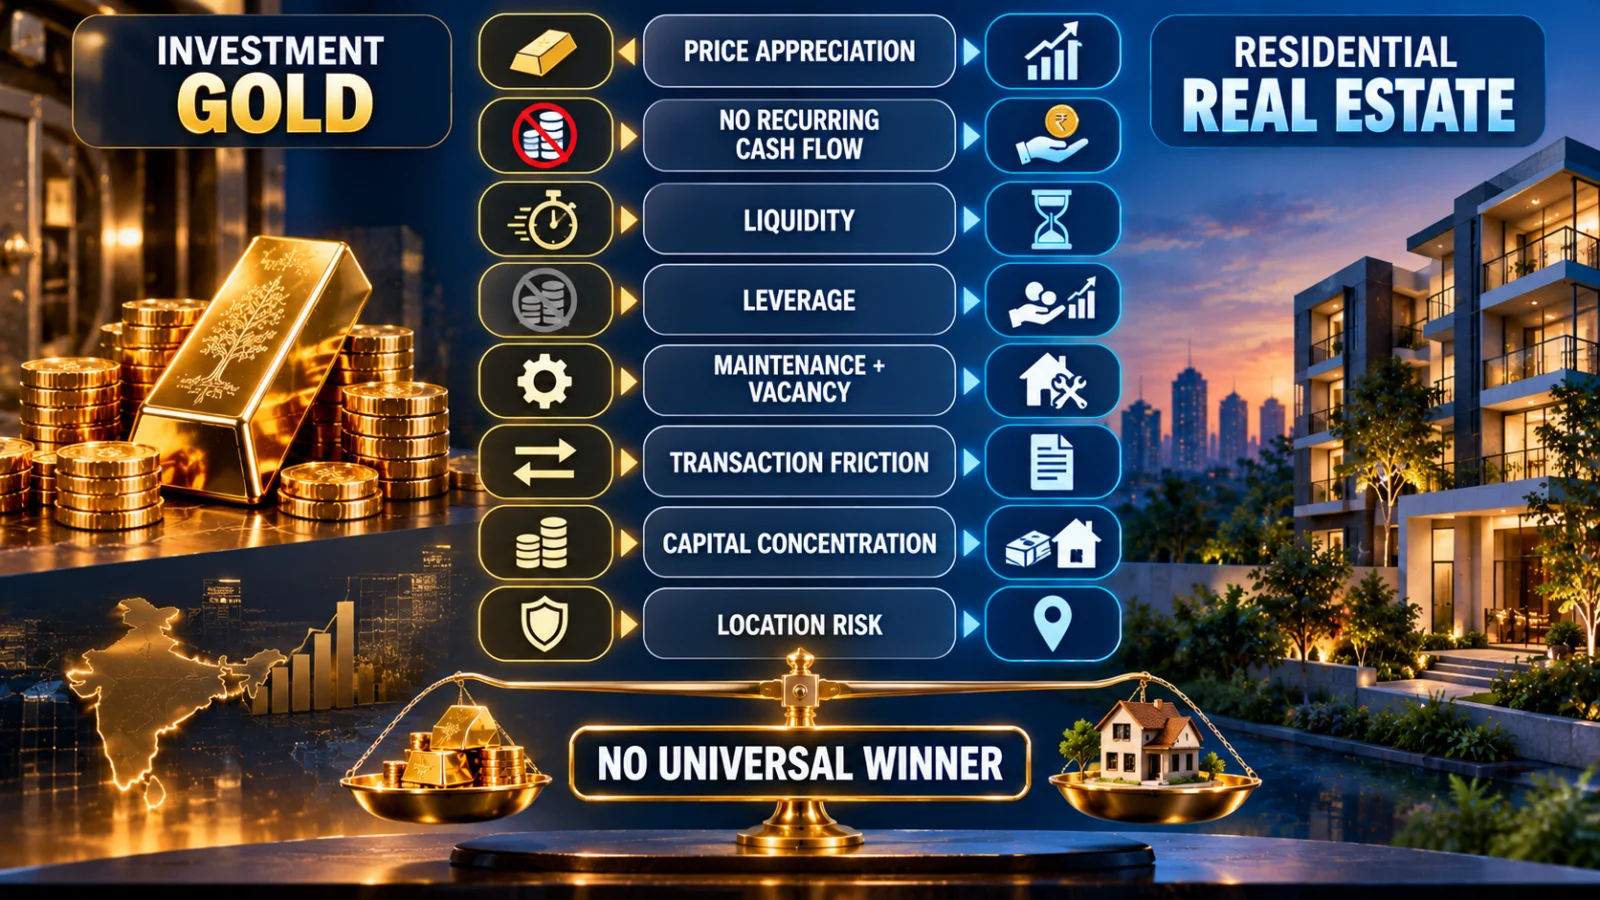
Gold vs real estate India comparisons are often reduced to one question: which asset gave the higher return? That is too simple. Investment gold and directly owned property build wealth through different mechanisms. Gold is highly liquid and divisible but does not generate rent, interest or dividends. Property can produce rental income and can be bought with leverage, but it also brings location concentration, financing costs, maintenance, vacancy risk and much more friction when buying or selling.
There is therefore no evidence-backed universal winner. A useful comparison must look beyond historical price appreciation and ask what financial job the asset needs to perform.
| Dimension | Investment gold | Direct investment property |
|---|---|---|
| Primary return engine | Market-price movement | Property-price movement plus possible rental income |
| Native recurring cash flow | No | Possible through rent, but not guaranteed |
| Liquidity | High at the asset-market level; holding form matters | Low and transaction-dependent |
| Partial sale | Generally practical | Usually difficult |
| Entry capital | Highly divisible | Large and concentrated |
| Leverage | Not normally central to ordinary ownership | Common through property finance |
| Ongoing operational burden | Usually low; storage or custody may apply | Maintenance, vacancy, tenant and documentation issues may apply |
| Location dependence | Global gold price plus rupee movement and holding form | City, micro-market, project, property and local demand |
| Portability | High | Immovable |
| Transaction friction | Vehicle-dependent | Typically high because of documentation, registration, brokerage and sale execution |
The two assets generate wealth differently
Gold itself does not produce recurring cash flow. Its investment value changes mainly when the market price of gold changes. An investor eventually realises that value by selling, redeeming or otherwise exiting the holding.
Direct property has two potential return sources. The property itself may appreciate, and a rented property may generate cash flow while it is held. That makes property structurally different from gold before any historical return numbers are compared.
But rent should not be treated as guaranteed profit. Vacancy, repairs, maintenance, local charges, tenant issues and taxes can reduce the amount that actually reaches the owner.
Why one Indian property return can be misleading
Real estate is unusually difficult to represent with one national return because the asset is local by nature.
National Housing Bank RESIDEX data for the third quarter of FY2025-26 illustrates the dispersion. The 50-city composite housing-price index rose 5.0% year on year, but individual city movements ranged from a 22.8% increase in Gurugram to an 8.9% decline in Raipur.
That does not tell a reader what a specific Gurugram apartment, Bengaluru plot or Mumbai flat will return. It shows why a statement such as “Indian real estate returns X%” can hide materially different local outcomes.
Property results can vary further by neighbourhood, project quality, age of the building, title quality, supply, infrastructure, tenant demand and the price paid at entry.
Gold is far easier to divide and exit
World Gold Council research describes gold as a highly liquid asset in deep global markets. For an individual investor, practical liquidity still depends on the form held: an exchange-traded gold product is different from jewellery, and a bullion bar may have different sale friction from a financial product.
Even with that qualification, gold is structurally easier to divide than direct property. A reader can generally buy or sell a relatively small portion of a gold holding. Selling 8% of an apartment is not normally a practical option.
This matters for portfolio rebalancing, emergency liquidity and gradual withdrawals.
Property can use leverage — and that changes the comparison
One of the largest differences is leverage. A buyer may purchase a property using a combination of personal capital and borrowed money. That allows the buyer to control a larger asset with less initial equity.
But leverage is not a free return multiplier. Interest, fees and repayment obligations become part of the economics. If the property rises in value, leverage can increase the return on the owner’s initial equity. If the property performs poorly, remains vacant or must be sold under pressure, the same leverage can amplify financial stress.
This is why a leveraged property owner’s equity return cannot be compared casually with an unleveraged gold return. The financing assumption has to be shown.
Rental income is useful, but gross rent is not net return
Rental cash flow is one of property’s clearest structural advantages over gold. Investment gold has no tenant and generates no rent.
However, the correct comparison is not “property earns rent, gold earns nothing.” The relevant figure is what remains after vacancy, repairs, maintenance, society or local charges, taxes and other property-specific expenses.
A property with a headline rent can therefore produce a much smaller net cash yield than the gross rent suggests.
Capital concentration is very different
Direct property is usually a large, indivisible commitment. For many households, one property can represent a substantial share of total net worth.
That means the investor can become concentrated not only in real estate but in one city, one neighbourhood, one building and sometimes one tenant market.
Gold exposure can usually be accumulated in smaller increments and spread across time without committing a large amount to one physical location.
This does not make gold automatically safer or better. It means the concentration problem is structurally different.
Property has a much larger operating layer
A direct property investment can require legal-document verification, registration, maintenance, repairs, association or society interaction, tenant management and eventual sale execution.
Gold normally has a smaller operating burden. Physical gold can still require secure custody, insurance or safe storage, and jewellery can carry making-charge and resale frictions. Financial gold products have their own costs.
The key distinction is that property ownership often behaves partly like operating a small asset business, while passive gold ownership generally does not.
Transaction friction matters before the return calculation
Property transactions can involve stamp duty, registration, brokerage, legal verification and substantial time. Exact costs differ by state, transaction and property type, so TPS cannot apply one universal percentage.
The same principle applies to gold: transaction cost depends on whether the reader owns jewellery, bullion, an ETF, a fund or another form.
A fair comparison therefore uses net economic outcome rather than only purchase price versus sale price.
Tax does not create a universal winner
Indian tax treatment depends on the asset, acquisition date, holding period, disposal route and taxpayer facts.
Property can create both rental-income tax considerations and capital-gains consequences. Current law also contains specific treatment for qualifying land or buildings acquired before 23 July 2024 by resident individuals or Hindu Undivided Families, so older property cannot always be analysed using a single headline capital-gains rate.
Gold taxation also varies by ownership vehicle and holding period. Physical gold, exchange-traded products and fund structures should not be assumed to have identical treatment.
For this reason, “gold is more tax efficient” or “property is more tax efficient” is not a defensible universal conclusion.
A self-occupied home is not a clean investment comparison
A home used by the owner provides housing utility as well as financial exposure. The household receives a place to live and may avoid paying rent elsewhere. Those benefits make the decision different from buying an investment property solely to earn rent or appreciation.
This article therefore uses directly owned investment property as the cleanest comparison. Land, commercial property and listed REITs have different economics and should not be silently treated as the same asset.
When gold may fit the job better
Gold may be structurally better aligned when the reader values liquidity, portability, smaller investment increments, easy partial sale and low operational involvement.
That is a suitability statement, not a return forecast. A liquid asset can still fall in price, and gold’s lack of recurring cash flow may make it unsuitable for a goal that requires dependable income.
When direct property may fit the job better
Direct property may be better aligned when the reader can commit substantial concentrated capital, tolerate illiquidity and ongoing management, potentially use debt responsibly, and values rental cash flow or the utility of owning a physical property.
Again, this does not guarantee a higher return. The actual result depends heavily on purchase price, financing, rent, costs, location and exit conditions.
Do not choose the winner from one historical CAGR
Historical comparisons are sensitive to the starting date, ending date and property market selected. A gold rally can make gold appear dominant over one window. A strong property cycle in a particular city can make property appear dominant over another.
The comparison becomes more meaningful only after asking whether the figures include rent, leverage, interest, maintenance, vacancy, transaction costs and tax.
A reader should also avoid comparing one local property index with a national or global gold price and treating the result as universally representative.
A better decision framework
Need liquidity or partial access?
Gold is structurally easier to divide and sell in smaller amounts.
Need recurring cash flow?
Property may provide rent; gold itself does not generate recurring income.
Planning to borrow?
Property can use leverage, but interest and repayment risk must be included.
Concerned about concentration?
One property can concentrate capital in a single location and asset.
Want minimal operational work?
Gold usually requires less ongoing management than direct property.
Choosing on expected return?
Do not rely on one historical CAGR or one city cycle as a future forecast.
The useful question is therefore not simply “Which asset returned more?” It is “Which return engine, liquidity profile, cash-flow structure, concentration level and operating burden fits the job this capital needs to perform?”
TPS has separately compared gold versus equity for long-term wealth in India. Equity ownership has a different return engine from direct property, so that comparison should not be merged with this one.
Bottom line
There is no universal winner in gold vs real estate India comparisons. Gold is more liquid, divisible and portable, but it produces no native recurring income. Direct property can add rent and leverage, but it also introduces large capital concentration, location dependence, financing costs, maintenance, vacancy and substantial transaction friction.
For long-term wealth, compare the assets by the jobs they perform and by net outcomes after financing, operating costs and tax—not by whichever historical CAGR looks highest.
Verification note
TPS reviewed World Gold Council strategic-asset research for gold’s liquidity and lack of recurring cash flow, National Housing Bank RESIDEX data for current Indian residential property-price dispersion, current Income Tax Department material for property income and capital-gains context, and RBI housing-finance material for the leverage dimension.
Limitations and unresolved facts
Future gold and property returns are unknown. Property outcomes are highly dependent on city, micro-market, property quality, financing, vacancy, maintenance and exit conditions. Mortgage rates and tax rules can change. Gold costs and tax treatment vary by holding form. This comparison does not establish the correct asset allocation or investment choice for any individual reader.