






The rupee affects gold prices in India because international gold is largely benchmarked in US dollars, while Indian buyers ultimately see prices in rupees. This page specifically owns the USD/INR transmission into Indian gold prices: how a stronger or weaker rupee changes the domestic translation of an international gold-price move.
If the rupee weakens against the US dollar, more rupees are required to buy the same dollar-priced amount of gold. If the rupee strengthens, fewer rupees are required. This means USD/INR can amplify, cushion or partly offset an international gold-price movement before other Indian pricing factors are added.
How USD/INR transmits global gold prices into India
A simplified way to understand the mechanism is to begin with an international gold value quoted in US dollars. Indian buyers do not settle that value in dollars; it must be translated into rupees. The USD/INR exchange rate therefore becomes one of the bridges between the international benchmark and the domestic Indian price.
If one US dollar becomes more expensive in rupee terms, converting the same dollar gold value produces a higher rupee amount. If the rupee strengthens and one dollar costs fewer rupees, the translated rupee value becomes lower than it otherwise would have been.
This transmission mechanism is the central reader job of this article. It should not be confused with the separate question of why the international gold price itself rises or falls.
What happens when the rupee weakens?
A weaker rupee means USD/INR has risen: each dollar costs more rupees. All else being equal, that increases the rupee value of dollar-priced gold.
World Gold Council research on India during 2026 showed periods in which rupee depreciation helped support domestic gold prices even when international gold performance was weaker. This demonstrates why Indian gold does not necessarily fall by the same percentage as international gold.
What happens when the rupee strengthens?
A stronger rupee produces the opposite translation effect. When fewer rupees are required for each dollar, currency appreciation can reduce part of the domestic impact of an international gold-price increase.
The World Gold Council’s August 2026 India update provides a direct example. International gold rose strongly during the first half of August, while domestic gold rose by a smaller percentage. WGC identified rupee appreciation as one factor that partly offset the international increase.
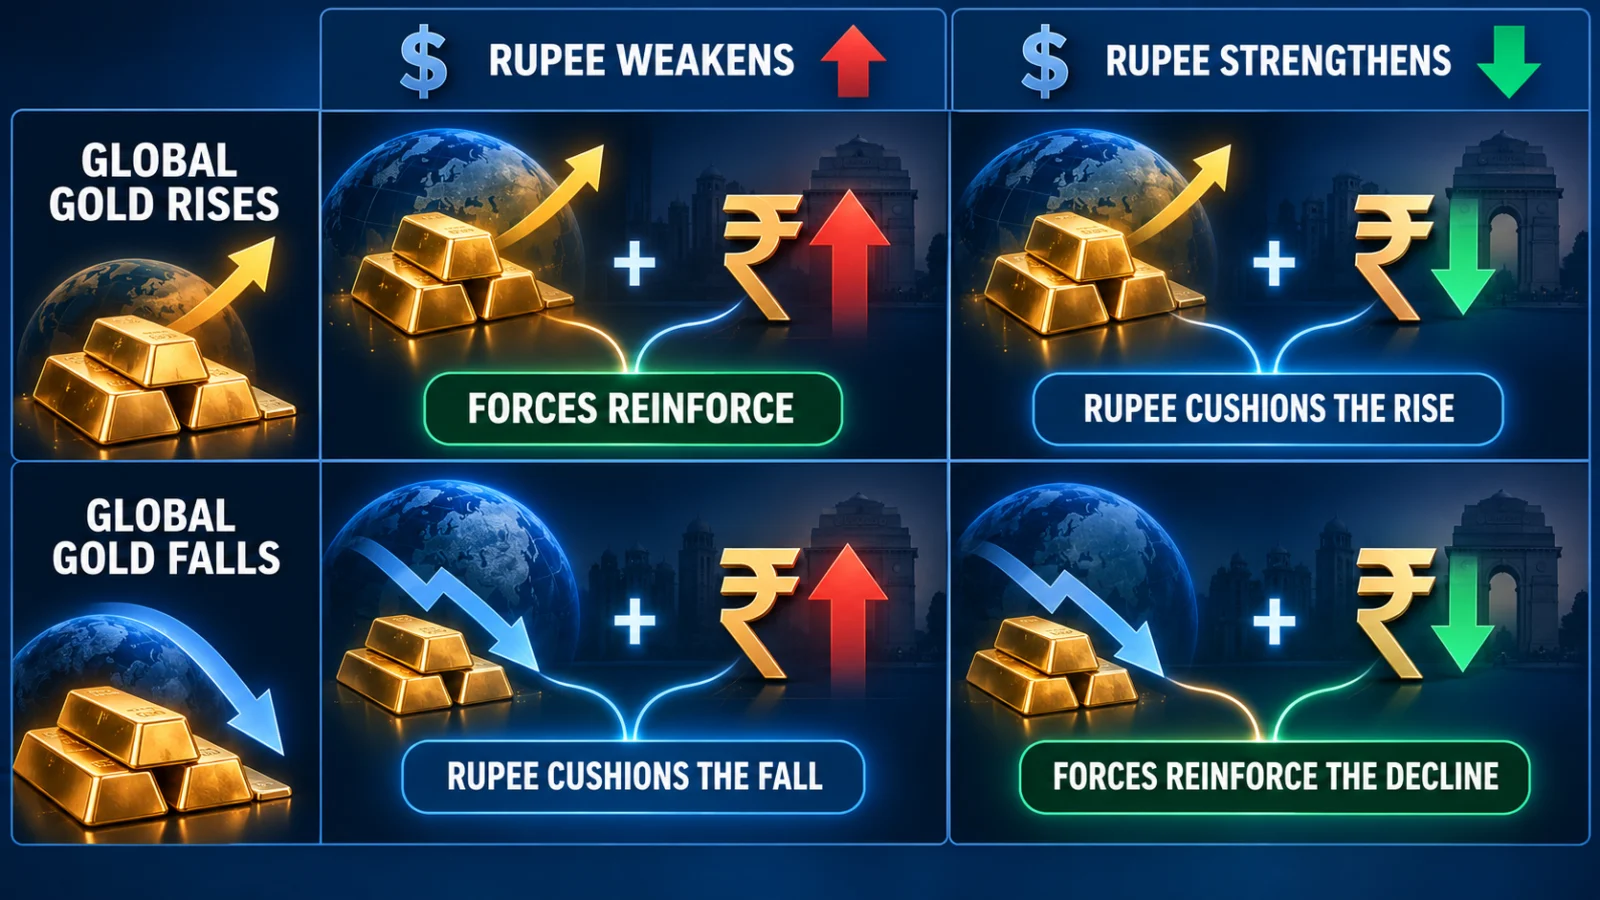
Four ways USD/INR and international gold can interact
| International gold | USD/INR / rupee state | Transmission into Indian gold |
|---|---|---|
| Rises | Rupee weakens | The forces can reinforce each other, making the translated Indian increase larger. |
| Rises | Rupee strengthens | Rupee appreciation can cushion part of the international rise. |
| Falls | Rupee weakens | Currency weakness can cushion part of the international decline in rupee terms. |
| Falls | Rupee strengthens | The forces can reinforce the decline in the translated rupee value. |
These scenarios explain direction, not a guaranteed percentage outcome. International gold and USD/INR can move simultaneously, while Indian duties, taxes, premiums and local-market conditions may also change.
Why Indian gold can move differently from international gold
An international gold headline tells only one part of the Indian price story. When global gold moves, the Indian result depends partly on what happened to USD/INR over the same period.
World Gold Council India updates during 2026 repeatedly documented differences between international and domestic gold performance. In some periods rupee depreciation supported the Indian price; in August, rupee appreciation partly offset an international rise. These opposite-direction examples show that currency transmission can either reinforce or counter the global move.
USD/INR does not determine the entire Indian gold price
USD/INR transmission is the ownership boundary of this explainer, but it is not the only component of the final domestic price. Import duties and applicable taxes, domestic premiums or discounts, local supply and demand, bullion-market conditions, purity and retail making charges can all affect what an Indian buyer ultimately pays.
That is why a simplified currency conversion should not be treated as an exact jewellery-shop invoice calculator.
Why a 1% rupee move does not guarantee a 1% retail-gold move
A common mistake is to assume that a 1% rupee depreciation must produce an immediate 1% rise in every Indian gold quote. That conclusion ignores the fact that international gold itself may be moving and that other domestic pricing layers may change at the same time.
The safer interpretation is directional: a weaker rupee creates upward pressure on the rupee translation of dollar-priced gold, while a stronger rupee creates downward pressure on that translation. The final observable Indian price reflects the interaction of that FX effect with the rest of the pricing chain.
What this article owns — and what the broader TPS gold hub owns
This article owns one narrow but recurring India-specific reader problem: USD/INR transmission into Indian gold prices. It explains what happens after an international dollar gold price is translated into rupees and why currency movements can amplify, cushion or offset that international move.
The separate TPS macro hub, Why Is Gold Price Falling Despite War?, owns the broader question of what moves international gold itself, including war and geopolitical risk, real yields, interest rates, the broader US dollar, ETF and investment flows, central-bank demand and other competing macro forces.
The two canonicals therefore solve different reader jobs: the macro hub explains why global gold moves; this page explains how USD/INR transmits that move into Indian gold prices.
A simple way to interpret an Indian gold-price move
When Indian gold and international gold appear to be moving differently, first identify what happened to international gold in US dollars. Then check whether the rupee strengthened or weakened against the dollar during the same period.
If those two movements still do not explain the full domestic change, the remaining difference may involve Indian-specific layers such as duties, taxes, premiums, supply-demand conditions or product-level pricing.
The useful conclusion is not that the rupee controls gold. It is that USD/INR is a major transmission channel between the dollar-denominated international gold market and the rupee-denominated price seen in India.
Verification note
TPS reviewed multiple World Gold Council India market updates and research from 2026. The evidence includes periods in which rupee depreciation supported domestic gold prices and an August example in which rupee appreciation partly offset an international rally. TPS uses those opposite-direction cases to establish the USD/INR transmission mechanism without treating currency as the sole determinant of Indian gold prices.
Limitations and unresolved facts
This explainer describes a pricing mechanism rather than predicting future gold or currency movements. The exact pass-through from USD/INR to any specific bullion, exchange or retail jewellery quote is not fixed because international gold, duties, taxes, premiums, local conditions and product-level charges can move simultaneously.