






Can gold make you rich? Gold can make an invested amount substantially larger if its market price rises over a long period. That is real wealth growth. But it is not the same mechanism as a business earning more profit, a bond paying contractual interest or a company distributing dividends.
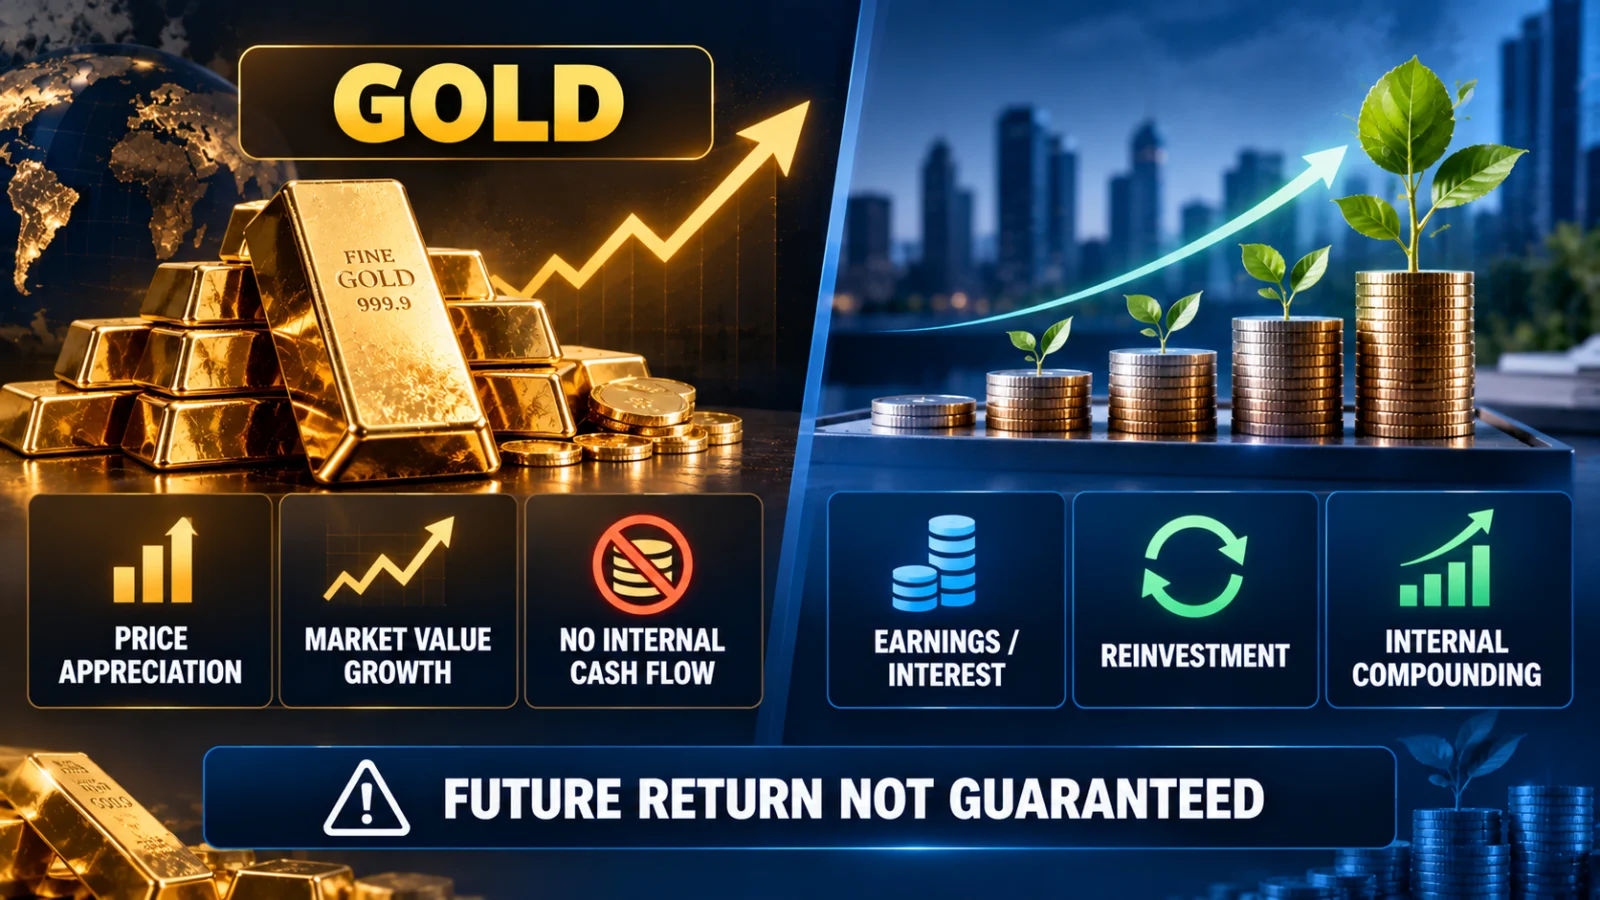
The important distinction is between price-return compounding and internal economic compounding. Gold can show a compounded annual growth rate because its market price can rise from one year to the next. The metal itself, however, does not generate earnings, rent, coupons or dividends that are automatically reinvested to produce more gold.
Two different meanings of compounding
Gold: price-return compounding
If gold rises from one price level to another over many years, the market value of the holding can grow at a compounded annual rate. The investor’s gain depends primarily on the future price path, with currency, costs, taxes and product structure affecting the final result.
Income-producing assets: internal compounding
A business can retain and reinvest earnings, while some securities can pay interest or distributions. Those cash flows can themselves generate additional returns. Physical gold does not contain that internal earnings or coupon engine.
So can gold actually create wealth?
Yes, if by wealth creation you mean that the market value of the capital you invested becomes substantially larger. Historical gold prices show that this has happened over long periods.
World Gold Council research for its 2026 strategic-asset study reports long-term positive returns across multiple horizons and calculates roughly 9% annualised US-dollar returns since 1971. That is a historical result for a particular start date, currency and measurement period. It is not a promised return for the next decade.
This is why the statement “gold cannot create wealth” is too absolute. A person who bought gold at a much lower market price and later sold at a substantially higher price did experience a real increase in nominal wealth.
But gold does not create that return from earnings
The other half of the answer matters just as much. Gold does not operate like a company. An ounce of gold does not earn profit, hire more workers, sell more products or reinvest retained earnings. Physical gold does not pay a contractual interest rate or a business dividend simply because you hold it.
World Gold Council’s own risk discussion identifies the lack of regular cash flow as an important characteristic of gold. Without a separate income-producing structure around the holding, the investor depends on price appreciation to generate the economic gain.
That makes gold’s wealth-building mechanism highly dependent on what another buyer is willing to pay for the asset in the future. That does not make the return unreal. It means the source of the return is different.
Why “gold does not compound” can be misleading
The phrase is often used to mean that gold does not internally produce earnings or cash flows. In that sense, it is useful. But taken literally, it can confuse readers because any asset whose market price grows from one level to another over several years can be described with a compounded annual growth rate.
Suppose an asset rises from a starting value to a much larger value over ten years. The annualised growth calculation mathematically compounds that price change. Nothing about that calculation proves the underlying asset generated internal income.
So two statements can both be true:
- Gold’s market value can compound through sustained price appreciation.
- Gold itself does not internally compound business earnings, dividends or contractual interest.
That distinction is the core of the wealth question.
Where does a gold investor’s return actually come from?
For a straightforward gold holding, the central source of return is the change in the market price between purchase and sale. The investor’s actual net result can then be affected by several additional layers.
Gold price appreciation
The primary driver of nominal wealth growth from the holding itself.
Currency movement
An Indian investor sees the result in rupees, so INR movement can make local gold returns differ from US-dollar gold returns.
Costs and spreads
Buying, selling, storage, fund charges or jewellery-related costs can reduce what the investor actually keeps.
Taxes and product structure
Net investor outcomes can differ depending on how gold is held and the applicable tax treatment.
Why Indian gold returns can differ from global gold returns
An Indian investor measures wealth in rupees, not only in US dollars. That matters because local gold performance reflects both the underlying international gold price and currency effects.
World Gold Council’s India-focused 2026 research notes that rupee depreciation has historically added resilience to Indian-currency gold returns. The reverse also matters: currency movement should not be treated as a guaranteed permanent boost.
TPS explains the currency transmission mechanism separately in Why Does the Rupee Affect Gold Prices in India?. On this page, the important point is simply that an Indian holder’s wealth outcome can differ from the return quoted for gold in US dollars.
Gold can still disappoint for years
Long-term positive history does not mean the path is smooth. World Gold Council’s risk analysis notes that gold has experienced individual years with gains around 30% and losses around 30%, as well as periods of medium-term underperformance.
A person who buys after a major rally can therefore experience a very different outcome from someone who accumulated during a weak period. The same asset can look like an exceptional wealth creator over one start-and-end window and a disappointing holding over another.
This is why a recent rally should not be converted into a permanent expected CAGR.
Does gold preserve wealth or create wealth?
The usual “wealth creator versus wealth protector” argument is too binary.
Gold can contribute to wealth growth because its price can rise materially over time. It can also serve a portfolio role through diversification, liquidity and resilience during certain market environments. Those functions are not mutually exclusive.
What gold does not offer is a guaranteed internally generated growth engine. Its market price must ultimately do the work.
What about inflation?
Gold’s long-term history includes periods in which it preserved purchasing power, but the relationship with inflation is not mechanically reliable over every short or medium holding period.
That is a separate reader question from whether gold can build nominal wealth. TPS covers the inflation question in Is Gold Really an Inflation Hedge? When It Works and When It Doesn’t.
Why historical returns are not a fortune formula
A historical annualised return is a description of what happened between two dates. It is not an interest rate attached to gold and it does not tell you what the next ten years must deliver.
Changing the starting date, ending date, currency and holding period can materially change the reported CAGR. Costs and taxes can also make an investor’s realised result different from the headline market return.
That is why the strongest historical gold return figure should never be turned into statements such as “gold compounds at 9%” or “gold will double every eight years.” The evidence does not establish a contractual or guaranteed return.
Does this mean productive assets are always better?
No universal conclusion follows from gold’s lack of internal cash flow. Productive assets and gold have different economic characteristics, risk paths and portfolio roles, and their relative performance depends heavily on the period being measured.
This article therefore does not rank gold against equities, property or bonds or tell readers which asset will create the most wealth. That would require a separate comparison using consistent periods, risk measures, income assumptions, costs and investor objectives.
Should everyone hold the same percentage in gold?
No. World Gold Council research includes hypothetical portfolio studies in which adding gold improved historical risk-adjusted outcomes, including India-focused analysis. Those simulations are useful evidence about portfolio behaviour, but they are not a universal allocation prescription for every investor.
Age, liquidity needs, existing assets, liabilities, risk tolerance, investment horizon and the form in which gold is held can all change the decision. TPS does not convert historical model portfolios into personalised allocation advice.
Bottom line: can gold make you rich?
Gold can make an invested corpus materially larger when its market price appreciates over a long holding period. Historical evidence shows that gold has produced substantial long-term returns, so it is inaccurate to say gold can never create wealth.
But gold is not a guaranteed compounding machine. The metal itself does not generate business earnings, contractual interest or dividends. Its wealth-building power depends primarily on future price appreciation, while an Indian investor’s result can also be influenced by the rupee, costs, taxes and the chosen holding structure.
The useful distinction is therefore not “wealth creator or wealth protector?” It is this: gold can compound in market value, but it does not internally compound earnings or cash flow. Understanding that difference is more useful than either extreme slogan.