






How to calculate gold returns in India correctly starts with a simple distinction: a rise in the quoted gold price is not automatically the return you actually earned.
Your real investment outcome depends on the money you paid to acquire the gold, the amount you receive when you sell or redeem it, costs at both ends, applicable tax and the loss of purchasing power caused by inflation.
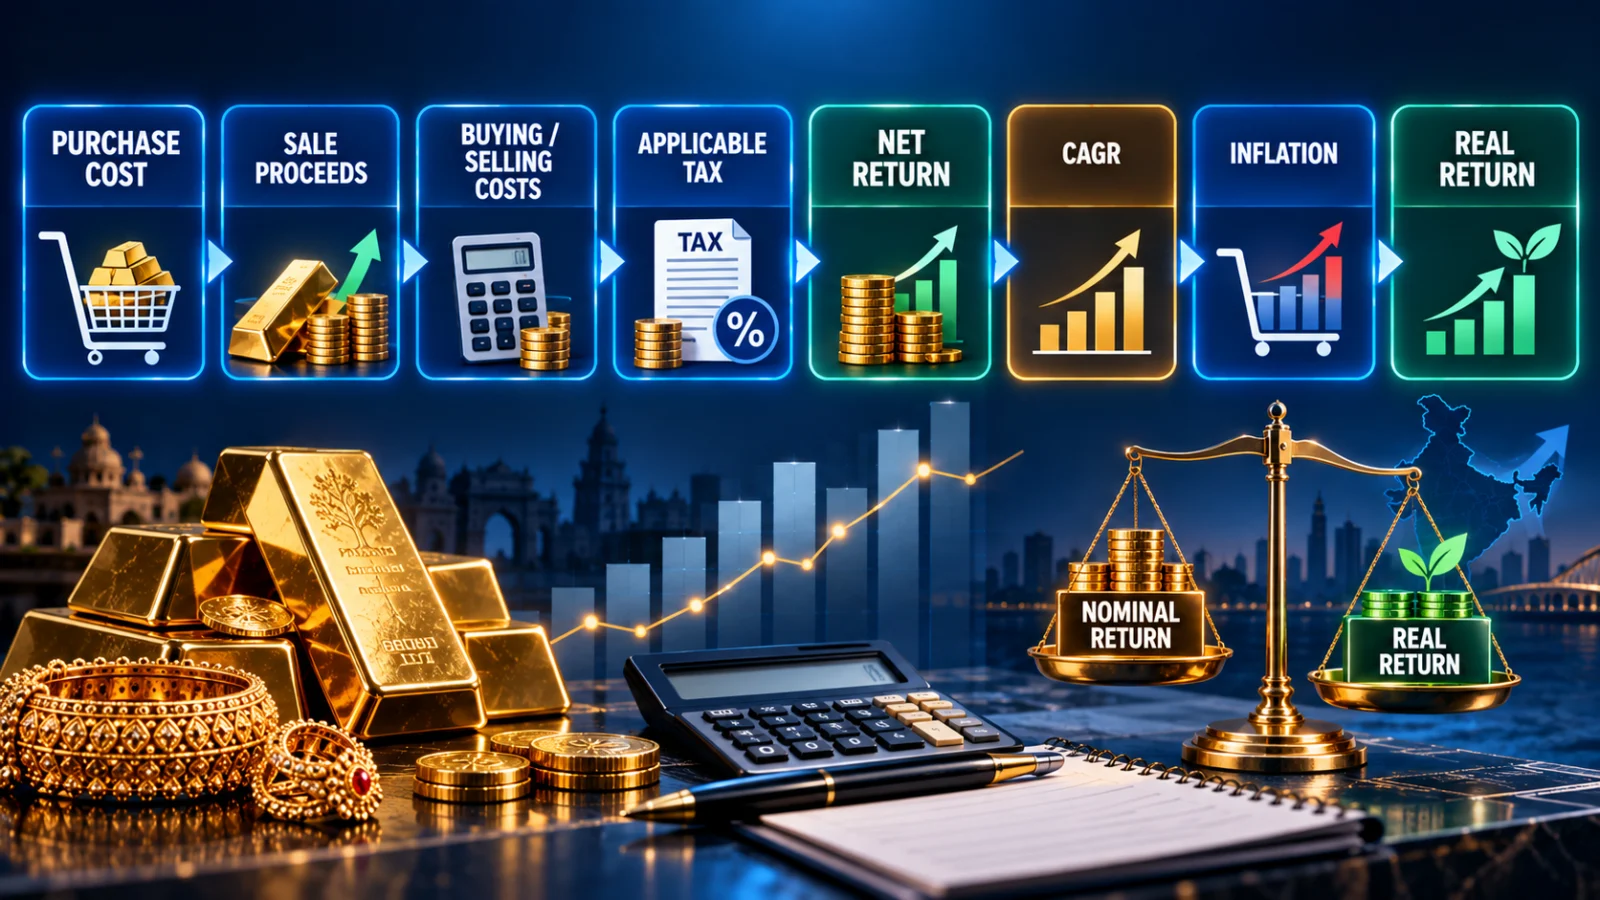
A useful calculation therefore moves through several layers: gross price change → net cash profit → total return → annualised return → inflation-adjusted real return.
The five return numbers readers should not confuse
| Measure | What it tells you | What it can miss |
|---|---|---|
| Gold-price change | How much the reference gold price moved | Your purchase costs, selling costs and tax |
| Net profit | How many rupees you gained or lost after relevant cash costs | How long the money was invested |
| Total return % | Profit or loss relative to the money invested | Annualisation |
| CAGR | Annualised growth rate for a simple beginning-to-ending investment | Intermediate cash flows such as SGB interest |
| Real return | Return after accounting for inflation | Your personal inflation experience may differ from the chosen inflation series |
1. Start with the cash you actually invested
For economic-return measurement, the beginning value should reflect the money that actually left your pocket to acquire the investment.
For a physical-gold purchase, that can include the purchase consideration and acquisition costs actually borne. If you bought jewellery, the cash outflow can also include making or value-addition charges and other amounts you paid even if those amounts are not recoverable when you later sell the jewellery.
For a Gold ETF or fund, use the actual acquisition cash outflow relevant to your investment rather than reconstructing the investment from a historical headline gold rate.
This economic-return calculation should not be confused with the statutory tax cost base. Tax computation follows applicable law and may classify particular costs differently.
2. Work out the proceeds you actually receive
Start with the amount received from the sale, redemption or exit. Then account for selling or exit costs actually borne.
For physical gold, that can mean the dealer or jeweller’s actual buyback amount rather than the day’s headline gold rate. Purity adjustment, product form and buyback terms can affect the cash you receive.
For exchange-traded products, the relevant ending value should reflect the actual transaction or a clearly labelled mark-to-market value if the investment has not yet been sold.
An unrealised current value and realised sale proceeds are not the same thing. If you still hold the investment, describe the result as an estimated or mark-to-market return rather than realised profit.
3. Calculate net profit before annualising it
A practical economic framework is:
Net sale proceeds = gross sale proceeds − selling costs − applicable tax attributable to the disposal
Total acquisition cost = purchase consideration + acquisition costs actually borne
Net profit = net sale proceeds − total acquisition cost
Then calculate:
Net return % = net profit ÷ total acquisition cost × 100
This answers the basic question: after the costs included in your calculation, how much did you actually gain or lose relative to the money invested?
4. CAGR tells you the annualised rate, not just the total gain
A 30% total return over two years is not the same performance as a 30% return over ten years. CAGR converts a simple beginning-to-ending investment into an annualised rate.
The standard formula is:
CAGR = (Ending value ÷ Beginning value)^(1 ÷ years) − 1
If you want an after-cost or after-tax CAGR, the beginning and ending values must be economically consistent. For example, compare your actual initial cash outflow with the appropriate net terminal value rather than mixing a gross gold-price quote at one end with an after-tax cash value at the other.
5. When CAGR is not enough
CAGR works best when there is one beginning cash outflow and one ending value.
It becomes incomplete when material cash flows occur during the holding period. Sovereign Gold Bonds are an important example because they can pay periodic interest while the investment is outstanding.
If those interest receipts are part of the return you want to measure, a simple start-to-end CAGR does not represent the complete investor experience. A dated cash-flow return such as XIRR is more appropriate.
For an SGB XIRR calculation, record the purchase as a negative cash flow, each interest payment as a positive dated cash flow and the final sale or redemption amount as the last positive cash flow. If measuring an after-tax outcome, tax cash flows should be incorporated consistently.
6. Nominal return is not the same as real return
Nominal CAGR tells you how quickly the rupee value of the investment grew. It does not tell you how much purchasing power you gained.
Inflation reduces what a rupee can buy, so a long-term return should also be viewed in real terms.
The exact compound relationship is:
Real CAGR = (1 + nominal CAGR) ÷ (1 + inflation CAGR) − 1
Simply subtracting inflation from nominal CAGR can be a useful rough approximation when both rates are small, but it is not the exact compounded result.
Use an inflation measure covering the same holding period as the investment. A broad CPI measure can provide a consistent benchmark, although an individual household’s actual inflation experience can differ.
7. Worked example: why headline gold gains can overstate your result
Consider a hypothetical investor who spends ₹1,00,000 in total to acquire gold and later receives ₹1,35,000 before exit costs and tax.
If selling costs are ₹2,000, the pre-tax net proceeds become ₹1,33,000. The pre-tax economic profit is therefore ₹33,000, or 33% on the ₹1,00,000 cash invested.
If this outcome took five years, the investor should not describe the result as a 33% annual return. The CAGR calculation annualises the beginning and ending values over the five-year holding period.
If the investor then wants purchasing-power return, the resulting nominal CAGR should be adjusted for the compounded inflation rate over the same five-year period.
This example is deliberately tax-neutral because the applicable tax depends on the type of gold investment, holding period, transaction date and taxpayer facts.
8. Current physical-gold capital-gain treatment matters
Under the current post-July-2024 framework reviewed for this article, physical gold generally uses a 24-month threshold for long-term capital-gain classification rather than the older 36-month rule that still appears on some websites.
For relevant long-term transfers under the current general framework, the Income Tax Department describes a 12.5% long-term capital-gain rate without indexation.
That does not mean TPS can determine an individual’s final tax from the holding period alone. Exemptions, losses, taxpayer status, transaction date and other provisions can affect the actual computation.
9. Gold ETF and Gold Mutual Fund taxation must not be treated as identical by default
Current rules distinguish listed and unlisted units and also require attention to section 50AA.
Listed units generally fall into the current 12-month long-term holding bucket. Other unlisted units generally use a 24-month threshold, subject to the applicable statutory classification.
From April 2026, section 50AA’s specified-mutual-fund definition was narrowed to focus on funds investing more than 65% in debt and money-market instruments, and funds investing at least 65% in those debt-oriented funds. This change was important because the earlier definition could unintentionally capture products such as Gold ETFs and Gold Mutual Funds.
A reader should therefore verify the actual product, listing status and current tax classification instead of applying one generic “gold fund tax” rule to every vehicle.
10. Legacy SGB holdings need their own return calculation
Sovereign Gold Bonds require special care because the investor may receive both periodic interest and a later sale or redemption amount.
Under the 2026 rule reviewed for this article, the capital-gains exemption on maturity redemption is limited to an individual who subscribed at original issue and held the SGB continuously until redemption at maturity.
The current exemption should not be generalised to SGBs purchased in the secondary market or to premature redemption cases. Periodic SGB interest is also a separate taxable cash flow.
That is another reason an SGB’s complete investor return may require XIRR rather than a simple CAGR based only on issue price and maturity value.
11. Jewellery return is especially easy to overstate
Jewellery combines metal value with a finished product. The cash paid can include making or value-addition charges, tax and other retail components, while the resale offer may primarily reflect recoverable gold value and the buyer’s commercial policy.
For economic-return measurement, cash that you actually paid but do not recover still affects the investment outcome. Ignoring those amounts can make the calculated return look better than the financial result you actually experienced.
This does not mean jewellery has no value beyond investment return. Wearable, gifting and personal utility are separate benefits. It means those benefits should not be confused with financial return.
12. Use the same basis throughout the calculation
Many return errors come from mixing incompatible inputs. Examples include comparing a jeweller’s invoice with an international spot rate, using a gross sale price against a purchase amount that included all costs, or comparing a pre-tax beginning value with an after-tax ending value.
Choose the return you want to measure—gross market return, economic return, after-tax return or real purchasing-power return—and use consistent inputs from beginning to end.
A practical gold-return calculation path
1. Identify the gold vehicle
Physical bullion, jewellery, Gold ETF, Gold Mutual Fund and SGB can have different costs, cash flows and tax rules.
2. Record the actual acquisition cash outflow
Use what you actually paid, including relevant acquisition costs for the economic-return calculation.
3. Record the ending value or realised proceeds
Distinguish an unsold mark-to-market value from an actual sale or redemption.
4. Deduct exit costs
Use actual selling, brokerage, spread, buyback or other relevant disposal costs.
5. Apply the correct current tax branch
Check the vehicle, holding period, transaction date and current law before using a tax figure.
6. Calculate net profit and total return
Compare net proceeds with the total acquisition cash outflow.
7. Annualise the result
Use CAGR for a simple beginning/end investment and XIRR when material dated cash flows occur during the holding period.
8. Adjust for inflation
Convert the nominal annualised return into a real purchasing-power return using the compound real-return formula.
Gold return calculation: the bottom line
A gold-price chart answers one question: how the quoted market price moved. It does not automatically answer how much money you earned.
For a useful personal return calculation, start with actual cash invested and actual or estimated ending proceeds, include the costs that affected your transaction, apply the correct current tax treatment, annualise the result appropriately and then adjust for inflation.
That produces a much more meaningful answer than simply saying gold rose by a certain percentage between two dates.