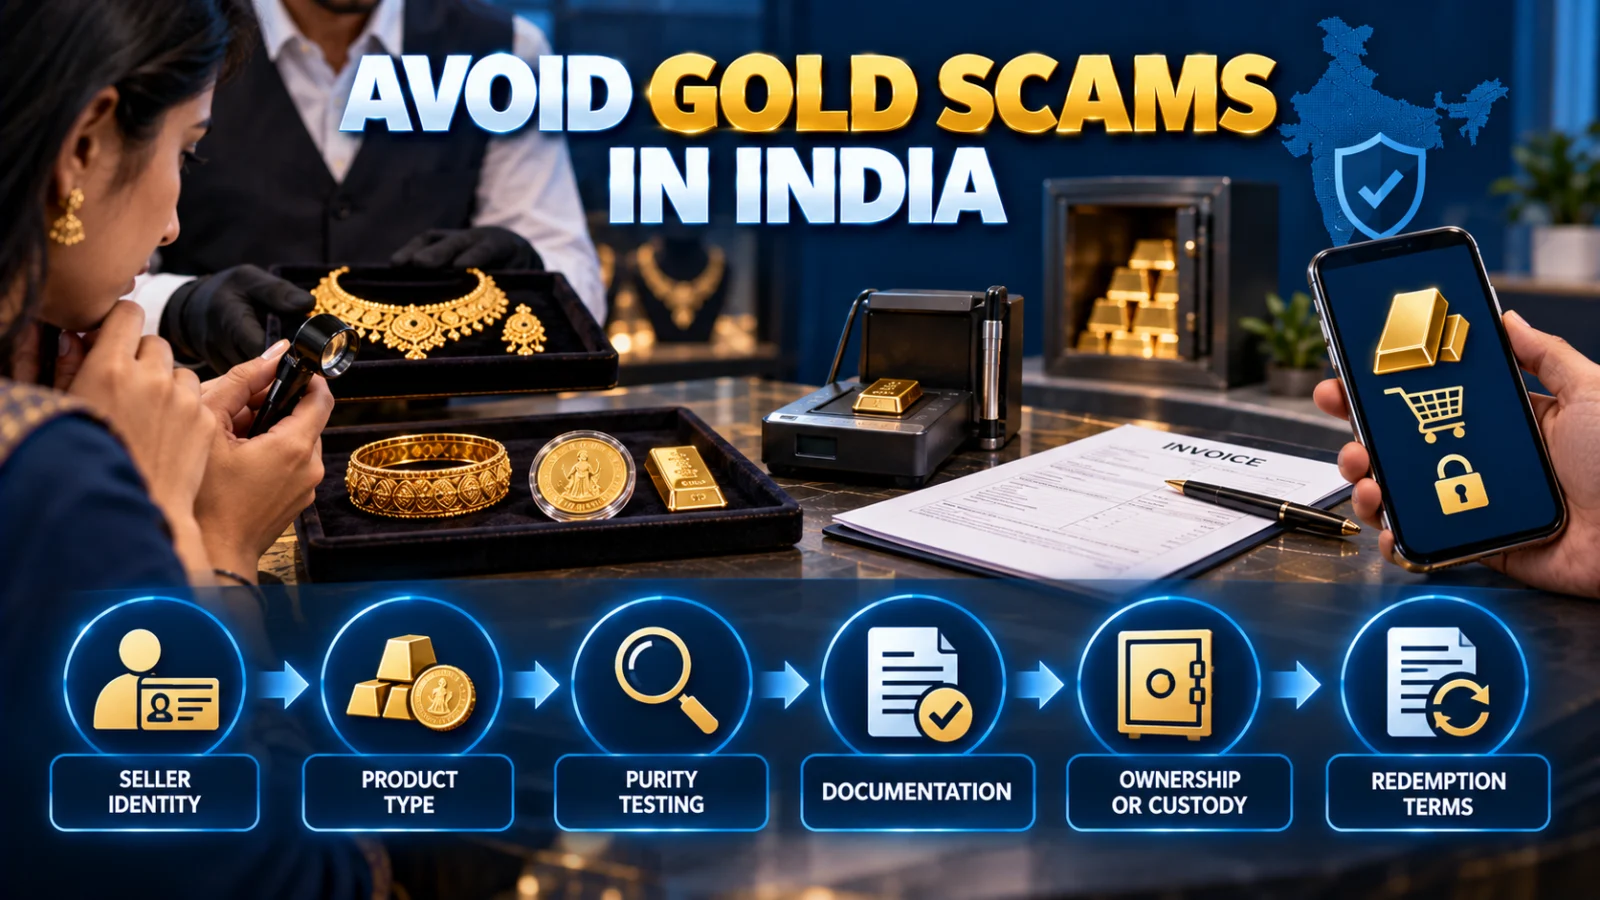
How to avoid gold scams in India starts with one rule: do not verify only the gold. Verify the seller, the product, the evidence and the exit terms before you pay.
A genuine-looking shop, hallmark, app or promise of gold ownership does not answer every risk question. Physical jewellery has BIS-backed verification routes for applicable hallmarked articles. Digital-gold products can involve a completely different ownership and regulatory structure. Investment pitches can add another layer of risk if they promise guaranteed or unusually certain returns.
The practical goal is not to make a transaction “scam-proof.” It is to stop before payment when a material part of the deal cannot be independently understood or verified.
Know the legal jeweller, company or platform receiving your money.
Jewellery, coin, bar, Gold ETF, EGR and privately offered digital gold are not interchangeable.
Use BIS tools for applicable jewellery and read the actual contractual terms for indirect or digital ownership.
Know how you can sell, redeem, receive physical gold or complain before committing money.
1. Verify who is actually selling the gold
Start with the legal seller or provider, not the advertisement.
For hallmarked precious-metal articles, BIS maintains registration and licence information for jewellers and provides verification tools through BIS resources and the BIS Care app. A familiar shop name, marketplace listing or social-media account should not replace those checks where BIS registration is relevant.
For an online or digital product, identify the company that is legally responsible for the transaction. The app or marketplace you see may not necessarily be the same entity that holds the underlying asset or owes you money on redemption.
If you cannot identify the actual counterparty receiving or owing your money, do not proceed yet.
2. Identify exactly what gold product you are buying
“Gold” can describe very different products.
- hallmarked jewellery;
- physical coins or bars;
- Gold ETFs;
- Electronic Gold Receipts;
- commodity-derivative exposure; or
- privately offered digital gold or e-gold products.
The protections are not identical. SEBI has specifically cautioned that the digital-gold or e-gold products covered by its warning are different from SEBI-regulated securities-market gold products such as Gold ETFs and EGRs.
Do not assume that because a product tracks gold, it automatically receives the same investor-protection framework as a regulated security.
3. For jewellery, verify the actual HUID instead of trusting the stamp alone
A visible hallmark or HUID should be checked, not merely admired.
BIS provides a Verify HUID facility through the BIS Care app. Use it to check the six-character HUID on the article and reconcile the returned details with the jewellery you are being asked to buy.
TPS already has a dedicated guide to checking gold purity and HUID before buying. The important point here is broader: HUID verification is one fraud-control layer, not proof that every commercial promise in the transaction is safe.
4. Check purity, weight and the invoice together
Do not evaluate the gold and the bill as separate documents.
BIS consumer guidance says an invoice for a hallmarked article should contain information including the description of the article, net weight of precious metal, purity in carat and fineness, and hallmarking charges.
Compare those details with what you physically received and with the purity information you verified.
Do not assume that HUID must appear on the invoice itself. BIS states that mentioning the HUID number on the invoice is voluntary, so the absence of HUID from the invoice alone should not be described as proof of fraud.
5. Use independent testing when purity remains doubtful
If the article is old, unusual, expensive, inconsistent with its documentation or otherwise doubtful, BIS gives consumers an independent testing route.
Consumers can have hallmarked or unhallmarked jewellery tested at a BIS-recognised Assaying and Hallmarking Centre on a chargeable basis and receive an assay report for the tested article.
That is stronger evidence than relying on a seller’s verbal reassurance when the transaction is consequential.
6. For digital gold, verify what you actually own and who holds it
This is the point where physical-gold logic can become misleading.
SEBI warned that the digital-gold products covered by its November 2025 caution operate outside its securities-market regulatory purview and can expose investors to counterparty and operational risks. SEBI also said securities-market investor-protection mechanisms do not apply to those products.
That warning does not mean every digital-gold product is fraudulent or banned. It means a buyer should not assume the regulatory protection of a Gold ETF merely because both products reference gold.
Before paying, determine from the provider’s current terms:
- which legal entity owes you the gold or money;
- what ownership or contractual right you receive;
- how the provider says the underlying gold is held or custodied;
- what evidence supports any claim that the gold is backed or audited;
- what happens if the provider, custodian or another counterparty fails; and
- which complaint or dispute mechanism applies.
These arrangements are provider-specific. TPS does not assume one custody or backing structure applies to every digital-gold service.
7. Read redemption, sale and delivery terms before you pay
A gold product can look simple while the exit is not.
Before buying digital or indirectly held gold, check how you can leave the product. Look for the provider’s current rules on sale, redemption, minimum quantities, physical delivery, delivery charges, spreads, fees and any time limits.
For physical jewellery or bullion, separately understand the seller’s current exchange or buyback policy. A future buyback promise is a commercial term, not the same thing as guaranteed value.
If the seller’s headline promise sounds attractive but the exit conditions are missing or difficult to understand, do not treat the headline promise as sufficient evidence.
8. Reject guaranteed-return and pressure-based gold pitches
Gold itself does not create a guarantee of investment returns.
SEBI’s investor-scam guidance warns consumers about red flags such as guaranteed or unusually certain returns, unregistered entities, weak documentation and pressure to act quickly.
Those warnings matter when someone uses the word “gold” to make an investment pitch appear inherently safe.
Pause when a seller or promoter:
- promises a fixed or guaranteed return without a clear regulated product structure;
- asks you to pay immediately before verification;
- discourages written documentation;
- uses regulator names or logos as a substitute for verifiable registration;
- asks for payment to an unrelated personal account; or
- cannot explain how you will prove ownership or recover value later.
9. Preserve evidence and know the redress route
Verification matters before payment, but evidence matters afterward.
Preserve the purchase invoice, product description, payment proof, order confirmation, relevant HUID verification result, contractual terms and any written representations about custody, redemption or returns.
For applicable hallmarked jewellery, BIS provides complaint and consumer-protection mechanisms. BIS also provides compensation provisions when hallmarked jewellery is found, under the applicable testing and investigation process, to have lower purity than marked.
Those BIS protections should not be extended to unrelated digital-gold disputes unless the specific legal framework actually applies.
Can you identify the real legal seller or provider?
Do you know whether you are buying jewellery, bullion, a regulated security or privately offered digital gold?
For applicable jewellery, have you checked hallmark and HUID evidence rather than trusting a visible stamp?
Do the description, net precious-metal weight and purity match what you are buying?
For indirect or digital gold, what legal right do you actually receive?
Who says the underlying gold is held, and what evidence supports that claim?
Can you understand sale, redemption, delivery, fees and spreads before paying?
Are guaranteed returns, pressure or unverifiable regulator claims being used?
Will you receive and preserve the documents needed to prove the transaction or complain later?
The walk-away rule
Do not pay merely because most of the transaction looks legitimate.
If you cannot identify the seller, identify the product, verify the relevant physical-product evidence, understand what ownership right you receive, reconcile the documentation or understand how you can exit, the safest conclusion is not yet.
You do not need to prove that something is a scam before declining to send money. An unresolved material verification gap is enough reason to stop until it is cleared.
What this checklist does not prove
Completing these checks cannot guarantee that fraud will never occur. Scam techniques, private-platform structures and commercial terms change. A verified HUID does not validate every sales promise, and SEBI’s warning about digital gold does not mean every provider is fraudulent.
The checklist is designed to reduce avoidable trust failures by forcing the buyer to verify the transaction at several independent layers before payment.
Verification note
TPS reviewed BIS consumer-protection, BIS Care, jeweller-registration, invoice, purity-testing and compensation guidance alongside SEBI’s digital-gold caution and investor-scam guidance. Physical-jewellery protections were kept separate from provider-specific digital-gold custody and redemption claims.
Limitations and unresolved facts
Digital-gold custody, backing, audits, insurance, insolvency treatment, redemption minimums and fees can vary by provider and were not generalised. Future scam methods and regulatory changes remain possible. TPS has not established that all digital-gold providers are fraudulent, that digital gold is banned, or that these nine checks eliminate fraud risk.