






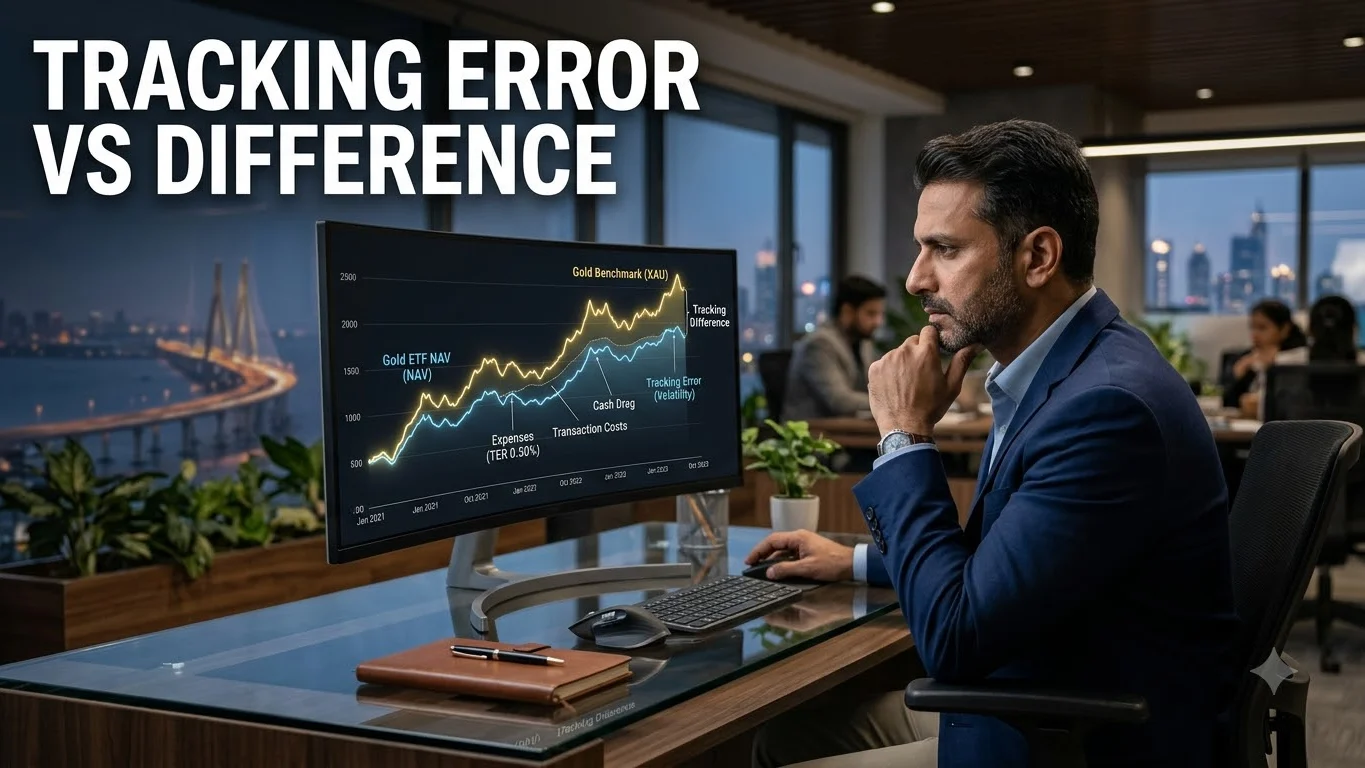
Gold ETF tracking error vs tracking difference answers two different questions about how closely a Gold ETF follows gold. Tracking difference tells you how far the ETF’s NAV return ended up from its benchmark return. Tracking error tells you how variable that benchmark-versus-NAV gap was over time.
Direct answer: Tracking difference measures the return gap between the Gold ETF’s NAV and its gold benchmark. Tracking error measures how consistently that gap behaves. Neither is the same as an ETF trading at a premium or discount to NAV on the stock exchange.
Tracking difference and tracking error are not the same metric
| Metric | What it tells you | What it does not tell you |
|---|---|---|
| Tracking difference | How far the ETF’s NAV return differs from the return of the underlying gold benchmark over the measured period. | It does not show how stable or unstable that gap was day to day. |
| Tracking error | How variable the daily return differences between the ETF’s NAV and its benchmark were, expressed on an annualised basis. | It does not directly tell you the total percentage-point return lag by itself. |
| Premium or discount to NAV | How the ETF’s exchange trading price compares with its NAV at a point in time. | It is not a measure of how the fund’s NAV tracked gold. |
SEBI’s current passive-fund framework defines tracking error using the annualised standard deviation of daily return differences between the underlying index or goods and the ETF’s NAV. Tracking difference is separately defined as the annualised difference in daily returns between the benchmark and ETF NAV.
Why this distinction matters for a Gold ETF investor
An investor can buy a Gold ETF at a fair exchange price close to NAV and still see the fund’s NAV return lag the gold benchmark. That is because exchange execution and fund replication are two different layers.
Layer 1: gold benchmark return versus ETF NAV return. Tracking difference and tracking error belong here.
Layer 2: ETF NAV versus the price at which units trade on the exchange. Premium, discount, liquidity and bid-ask spread belong here.
A premium or discount therefore cannot explain every case where a Gold ETF underperforms gold. The fund’s own NAV may already be tracking the benchmark imperfectly before exchange trading price is considered.
What does tracking difference actually show?
Tracking difference is the more direct measure of the realised return gap. If the gold benchmark produced a higher return than the ETF NAV over the same measurement period, the tracking difference captures that divergence.
For an investor asking, “Why did my Gold ETF return less than gold?”, tracking difference is therefore the first metric to understand. But the number must be read using the same benchmark and measurement period reported by the scheme.
What does tracking error actually show?
Tracking error describes the variability of the benchmark-versus-NAV return difference. A lower tracking error generally means the ETF followed its benchmark more consistently over the measured period.
That does not automatically mean the ETF delivered the smallest cumulative return gap. A fund could theoretically trail its benchmark by a relatively consistent amount and therefore show low tracking error while still showing a meaningful tracking difference.
Can tracking error be low while tracking difference is still meaningful?
Yes. The two metrics measure different properties of the same replication process.
Imagine a Gold ETF that trails its benchmark by a small but relatively stable amount day after day. The consistency of the gap can keep tracking error low, while the repeated lag still produces a noticeable tracking difference over time.
That is why investors should not treat tracking error as a substitute for tracking difference or compare schemes using only one of the two metrics.
Why can a Gold ETF’s NAV lag gold?
A Gold ETF cannot always replicate the benchmark perfectly. Reviewed Gold ETF disclosures identify several possible sources of divergence.
- Scheme expenses: operating costs reduce the assets available to generate the benchmark return.
- Cash holdings: a portion of the portfolio may remain in cash or permitted liquid assets for redemptions, expenses or operational needs instead of being fully exposed to gold.
- Transaction costs: buying, selling, creating or redeeming positions can involve costs that the benchmark itself does not bear in the same way.
- Large subscriptions or redemptions: portfolio adjustments required to handle investor flows can introduce execution differences.
- Taxes and other operating frictions: scheme-level transactions can create additional divergence depending on the circumstances and governing rules.
Is expense ratio the same as tracking difference?
No. Expense ratio is one contributor to the gap, but it is not a complete explanation of tracking difference.
Two Gold ETFs with similar expense ratios can still show different tracking outcomes because portfolio cash, transaction execution, flows, operational choices and other scheme-specific factors can differ.
The expense ratio should therefore be read alongside tracking difference and tracking error rather than used as a shortcut for them.
Does lower tracking error always mean a better Gold ETF?
Not by itself. A low tracking error indicates more consistent replication of the benchmark, but an investor also needs to look at the actual tracking difference, expense ratio, liquidity, assets under management and other relevant scheme factors.
A single short measurement period can also be misleading. SEBI’s disclosure framework uses recurring reporting so investors can evaluate tracking behaviour across appropriate periods rather than freeze one temporary snapshot into a permanent ranking.
How SEBI requires the metrics to be disclosed
Under SEBI’s current mutual-fund framework, Gold and Silver ETFs follow the passive-fund tracking-error and tracking-difference disclosure provisions.
Tracking error is disclosed daily on the AMC and AMFI websites. Tracking difference is disclosed monthly for prescribed periods, including one year, three years, five years, ten years and since the date of allotment where applicable.
SEBI’s current framework also specifies a tracking-error ceiling for passive funds other than debt ETFs and index funds, subject to its stated exceptions and treatment for circumstances beyond the fund manager’s control.
How to read the two metrics together
Start with the actual tracking difference to see how far the Gold ETF’s NAV return diverged from its gold benchmark over the relevant period. Then look at tracking error to understand whether that gap was relatively stable or more volatile.
A consistently small gap is different from a gap that swings widely. A consistently larger gap is also different from a fund that occasionally deviates sharply but otherwise tracks closely. The combination gives a more useful picture than either number alone.
Do not confuse tracking metrics with NAV premium or discount
The ETF’s exchange price can trade above or below NAV because buyers and sellers transact in the market. That execution-price problem is distinct from whether the fund’s NAV itself replicated the gold benchmark accurately.
An investor can therefore experience two separate deviations: first, the Gold ETF’s NAV can differ from the benchmark return; second, the investor’s exchange purchase or sale price can differ from NAV.
Where should you check the current numbers?
Use the Gold ETF’s current AMC disclosures and AMFI tracking disclosures for the actual scheme and period being evaluated. Make sure the benchmark and period are comparable before drawing a conclusion from one fund versus another.
Avoid relying on an old screenshot, a single-month leaderboard or a comparison using different measurement periods.
Verification note
ThePulseSignal reviewed SEBI’s current tracking-error guidance and 2026 mutual-fund framework, together with current Gold ETF and industry disclosures showing tracking-error, tracking-difference and scheme-level causes of benchmark divergence.
Limitations and unresolved facts
This article does not rank individual Gold ETFs or claim that one scheme currently has the best tracking performance. Scheme-level tracking metrics change over time and must be checked using the latest AMC or AMFI disclosures for the same benchmark and measurement period.