How to sell gold in India without losing more than necessary is mainly a process-control problem. Before accepting a quote, establish what you actually have, how much recoverable gold is present, what purity the buyer is using, which reference rate applies and exactly what is being deducted.
The most important rule is simple: there is no evidence-backed universal percentage that all jewellers deduct. Commercial buyback and exchange policies differ by buyer, item type, purity, testing method, stones, transaction type and current offer terms.
Jewellery, studded jewellery, coin or bar.
Use hallmark information, product documentation or independent testing when necessary.
Separate precious-metal weight from stones and non-gold components.
Ask each buyer to disclose rate, weight basis, purity and deductions.
Do not compare a cash-sale quote with an exchange incentive as though they are identical.
Keep invoices, testing evidence, quote calculations, receipt and payment proof.
1. Identify exactly what you are selling
Start by separating the item into the right category: plain gold jewellery, studded jewellery, coin or bar. The valuation process can differ because jewellery may include stones, enamel, solder or other non-gold material, while a bullion coin or bar is usually easier to express as a stated weight and fineness.
Collect whatever evidence you already have: purchase invoice, hallmark or HUID details where applicable, refinery or mint certificate for bullion, product packaging and any earlier assay or testing report.
2. Verify purity before you compare prices
Purity directly affects how much fine gold is present. A buyer quoting against 22K gold is not valuing the same fine-gold content as a 24K product of identical gross weight.
The Bureau of Indian Standards allows consumers to have hallmarked or unhallmarked jewellery tested at BIS-recognised Assaying and Hallmarking Centres on a chargeable basis. The centre can issue an assay report identifying the tested article.
Independent testing can be especially useful when the item is old, unhallmarked, inherited, has unclear provenance or when the buyer’s purity result materially changes the quote.
3. Do not confuse gross jewellery weight with recoverable gold weight
This is one of the easiest ways to misunderstand a resale quote.
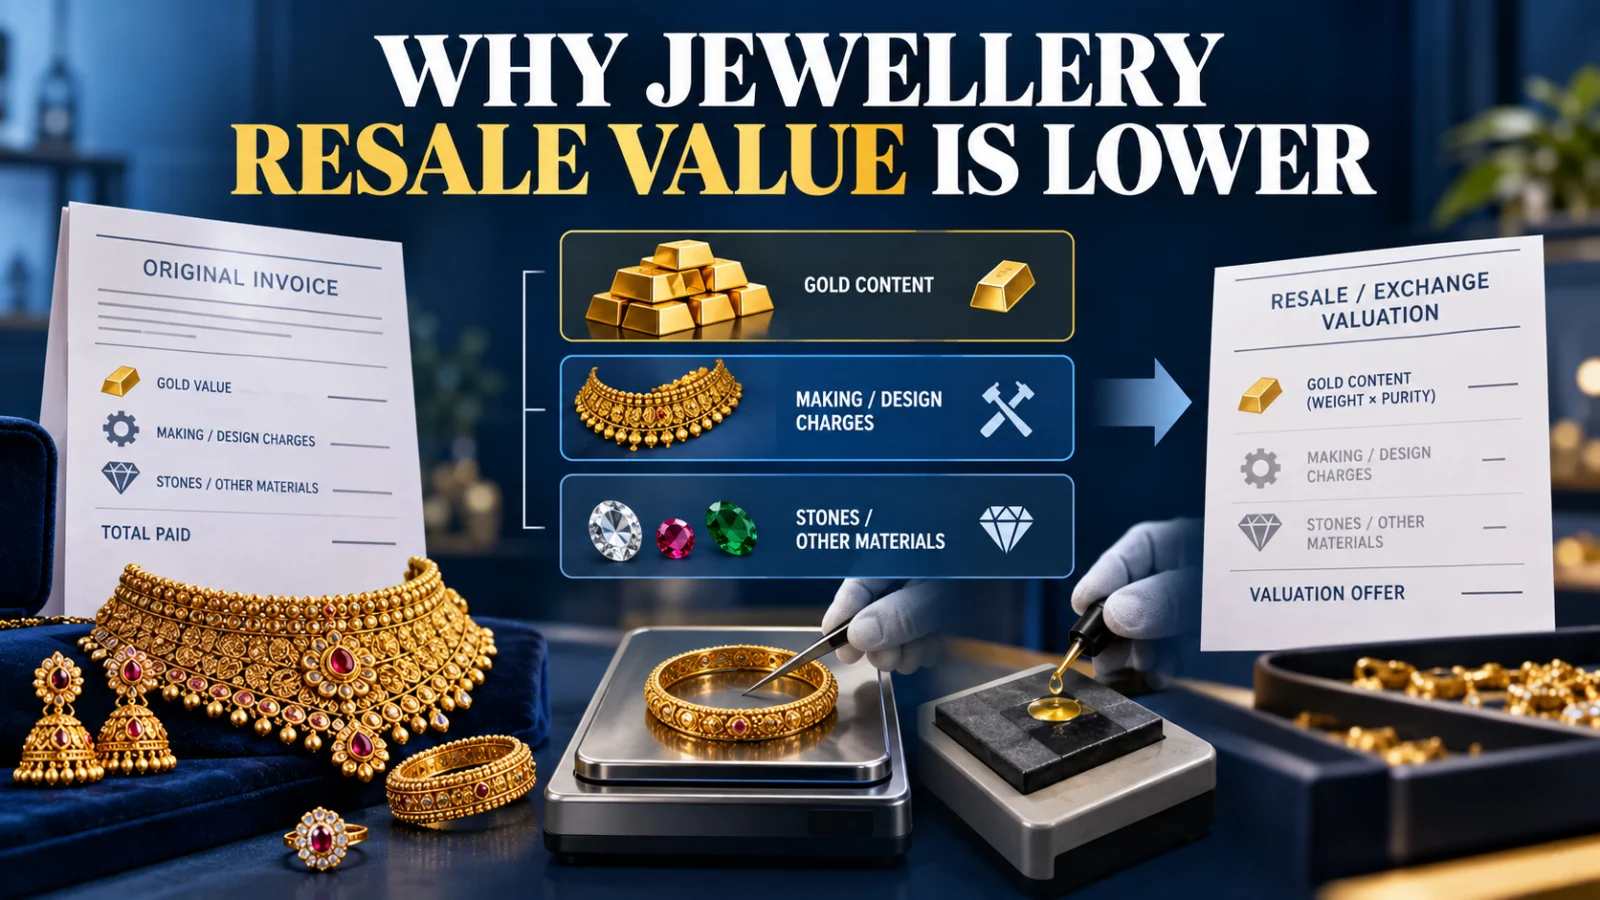
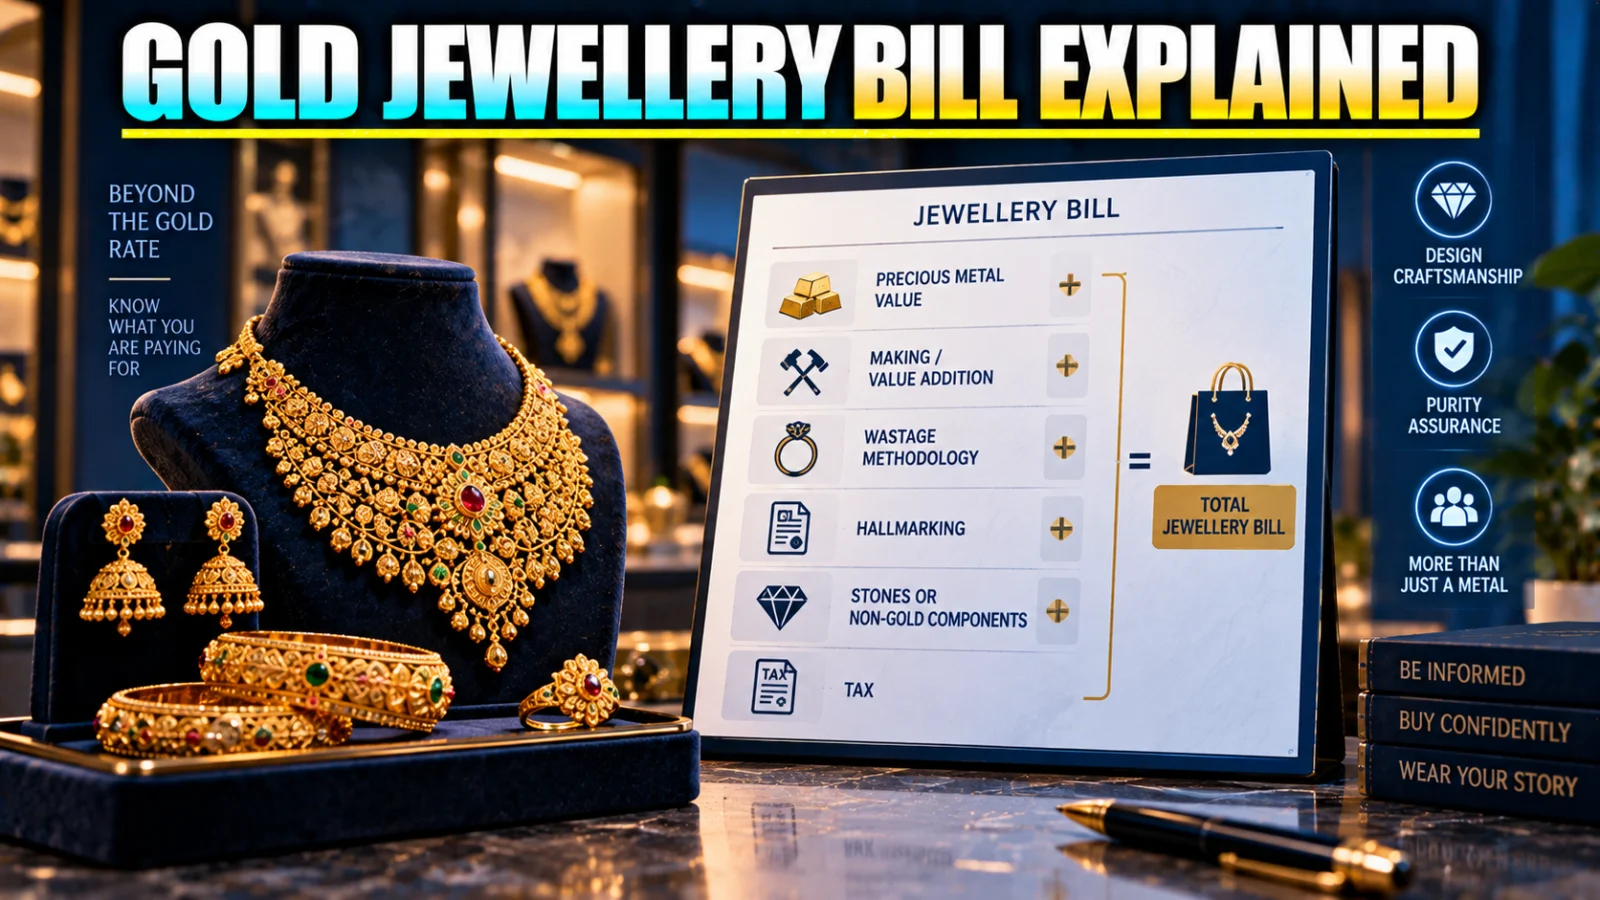
A jewellery item can weigh more than the precious metal it contains because stones and other non-gold components may be part of the gross weight. BIS invoice guidance for hallmarked jewellery specifically distinguishes the net weight of precious metal.
For a meaningful comparison, ask each buyer what gold weight it is actually valuing after stones and non-gold components are excluded or separately accounted for.
4. Keep stones and non-gold components separate
If you are selling studded jewellery, do not let a single headline amount hide how the buyer treated the stones.
Ask whether stones are being returned, assigned a separate value, ignored, or removed before the gold calculation. The treatment can differ by buyer and item.
The gold part of the quote should be understandable on its own. If a stone or other component receives a separate value, record that separately rather than mixing it into the gold price comparison.
5. Ask each buyer to show the calculation
A useful quote should allow you to understand at least these components:
- measured or accepted purity;
- recoverable or net gold weight;
- the reference gold rate used;
- gross metal value before deductions;
- each deduction, spread, melting/testing charge or other adjustment;
- separate stone value, if any; and
- final payable amount.
If two buyers use different assumptions, their final numbers are not directly comparable until those assumptions are normalised.
There is no universal jeweller deduction percentage
TPS found no universal deduction percentage in the reviewed official and current commercial policies.
Some jewellers publish exchange programmes with deductions. Others occasionally advertise zero-deduction exchange offers subject to product, purity and promotional conditions. Some programmes apply only when the customer buys new jewellery, while a cash-sale route can use a different calculation entirely.
That means a statement such as “jewellers always deduct 5%” or “old gold always loses 10%” is not a reliable general rule.
The correct question is: what exactly is this buyer deducting from this item, and from which starting value?
6. Get comparable quotes before an irreversible sale
Where practical, obtain more than one quote before handing over the item permanently.
But multiple numbers are useful only when they represent the same thing. One buyer may quote after deducting stones, another may display a gross amount before adjustments, and an exchange programme may include incentives that are available only if you purchase a new item.
Normalize the comparison to the same purity, recoverable gold weight and transaction type.
| Quote item | Buyer A | Buyer B |
|---|---|---|
| Accepted purity | Record actual value | Record actual value |
| Recoverable gold weight | Record actual value | Record actual value |
| Reference gold rate | Record actual rate | Record actual rate |
| Gross metal value | Record calculation | Record calculation |
| Deductions or spread | List separately | List separately |
| Stone or other value | Separate if applicable | Separate if applicable |
| Transaction type | Cash sale or exchange | Cash sale or exchange |
| Final payable amount | Record final quote | Record final quote |
7. Do not treat an exchange quote as the same as a cash-sale quote
An exchange programme can be economically different from selling gold for cash.
A jeweller may offer a favourable old-gold adjustment only when the customer uses the proceeds toward new jewellery. The new purchase can itself contain making charges, design costs or other commercial terms.
So compare the whole transaction, not only the headline exchange percentage.
8. Understand testing and melting before you consent
Buyers can use different purity-verification methods. Some commercial processes can include melting before final valuation.
If a process is destructive or irreversible, understand when that step occurs, whether you can still decline the transaction afterward, and how the item will be handled if you do not accept the final quote.
If you want independent purity evidence before agreeing to a buyer’s process, BIS-recognised Assaying and Hallmarking Centres provide a separate testing route for consumers.
9. Preserve your invoice and testing evidence
An invoice is useful even when a particular buyer does not insist on it.
BIS consumer guidance emphasises authentic purchase invoices and preserving evidence for complaints and redressal. Some jeweller exchange programmes also require original invoices or certificates for particular products or terms.
Keep, where available:
- original purchase invoice;
- hallmark or HUID details;
- bullion refinery or mint documentation;
- independent assay report;
- written or digital buyer quote;
- purity and weight readings;
- sale receipt; and
- payment proof.
10. Hallmarking does not guarantee a resale price
A hallmark or verified purity helps establish what the metal is. It does not force a commercial buyer to offer a particular spread or final payment.
A buyer can still apply its own current commercial terms, subject to applicable law and its stated process. This is why purity verification and quote comparison are separate stages.
11. Check the tax impact before treating the quote as your final proceeds
Selling physical gold can create a capital-gains tax consequence. The final tax treatment depends on current law and the seller’s facts, including acquisition cost, holding period and whether the gold was bought, gifted or inherited.
Current 2026 tax guidance generally treats physical gold held for more than 24 months as long-term for capital-gains purposes, while shorter holdings are generally treated as short-term. Exact tax payable cannot be determined from the buyer’s quote alone.
For inherited or gifted gold, cost and holding-period rules can require additional analysis. Verify current Income Tax guidance or obtain appropriate tax advice before assuming the amount received from the buyer is the amount you ultimately keep.
12. The final go/no-go check
Before accepting an offer, you should be able to reconstruct the quote in plain language:
recoverable gold weight × accepted purity × buyer’s reference rate, adjusted for clearly identified deductions or spread, with stones or other components treated separately.
If you cannot explain how the buyer moved from the item in your hand to the final amount offered, the quote is not yet transparent enough for a confident comparison.
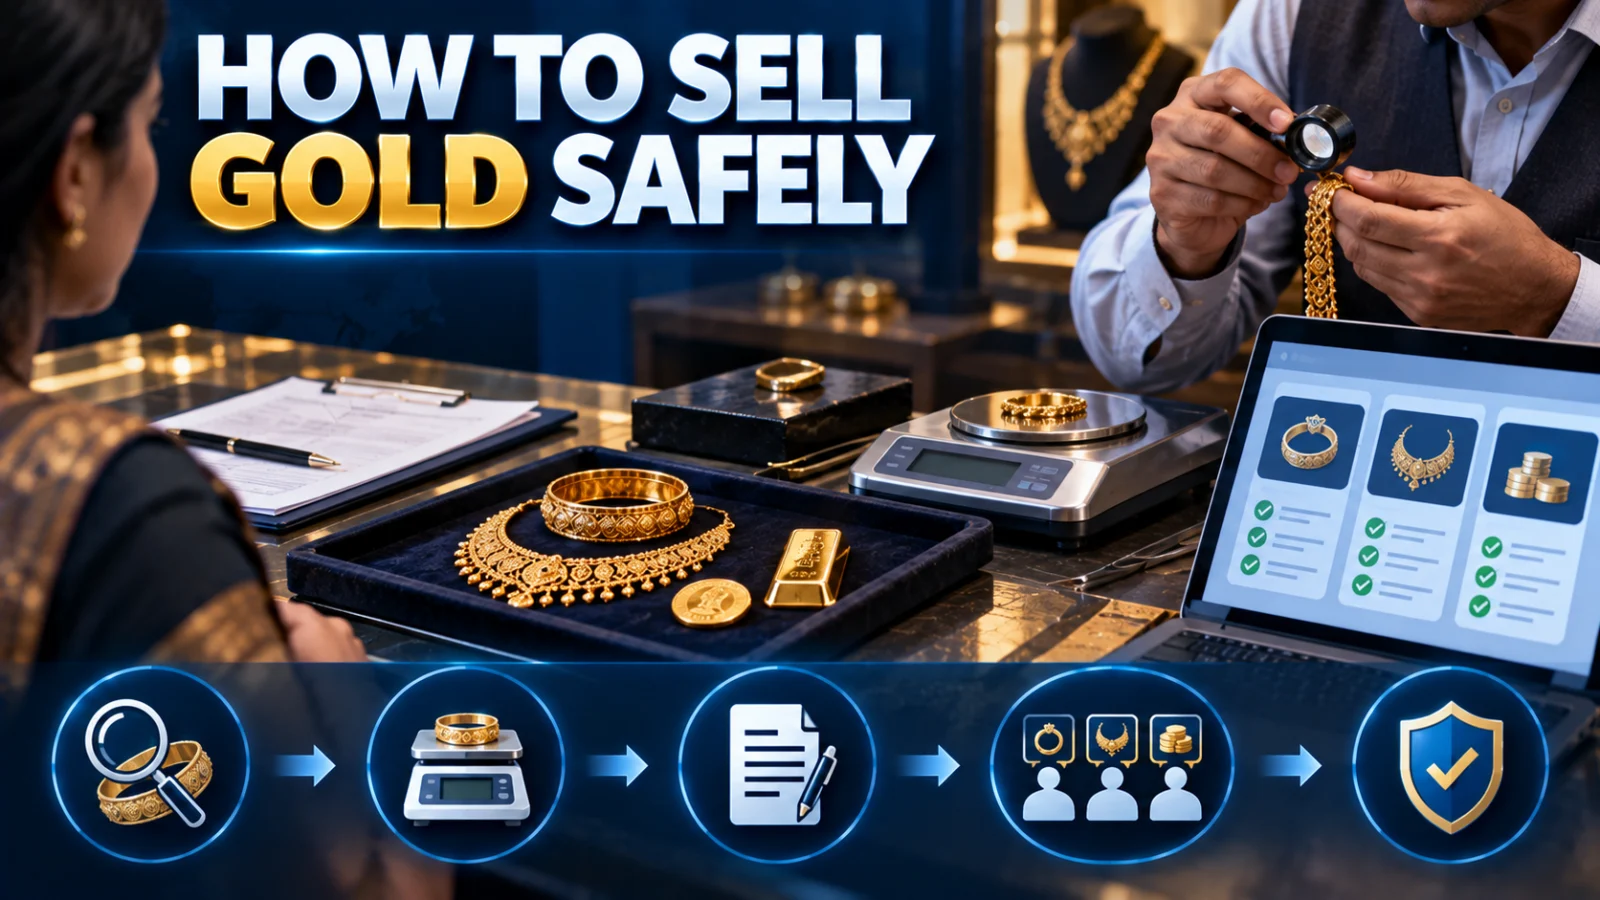
- Identify jewellery, coin or bar.
- Collect invoice and certification evidence.
- Verify purity if uncertain.
- Establish net recoverable gold weight.
- Separate stones and non-gold components.
- Record the reference gold rate.
- List every deduction and spread.
- Keep cash sale and exchange quotes separate.
- Obtain comparable quotes where practical.
- Understand destructive testing or melting.
- Preserve transaction evidence.
- Check current tax implications.
What this checklist cannot tell you
No article can provide one permanent “fair deduction” percentage for every gold sale in India. Buyer spreads, promotional exchange terms, stone treatment, testing methods and documentation requirements can change.
The purpose of the checklist is not to guarantee the highest possible price. It is to reduce avoidable information loss by making the transaction understandable and comparable before you commit.
Verification note
TPS reviewed BIS consumer-protection, hallmarking and invoice guidance, then compared current jeweller and finance-source material on purity testing, net weight, deductions, exchange structures and gold-sale taxation. Seller-specific deductions and offers were treated as variable commercial terms rather than universal rules.
Limitations and unresolved facts
Exact buyer deductions, buyback spreads, melting or testing terms, stone valuation, invoice requirements and exchange incentives remain buyer- and product-specific. Personal tax liability depends on acquisition and holding-period facts. TPS has not established one universal best buyer, one universal deduction rate or a guaranteed resale outcome.