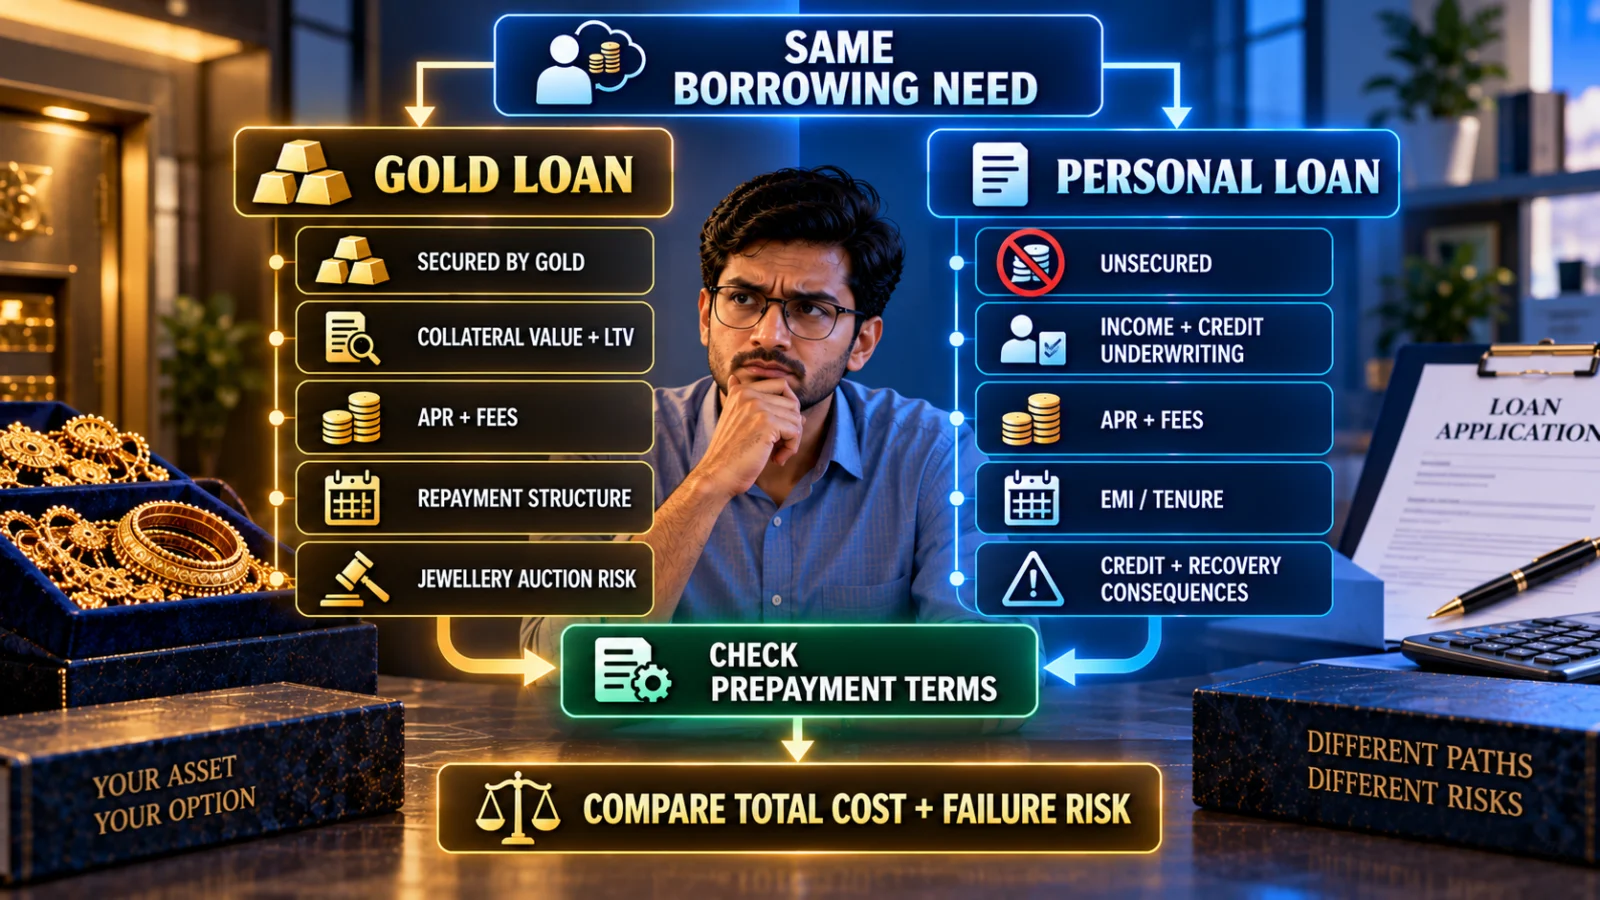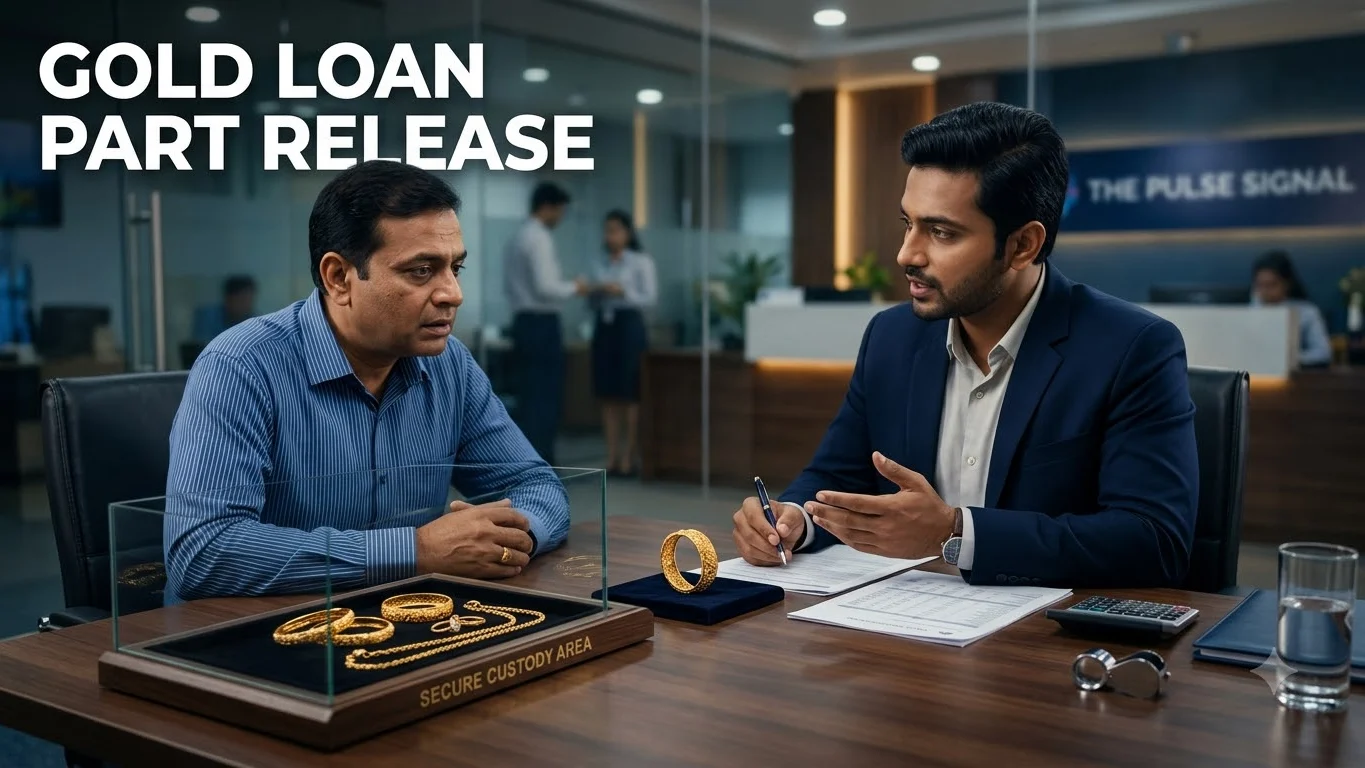
A gold loan part payment does not automatically mean that the lender must return part of your jewellery. Some lenders offer a separate part-release facility that lets eligible borrowers repay enough of the outstanding loan and retrieve selected pledged ornaments while keeping the rest of the loan open. Other lenders or products do not permit part release at all.
The practical distinction matters if you are paying specifically because you need a necklace, ring, bangles or another pledged item back. Before making the payment, confirm that your exact loan scheme supports part release and ask the lender how much must be paid for the particular collateral you want released.
Gold loan part payment and jewellery part release are two different things
| Action | What it normally changes | Does jewellery automatically come back? |
|---|---|---|
| Part payment | Reduces the outstanding loan or dues according to the lender’s account rules. | No. Payment alone does not establish an automatic collateral release. |
| Part release | Returns one or more identified pledged ornaments while the remaining loan continues. | Only where the lender and product permit it and the remaining collateral is sufficient. |
| Full repayment or settlement | Closes or settles the outstanding loan according to the applicable terms. | The current RBI framework expressly addresses return of pledged collateral after full repayment or settlement. |
Does RBI require every gold-loan lender to offer part release?
No universal part-release entitlement was identified in the current Reserve Bank of India Lending Against Gold and Silver Collateral Directions, 2025. The current framework requires lenders to maintain the applicable loan-to-value, or LTV, requirements through the loan tenor and expressly addresses release of pledged collateral after full repayment or settlement.
Older RBI prudential guidance for urban co-operative banks expressly contemplated part release after part repayment when the jewellery left with the lender continued to provide sufficient security with the required margin. That historical rule is useful context, but it should not be rewritten as proof that every regulated lender must provide a part-release facility under every gold-loan product today.
Current lender policies show why you need to check your exact loan
Current lender disclosures reviewed by TPS show materially different servicing policies. Bajaj Finance, Aditya Birla Finance, Muthoot Finance and IIFL publish part-release facilities or processes for eligible gold loans. Kotak Bank, by contrast, states that part release of ornaments is not possible under its relevant gold-loan servicing terms.
This variation means another lender’s website cannot establish your own entitlement. The controlling answer for your account comes from the applicable RBI framework together with your lender’s current product terms, loan agreement and servicing policy.
Why the remaining jewellery matters after part release
A lender does not evaluate a part-release request only by asking how much cash you have paid. It also has to consider the loan balance that will remain and the value of the collateral that will remain pledged.
The current RBI framework defines LTV using the outstanding loan and the value of pledged eligible collateral and requires the prescribed LTV to be maintained through the loan tenor. That is why a lender may calculate how much principal or other applicable dues must be paid before a particular ornament can be released.
For example, if releasing one high-value ornament would leave too little eligible collateral against the remaining outstanding loan, the lender may require a larger repayment, offer release of a different item, or refuse the requested release under the applicable scheme.
Can you choose exactly which ornament you want back?
Sometimes, but this is product- and process-specific. Current lender guidance shows that some part-release processes allow identified or selected ornaments to be released after the required payment and verification. The RBI framework also requires assaying and collateral records that identify pledged items and their valuation details.
That does not establish a universal right to choose any ornament regardless of its value. If several items were pledged, ask the lender to identify which packet or ornament can be released and what the remaining collateral value would be after that release.
How much must you repay before jewellery can be released?
There is no single RBI rupee amount or universal repayment percentage for every part-release request. The required payment can depend on the outstanding principal and dues, the value of the item being requested, the value of the jewellery remaining with the lender, the applicable LTV and the lender’s servicing rules.
This is why it is risky to calculate the payment yourself using only the original loan amount or the current retail gold price. Ask the lender for the amount required specifically for the proposed release and, where available, the resulting outstanding balance and remaining collateral value.
Can lenders charge for part release?
Yes, lender-specific charges can apply. Current product disclosures reviewed by TPS show that some lenders publish part-release or convenience charges, while others advertise part release without a separate charge under particular products or conditions.
Do not assume another lender’s fee structure applies to your account. Check the current schedule of charges, loan agreement or key fact statement for your loan before proceeding.
What should you verify before making a part payment to get jewellery back?
- Does your exact gold-loan scheme permit part release?
- Which pledged ornament, packet or item can be released?
- How much principal and other applicable dues must be paid first?
- What outstanding balance will remain after the payment?
- What collateral value will remain after the selected jewellery is released?
- Will the continuing loan remain within the applicable LTV requirement?
- Are there any part-release, convenience or servicing charges?
- Which branch, identity documents or account documents are required for collection?
If your purpose is specifically to recover jewellery rather than merely reduce interest or principal, confirm these points before transferring money. A payment posted to the account does not by itself prove that a particular ornament is ready for release.
What if your lender does not offer part release?
If the product terms do not support partial collateral release, you may need to fully repay or settle the loan before the pledged jewellery is returned. Do not assume that a lender must copy a part-release facility offered by another bank or NBFC.
If you believe the lender is acting contrary to your written agreement, disclosed servicing policy or applicable RBI requirements, first obtain the lender’s written explanation and use its grievance process. The issue is different from simply disliking a product rule that was disclosed and validly applies to the loan.
Bottom line
Gold loan part payment and jewellery part release are related, but they are not the same transaction. Some lenders allow borrowers to repay enough of the loan and retrieve selected pledged ornaments before full closure; others do not. The amount required depends on the continuing loan, remaining collateral and the lender’s applicable rules.
Before paying specifically to get jewellery back, ask the lender to confirm in writing that part release is available for your loan, identify the item that can be released, state the required payment and explain the remaining collateral position.
Verification note
TPS reviewed the current RBI Lending Against Gold and Silver Collateral Directions, 2025, older RBI prudential guidance that expressly discussed part release, and current lender disclosures showing both permitted and prohibited part-release policies.
Limitations and unresolved facts
Part-release availability, minimum repayment, item selection, fees, documentation and collection procedures can differ by lender and product. The current harmonised RBI Directions reviewed by TPS do not establish a universal part-release entitlement for every borrower. This article does not determine the amount required for any individual loan account.