
SEBI commodity derivatives position limits changed on September 9, 2026. The revised framework increases client-level limits for agricultural commodity derivatives, changes the definition of a Broad Commodity, caps monetary penalties for open-interest breaches and tightens consequences when violations continue or repeat.
What are the new SEBI commodity derivatives position limits?
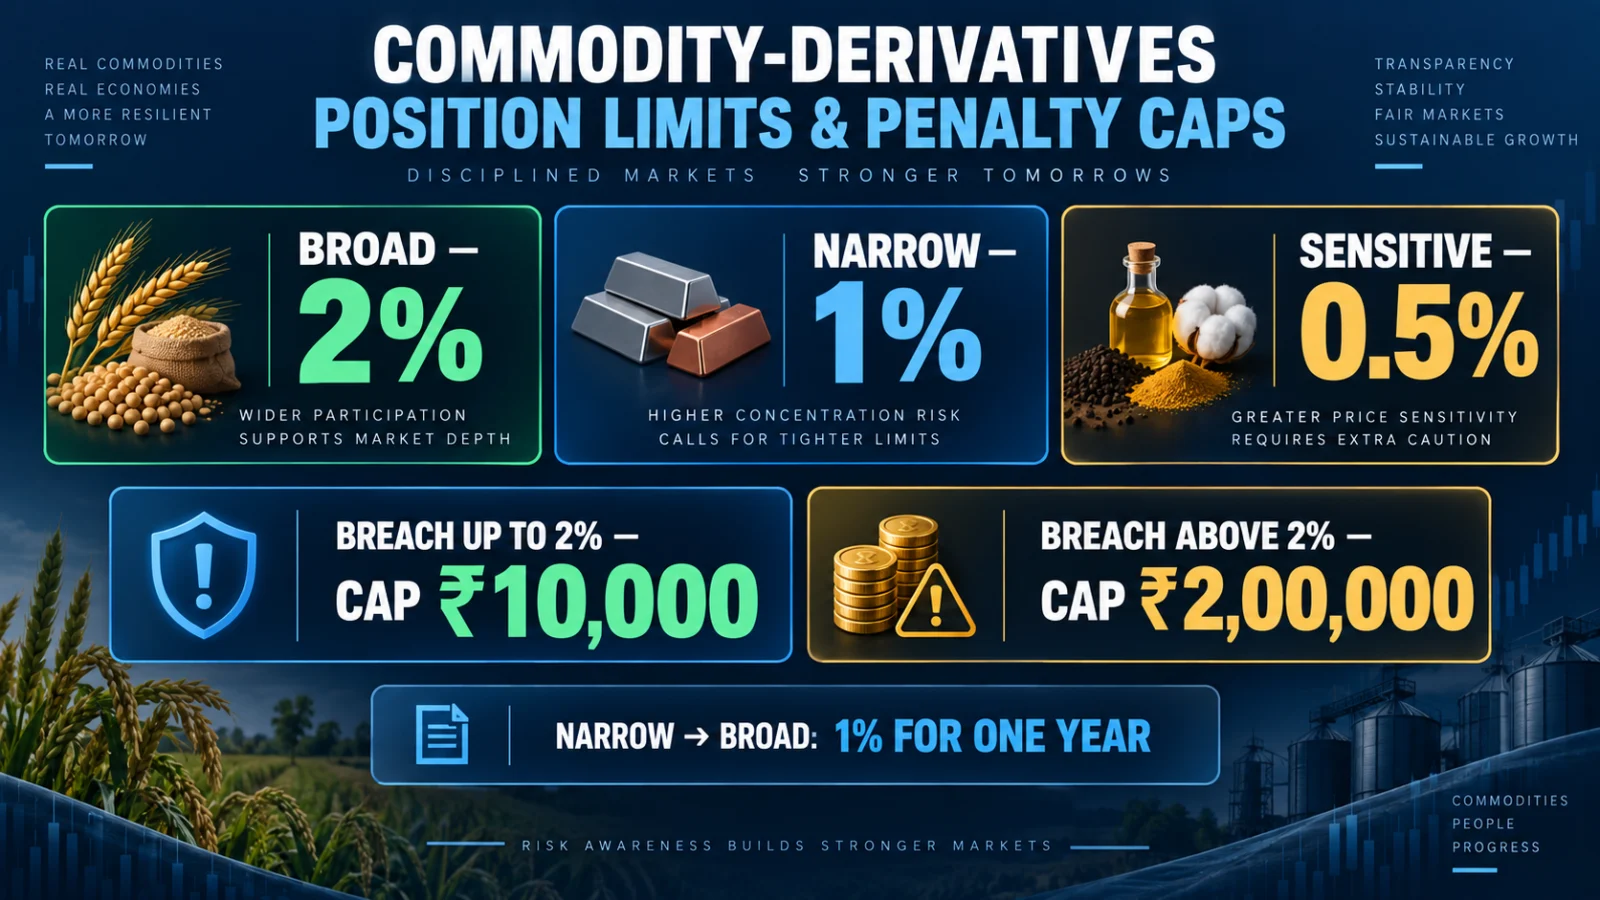
For agricultural commodity derivatives, the revised client-level limits are 2% of deliverable supply for Broad commodities, 1% for Narrow commodities and 0.5% for Sensitive commodities.
The earlier limits were 1%, 0.5% and 0.25% respectively. The change therefore doubles the percentage limit within each category, but it does not mean every agricultural commodity automatically receives a 2% limit.
Old vs new client position limits
| Commodity category | Earlier client limit | New client limit |
|---|---|---|
| Broad | 1% of deliverable supply | 2% of deliverable supply |
| Narrow | 0.5% | 1% |
| Sensitive | 0.25% | 0.5% |
What now counts as a Broad Commodity?
A commodity can qualify as Broad if it is not classified as Sensitive and meets either of two five-year average deliverable-supply tests: at least 10 lakh metric tonnes in physical terms or at least ₹5,000 crore in monetary terms.
The important change is that the quantitative and monetary tests now operate on an either/or basis rather than requiring both thresholds to be met.
What happens if a Narrow Commodity now qualifies as Broad?
A commodity moving from Narrow to Broad because of the revised definition does not immediately jump to the full 2% client limit.
Its client limit remains at 1% for one year. After that period, the recognised exchange may review the market and increase the limit to 2%.
How are position-limit breach penalties calculated?
SEBI has introduced monetary caps while retaining a formula-based calculation. The applicable penalty is calculated using the extent of the excess position, closing price, number of violation days and the specified penalty rate, subject to the applicable cap.
| Breach size | Penalty treatment | Maximum cap |
|---|---|---|
| Up to 2% above prescribed limit | Formula-based penalty | ₹10,000 |
| More than 2% above prescribed limit | Formula-based penalty | ₹2,00,000 |
For a breach of more than 2%, the reviewed rule text applies the calculation limit exceeded × closing price × days of violation × 2%, subject to the ₹2 lakh ceiling. The lower-breach band is likewise capped at ₹10,000 rather than becoming a flat ₹10,000 charge.
How quickly must an excess position be corrected?
The trading member must bring the client’s position back within the prescribed limit by the next trading day after the violation.
If the excess continues beyond the permitted correction window, the recognised exchange can square off the excess position without further notice under the revised framework.
What happens after repeated breaches?
Repeated violations can trigger consequences beyond the ordinary daily breach penalty. The revised framework provides for a one-day square-off mode in specified repeated-breach situations and can impose an additional penalty equivalent to the open-interest violation penalty.
The reviewed final-rule reporting also identifies an exception where the violation results exclusively from position clubbing. Brokers and compliance teams should check the exact exchange implementation before applying the repeat-breach rule to a live client case.
Does the rule apply immediately?
Yes. The September 9 circular states that the revised framework comes into force with immediate effect.
MCX also published Trading & Surveillance Circular 513 on September 9 under the same title, confirming that the SEBI revision has reached at least one recognised commodity exchange’s operational circular stream. That removes the earlier uncertainty about whether any exchange implementation notice had appeared.
However, an exchange circular carrying the SEBI framework does not by itself establish every commodity’s revised classification, transition status or contract-specific numerical limit.
How do you find the exact limit for a contract?
The SEBI-level percentages alone are not enough to determine every live contract limit. The exact number depends on the commodity’s classification, its deliverable-supply calculation and the recognised exchange’s current implementation data.
Check the commodity category
Confirm whether the commodity is currently classified as Broad, Narrow or Sensitive.
Check transition status
If a commodity has moved from Narrow to Broad under the revised definition, verify whether it is still inside the one-year 1% transition period.
Check the exchange circulars and limits
MCX has already published Circular 513 carrying the revised framework. For a live position, use the applicable recognised exchange’s latest commodity-level or contract-level position-limit information rather than relying only on the SEBI percentage table.
Monitor breaches separately
Track the size and duration of an excess position because the applicable penalty and repeat-breach consequences depend on the actual violation state.
What did not change?
The revised rule does not create one universal 2% limit for every agricultural commodity. Position limits still depend on commodity classification and deliverable supply, and exchanges remain responsible for operational implementation and monitoring.
The September 9 circular also does not rewrite unrelated equity-derivatives position-limit rules.
What should brokers and compliance teams do now?
- refresh internal Broad, Narrow and Sensitive client-limit tables;
- identify commodities affected by the revised Broad definition;
- track the one-year transition for Narrow-to-Broad reclassification;
- update breach-penalty logic for the ₹10,000 and ₹2 lakh caps;
- ensure excess positions are corrected by the next trading day;
- monitor repeated violations and square-off consequences separately;
- check the applicable exchange’s latest circulars, classifications and position-limit data before relying on a contract-specific numerical limit.
What happens next?
The remaining operational questions are commodity-by-commodity classification, transition status and current contract-level limits across recognised exchanges. Any later exchange table, reclassification or SEBI clarification that changes those answers would materially affect this guidance.
The one-year transition for commodities moving from Narrow to Broad also remains important because those commodities stay at the 1% client limit during that transition rather than moving immediately to 2%.
Verification note
TPS reviewed SEBI’s September 9 circular listing, the May 2026 SEBI consultation, current final-rule reproductions and MCX’s September 9 Trading & Surveillance Circular 513 listing. The SEBI-level rule change and MCX’s exchange circular are confirmed. Commodity-by-commodity reclassification, transition status and exact contract-level revised limits remain dependent on current recognised-exchange information.