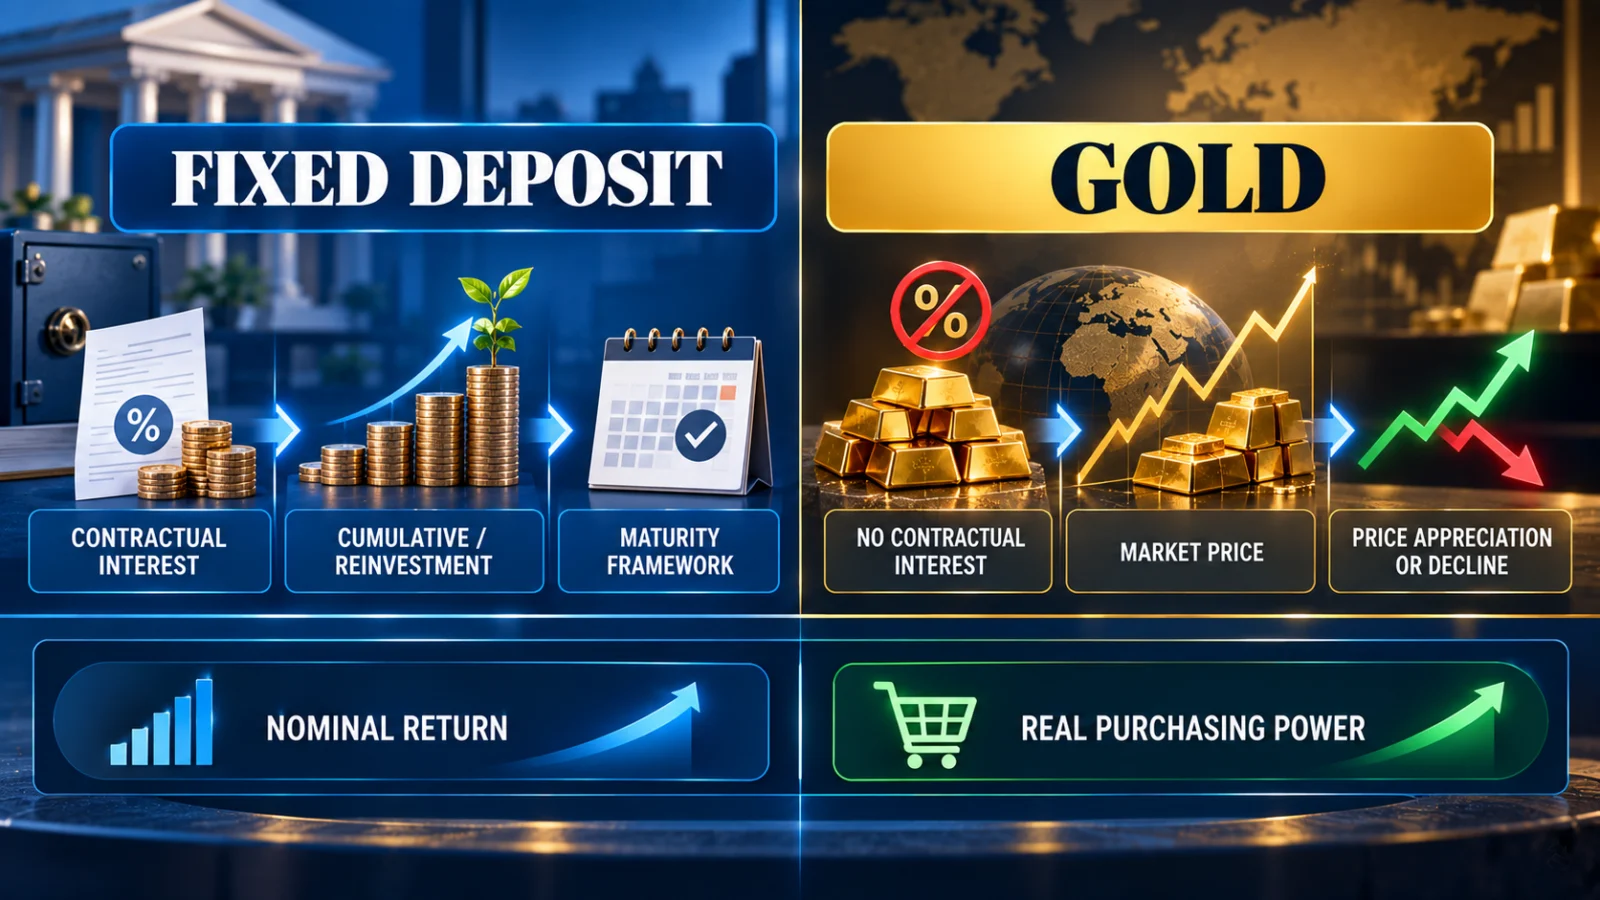
Gold vs fixed deposit is not simply a contest between two return percentages. A bank fixed deposit and gold build wealth through fundamentally different mechanisms. A cumulative or reinvestment FD can grow through contractual interest that is added back to the deposit, while gold pays no contractual interest and gains or loses value when its market price changes.
Fixed deposit
A bank FD has a defined rate and tenure when booked. In a cumulative or reinvestment structure, interest can be added back so the deposit compounds toward a maturity value, subject to the bank’s terms.
Gold
Gold has no contractual interest or maturity value. Its investment return comes from changes in market price, which can be positive or negative and is influenced by demand, macroeconomic conditions, risk, currency movements and other gold-market forces.
The central difference: contractual compounding versus market appreciation
For a cumulative FD, the basic wealth engine is straightforward: principal earns contractual interest, that interest is retained or reinvested, and the larger balance can earn further interest. The maturity framework is therefore substantially more predictable when the deposit is held according to its booked terms.
Gold works differently. Gold itself does not pay interest, dividends or another contractual cash flow. If the price rises over time, the market value of the investor’s gold exposure rises. If the price falls, the market value can fall.
It is therefore too simplistic to say that an FD compounds while gold does not. A cumulative FD has an internal contractual compounding mechanism. Gold has no such yield, although repeated price appreciation can still produce a compounded-looking increase in market value over a long period. The source of growth is different.
Not every FD compounds internally in the same way
The compounding distinction also depends on the deposit structure. A cumulative or reinvestment FD retains interest so that it contributes to future interest calculations. A periodic-payout FD can instead distribute interest to the depositor.
That means the statement “FD compounds” should always be read in the context of the actual deposit product. The important comparison with gold is that the FD’s return comes from contractual interest, while gold’s return comes from its future market price.
Does an FD give you a known maturity value?
A cumulative FD booked for a specified rate and tenure can provide a defined maturity framework when it is held according to its terms. That is materially different from gold, where there is no contractual future selling price.
However, the original FD maturity amount should not be treated as unconditional. RBI’s deposit framework allows premature withdrawal, but the interest applicable when a deposit is closed early can be based on the period for which the money actually remained with the bank. Banks can also apply their stated premature-withdrawal conditions.
Gold has no comparable contractual maturity date. The investor exits at whatever market value applies when the gold exposure is sold, subject to the costs and mechanics of the particular gold vehicle.
FD has lower market-price volatility — but that is not the same as unlimited protection
A conventional bank FD does not fluctuate daily like gold or listed market assets. That makes its nominal value path much more predictable.
But “predictable” should not be rewritten as “completely risk-free.” Deposit protection in India has a defined boundary.
DICGC currently insures eligible deposits, including fixed deposits, up to ₹5 lakh per depositor per bank in the same right and same capacity. The limit includes principal and accrued interest together, and eligible deposits across branches of the same bank are aggregated for this purpose.
This means TPS should not describe every rupee in every FD as government guaranteed. The contractual bank obligation and the statutory deposit-insurance ceiling are related but separate concepts.
Gold takes a different kind of risk
Gold does not have an issuer promising a maturity amount. Instead, the holder accepts market-price risk.
Gold can appreciate strongly over some periods, but it can also decline or remain weak for extended periods. World Gold Council research describes gold’s return as being influenced by a mix of investment demand, consumer demand, uncertainty, economic conditions, opportunity cost and currency effects.
That makes gold’s future value less predictable than a booked FD maturity framework, but it also means gold can respond differently from interest-bearing savings when inflation, currency or financial-market conditions change.
Inflation changes what an FD return actually means
An FD may deliver a positive nominal return while delivering a much smaller real purchasing-power gain after inflation and tax.
For example, an interest rate above zero does not by itself prove that the depositor became richer in real terms. What matters for purchasing power is the return remaining after inflation and applicable tax.
Gold is often discussed as an inflation or purchasing-power hedge because its market value has historically responded to monetary, inflation and currency conditions over long periods. That does not mean gold rises every year inflation is high, and it should not be described as a guaranteed annual inflation hedge.
Tax treatment also follows different return mechanisms
Interest from bank deposits is taxable income under the applicable income-tax framework. The effective after-tax FD return therefore depends partly on the depositor’s tax position.
Gold is taxed differently because gains generally arise when the asset is transferred rather than as annual contractual interest. The exact treatment depends on the type of gold exposure, holding period and current tax law.
This is another reason a simple pre-tax historical-return table can be misleading. A fair comparison should distinguish gross return, tax treatment and the actual gold or deposit vehicle being used.
Liquidity is not a one-word comparison either
FDs are often described as less liquid because they have a booked tenure, but many bank FDs can be closed prematurely. The trade-off is that the applicable interest or penalty terms may change the amount received.
Gold liquidity depends heavily on the form of gold. A listed Gold ETF, a bullion coin and jewellery do not have identical exit mechanics or costs.
That means “gold is more liquid” or “FD is more liquid” is too broad without identifying the actual products being compared.
Gold can play a portfolio role that an FD does not
Gold should not be evaluated only through its standalone return. World Gold Council India research has also examined gold as a portfolio diversifier and found that, in its historical hypothetical INR portfolios, adding gold improved several risk-adjusted measures and reduced drawdowns.
That finding does not prove that gold should replace an FD or that a particular gold allocation is right for every investor. It shows that gold can contribute something different from a contractual savings product because its market behaviour is driven by different forces.
The related TPS comparison of gold vs equity for long-term wealth in India examines a different question: gold compared with ownership in productive businesses. This page focuses on gold compared with contractual bank savings.
Gold vs fixed deposit: what actually differs
| Dimension | Fixed deposit | Gold |
|---|---|---|
| Return source | Contractual interest | Market-price appreciation or depreciation |
| Internal compounding | Cumulative/reinvestment FDs can compound interest internally | No contractual yield; value changes through market price |
| Maturity framework | Defined by booked rate, tenure and terms | No predetermined maturity value |
| Market-price volatility | Generally very low for the deposit itself | Can rise or fall materially |
| Inflation risk | Positive nominal return can still produce weak real return after inflation and tax | Historically has shown inflation and currency sensitivity, but not a guaranteed hedge |
| Protection framework | Bank obligation plus DICGC coverage within statutory limits for eligible deposits | No deposit-insurance framework; value depends on the asset and custody structure |
| Early exit | Often possible but may alter applicable interest or involve penalties | Depends on the specific gold vehicle and market conditions |
| Portfolio diversification | Primarily provides contractual savings/income characteristics | Historically has provided diversification in many portfolios |
Why a recent return winner does not settle the decision
Gold may outperform FDs dramatically during some historical periods. During other periods, gold can stagnate or decline while an FD continues accruing contractual interest.
Using one five-year or ten-year period to declare a permanent winner therefore answers the wrong question. An FD rate is known when the deposit is booked, while gold’s future return is unknown.
A historical comparison can describe what happened. It cannot convert gold’s past CAGR into a contractual future return.
Which job is the saver actually trying to solve?
The evidence supports a role-based comparison rather than a universal recommendation.
If the primary need is a defined nominal maturity framework and contractual interest, an FD is solving that problem directly. If the objective includes market-linked appreciation, currency or inflation sensitivity and portfolio diversification, gold is providing a different type of exposure.
Those jobs can coexist. The evidence reviewed by TPS does not support one universal gold-versus-FD winner or one allocation that fits every Indian saver.
Personal suitability depends on the savings goal, time horizon, liquidity needs, tax position, amount held with one bank, chosen gold vehicle, tolerance for market fluctuations and other assets already owned.
Bottom line
FD and gold do not build wealth through the same engine. A cumulative FD can compound contractual interest toward a defined maturity framework. Gold generates no contractual interest and its wealth outcome depends on market-price movement.
The practical comparison is therefore not simply “which returned more last year?” It is whether the saver needs contractual nominal predictability, market-linked appreciation and diversification, or some combination of those functions.
Verification note
TPS reviewed RBI term-deposit rules, DICGC deposit-insurance guidance, current official tax material and World Gold Council research on gold return drivers and portfolio behaviour. Current gold-versus-FD competitor pages were used to identify reader confusion and comparison patterns, not as controlling evidence for banking or tax rules.
Limitations and unresolved facts
Future gold returns, FD rates, inflation and tax rules are unknown. Bank-specific premature-withdrawal conditions and rates vary. Gold liquidity, costs and taxation differ by investment vehicle. Historical gold diversification or inflation behaviour does not guarantee future performance, and no universal gold-versus-FD allocation was established.